










Goodluck India Q2 FY27 Income Rises 37.7% to ₹13.74 Billion
Key highlights
- Goodluck India reported Q2 FY27 total income of ₹13.74 billion, up 37.7% year on year.
- Q2 FY27 sales volume rose 18.1% to 133,374 metric tonnes.
- Q2 FY27 EBITDA increased to ₹1.27 billion, while EBITDA margin declined 55 basis points to 9.3%.
- H1 FY27 total income reached ₹26.66 billion, up 34.4% year on year.
powered by IRIS
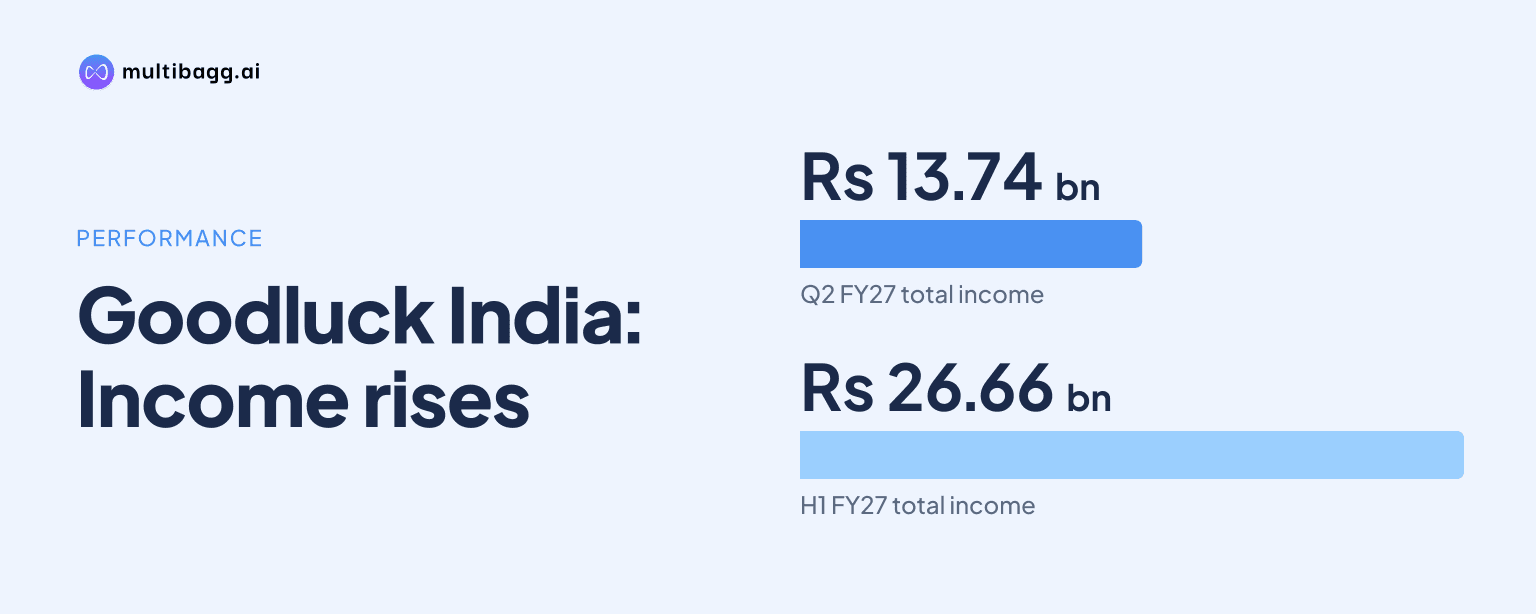
For Q2 FY27, Goodluck India Limited reported total income of ₹13.74 billion, up 37.7% year on year, supported by an 18.1% increase in sales volume to 133,374 metric tonnes. EBITDA rose 30.1% to ₹1.27 billion, although higher fuel and global freight costs reduced the operating margin to 9.3%.
Know Goodluck India inside out
Results, valuation, peers and who's buying, in one view.
How did Goodluck India perform in Q2 FY27?
Goodluck India recorded consolidated total income of ₹13.74 billion for the quarter ended September 30, 2026, compared with ₹9.98 billion in Q2 FY26. The reported 37.7% year-on-year increase was higher than the 18.1% rise in quarterly sales volume, which reached 133,374 metric tonnes from 112,937 metric tonnes a year earlier.
Consolidated EBITDA increased to ₹1.27 billion from ₹0.98 billion in Q2 FY26. This represented growth of 30.1% to 30.7%, depending on the reported calculation in the company materials. Consolidated net profit rose 18.8% to ₹0.51 billion from ₹0.43 billion. Revenue growth therefore translated into higher operating profit and profit after tax, but at a slower pace than total income.
The company released its Q2 and H1 FY27 investor presentation in late October, covering results for the quarter and six months ended September 30, 2026. The available figures are based on that presentation, and no earnings-call transcript for the quarter had been published in the supplied material.
Why did Goodluck India's quarterly margins decline?
Goodluck India's Q2 FY27 EBITDA margin declined to 9.3% from 9.8% in the corresponding quarter last year, a moderation of 55 basis points. Its PAT margin fell to 3.7% from 4.3%, down 59 basis points. The company attributed the operating-margin pressure to higher fuel and global freight costs.
The margin trend was also visible on a sequential basis. Q2 EBITDA was reported to be 8.7% lower than in the preceding quarter, while net profit was 24.6% lower sequentially. These movements occurred despite the strong year-on-year improvement in income, indicating that quarterly cost conditions affected profitability during the period.
Freight and fuel are relevant costs for a manufacturer supplying steel-based engineered products across domestic and export markets. The reported data does not provide a separate cost breakup or management outlook for these expenses. It therefore establishes the source of the Q2 margin pressure but does not quantify the contribution of each cost item.
What were Goodluck India's H1 FY27 financial results?
Goodluck India's H1 FY27 total income rose 34.4% year on year to ₹26.66 billion, from ₹19.84 billion in H1 FY26. Sales volume for the six-month period increased 13.5% to 256,093 metric tonnes, compared with 225,678 metric tonnes in the prior-year period.
Cumulative EBITDA for H1 FY27 grew 37.8% to ₹2.67 billion from ₹1.94 billion. Unlike the quarterly movement, the half-year EBITDA margin improved by 25 basis points to 10.0%, from 9.8% in H1 FY26. This suggests that the first-half operating performance, taken as a whole, retained a modest margin improvement despite the Q2 cost pressure.
Got a follow-up? Ask IRIS
What operational developments did Goodluck India report?
Goodluck India describes itself as a manufacturer of precision-engineered steel products and also has defence manufacturing operations through Goodluck Defence and Aerospace Limited. During the quarter, it received in-principle approval for the amalgamation of Goodluck Defence and Aerospace Limited and Goodluck Green Energy Limited into Goodluck India.
The company said defence revenue is expected later in FY27 after validation activities are completed. This is a stated operational update rather than reported Q2 defence revenue. The available release does not specify the value of anticipated defence revenue, a validation completion date, or a revised financial target following the proposed amalgamation.
The merger-related approval is relevant because it would bring the two named entities into Goodluck India, subject to the applicable process. For investors, the disclosed near-term point is that any defence contribution remains linked to validation activities and is expected later in the current financial year, rather than being reflected as a separately quantified Q2 result.
How do the Q2 results affect Goodluck India investors?
Goodluck India's reported figures show that volume expansion and income growth remained strong in Q2 FY27. Total income grew by 37.7%, while sales volume increased by 18.1%. The difference between these rates is part of the reported financial outcome, but the supplied information does not provide a detailed explanation such as product mix, pricing or geography.
For investors, the principal offset was the reduction in quarterly EBITDA and PAT margins. EBITDA grew 30.1% while total income grew 37.7%, and net profit grew 18.8%. Higher freight and fuel costs were specifically cited as the reason for the operating-margin decline, making cost conditions an important factor alongside sales volume in assessing the quarter.
The H1 results provide a broader view. Half-year income grew 34.4% and EBITDA grew 37.8%, with EBITDA margin at 10.0%. The contrast between the H1 margin expansion and Q2 margin moderation shows that the company entered the second half with higher cumulative operating profitability, while the latest quarter faced identifiable cost pressure.
Conclusion
Goodluck India delivered strong Q2 FY27 income growth, with total income reaching ₹13.74 billion and volume rising to 133,374 metric tonnes. EBITDA and net profit also increased year on year, but fuel and global freight costs narrowed quarterly operating and net profit margins. The H1 data remained stronger on a cumulative margin basis, with EBITDA margin improving to 10.0%.
The next disclosed developments to watch are the completion of validation activities tied to expected defence revenue later in FY27 and progress on the proposed amalgamation of Goodluck Defence and Aerospace Limited and Goodluck Green Energy Limited into Goodluck India. Cost movement in freight and fuel will also remain relevant to quarterly margins.