










Hero MotoCorp Wins ITAT Relief on Rs 27 Crore Tax Demand
Key highlights
- The ITAT allowed Hero MotoCorp's tax matters on 20 November 2026.
- The filing concerns relief on an outstanding income-tax demand of about Rs 27 crore.
- The proceedings cover six assessment years from 2013-14 to 2017-18 and 2019-20.
- Earlier CIT(A) orders reduced the tax demand from Rs 177.96 crore to Rs 27 crore.
powered by IRIS
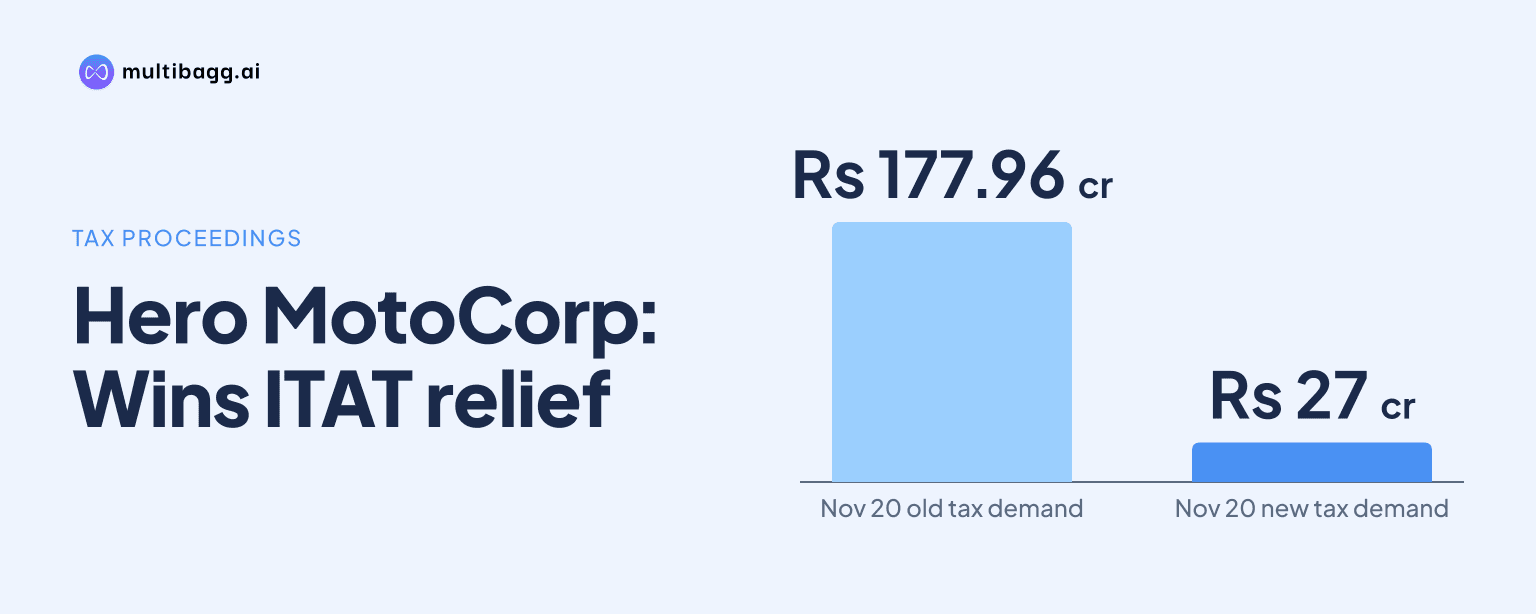
Hero MotoCorp received relief on an outstanding income-tax demand of about Rs 27 crore after the Income Tax Appellate Tribunal allowed its matters on 20 November 2026, covering six assessment years. The decision is significant because the demand was the residual amount after earlier appellate orders had reduced a larger tax claim.
Know Hero MotoCorp inside out
Results, valuation, peers and who's buying, in one view.
What did the ITAT decide in Hero MotoCorp's tax matter?
The Income Tax Appellate Tribunal recorded Hero MotoCorp's matters as allowed on 20 November 2026. The tribunal registry identifies the proceedings as ITA cases, with the available records including ITAT-ITA 4956/DEL/2026, ITAT-ITA 4959/DEL/2026 and ITAT-ITA 4960/DEL/2026.
The listed petitioner in these proceedings is M/S Hero MotoCorp Ltd., New Delhi, while the respondent is the Joint Commissioner of Income Tax, OSD, Central Circle-27, New Delhi. The matters were heard by a bench comprising Shri Mahavir Singh and Shri S. Rifaur Rahman. The registry shows four order documents on record for each of the listed cases.
How did Hero MotoCorp's Rs 27 crore tax demand arise?
Hero MotoCorp's remaining demand followed reassessment proceedings covering assessment years 2013-14 to 2017-18 and 2019-20. Earlier, the Income Tax Authorities had disallowed certain expenses incurred in prior periods, resulting in a demand that the company stated was Rs 27 crore, compared with Rs 178 crore in the previous year.
The company had challenged the reassessment orders through the appellate process. Commissioner of Income Tax (Appeals)-29 orders dated 9 and 10 March 2026 reduced the tax demand from Rs 177.96 crore to Rs 27 crore. Hero MotoCorp received those appeal orders on 11 March 2026 and had stated that it intended to contest the balance demand before the ITAT.
What were the main tax figures before the ITAT order?
The available disclosures show that the earlier appeal stage substantially lowered the tax exposure before the ITAT ruling. The filing refers to ITAT relief on the outstanding demand of approximately Rs 27 crore, while the tribunal registry's disposal status is recorded as allowed.
The order disclosure does not quantify any further reduction, refund, payment reversal or final cash impact arising from the ITAT decision. It also does not state the detailed reasoning contained in the tribunal's orders. Therefore, the confirmed development is the allowed disposal and the relief on the approximately Rs 27 crore outstanding demand.
Got a follow-up? Ask IRIS
Why was the dispute important for Hero MotoCorp?
The dispute related to tax treatment in reassessment proceedings across six assessment years, making it a multi-year compliance matter rather than a current-period operating issue. A tax demand can affect reported contingencies, legal costs and disclosures even where a company believes its legal position is supportable.
In its earlier annual disclosure, Hero MotoCorp said it had evaluated the Rs 27 crore demand using external legal advice, supporting documents and other available information. It concluded that no provision was required because it considered acceptance of its position probable upon ultimate resolution. The ITAT's allowed disposal is relevant to that assessment.
The broader tax issue has also been discussed in the context of transfers of components between company units. The available background indicates that the dispute involved the tax department's view of margins on certain internal transfers, while Hero MotoCorp maintained that components obtained from third-party vendors were transferred at purchase cost with applicable freight costs. The supplied record does not provide the full text of the latest ITAT order or establish the precise grounds accepted in each case.
How does the ITAT relief affect investors and company disclosures?
For investors, the immediate relevance is a reduction in uncertainty around an income-tax demand that had remained at approximately Rs 27 crore after the earlier CIT(A) relief. The ITAT's allowed status supports Hero MotoCorp's previously disclosed view that a provision was not required, although the filing does not state any change to the company's accounts or earnings as a result of the order.
The decision should also be read alongside the earlier progression of the case. The demand had already fallen by Rs 150.96 crore at the CIT(A) stage, from Rs 177.96 crore to Rs 27 crore. The current filing concerns relief on that residual demand, not a new tax demand or a change in Hero MotoCorp's vehicle sales, production or operating performance.
Investors will need to rely on future company disclosures for implementation details, including whether Hero MotoCorp seeks a refund or demand reduction and whether any amount is reflected in financial statements. The tribunal registry confirms the decision date and allowed disposal, but the supplied material does not specify a revised final liability following the 20 November order.
Conclusion
Hero MotoCorp has received a favourable ITAT outcome in a long-running tax matter spanning six assessment years. The tribunal allowed the matters on 20 November 2026, providing relief on an outstanding demand of about Rs 27 crore that remained after the earlier appellate reduction from Rs 177.96 crore.
The next point to watch is Hero MotoCorp's disclosure on implementing the ITAT outcome, including any application for refund or demand reduction and any stated accounting effect. The supplied record does not disclose a next hearing date, a final revised demand amount or the detailed text of the tribunal's orders.