










IIFL Finance offers Ingot SG two board nominees at 10%
Key highlights
- Ingot SG may nominate 2 IIFL Finance directors while holding 5,35,68,952 equity shares or CCPS, described as about 10%.
- The 4,01,76,714-share or CCPS threshold gives Ingot SG nomination rights at IIFL Finance, IIFL Home Finance and IIFL Samasta Finance.
- Ingot SG’s post-issue holding is shown at 15.57% on the stated fully diluted basis.
- IIFL Finance has scheduled shareholder approval for December 4, 2026.
powered by IRIS
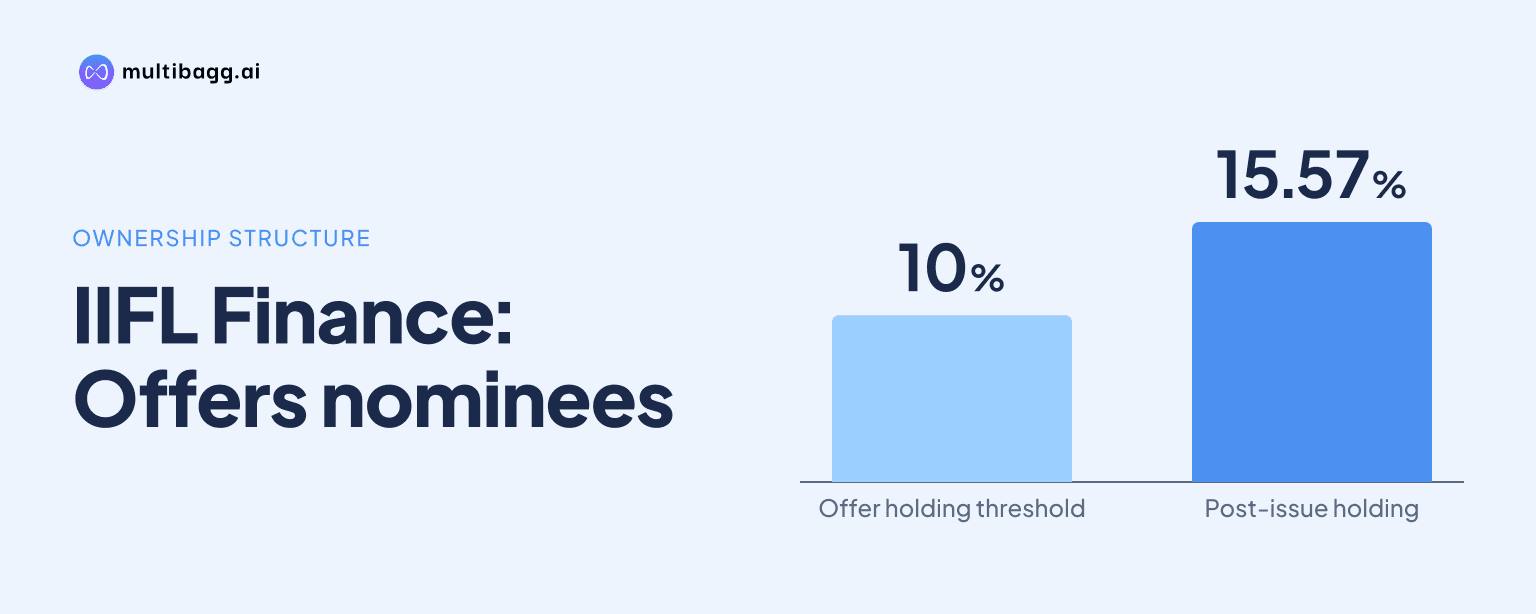
IIFL Finance Limited proposes to let Ingot SG nominate two retiring non-executive directors when it and its affiliates hold 5,35,68,952 equity shares or compulsorily convertible preference shares, or CCPS, described as about 10%, subject to completion and shareholder approval of restated articles. Ingot SG’s post-issue holding is shown at 15.57% on a fully diluted basis.
Know IIFL Finance inside out
Results, valuation, peers and who's buying, in one view.
What board nomination rights would Ingot SG receive?
Ingot SG would be entitled to nominate two retiring non-executive directors to the IIFL Finance board while it and its affiliates hold 5,35,68,952 equity shares or CCPS, described as about 10%. The threshold is subject to adjustments for certain corporate actions under Subscription Agreement 1, and the rights would take effect from the agreement’s completion date.
At the lower threshold of 4,01,76,714 equity shares or CCPS, described as about 7.5%, Ingot SG could nominate one retiring non-executive director to the IIFL Finance board. This entitlement cannot duplicate the two-director right at the higher threshold, and the disclosure does not name any proposed board nominees.
The 7.5% threshold would also allow Ingot SG to nominate one retiring non-executive director to IIFL Home Finance Limited and two retiring non-executive directors to IIFL Samasta Finance Limited. These subsidiary nominations are linked to the same continuing ownership condition and are set out in Subscription Agreement 1.
How are Ingot SG's veto and issuance rights structured?
Ingot SG would receive reserved-matters rights requiring its affirmative vote or affirmative written consent while it and its affiliates remain above thresholds set in Subscription Agreement 1. IIFL Finance does not disclose the applicable thresholds or the individual matters requiring consent, so the exact scope of this protection cannot be measured from the filing.
Ingot SG would also have a pre-emptive right to subscribe to future IIFL Finance issuances while its group holding stays above separately specified thresholds. The mechanism gives Ingot SG an opportunity to participate in future issuances under the agreement’s terms, but the announcement does not disclose an allocation formula, exemptions or the threshold levels.
Both the reserved-matter and pre-emptive rights are proposed for inclusion in IIFL Finance’s restated articles, subject to shareholder approval by special resolution under Regulation 31B of the Listing Regulations. The company describes these rights as customary protective rights typically granted to minority shareholders.
What stake would Ingot SG hold after the preferential issue?
Ingot SG would receive 8,30,56,478 Subscription Shares, issued at par as CCPS, under the preferential issue at a subscription price of Rs 602 per Subscription Security. IIFL Finance’s shareholding table shows Ingot SG with no holding before the issue and 15.57% afterward on the stated fully diluted basis.
That 15.57% calculation assumes conversion of all Subscription Securities into equity shares and exercise of all proposed warrants, but excludes the conversion of employee stock options granted or vested at the disclosure date. The proposed Ingot SG allotment exceeds both the approximately 10% and 7.5% ownership thresholds that activate its board nomination rights, based on the disclosed post-issue percentage.
Anchorage Capital Scheme II would receive 9,96,678 CCPS and Anchorage Capital Scheme III would receive 14,95,017 CCPS. Their indicated post-issue holdings are 0.19% and 0.28%, respectively, and IIFL Finance states that neither Anchorage investor would receive special rights.
Got a follow-up? Ask IRIS
How do the promoter warrants compare with investor subscriptions?
The three promoter-group allottees would receive warrants exercisable within 18 months of allotment, whereas the CCPS issued to Ingot SG and the Anchorage investors must convert earlier of an agreed date or 17 months and 15 days after allotment. Shares issued on CCPS conversion or warrant exercise would rank pari passu with existing equity shares from their respective allotment dates.
Mr. Nirmal Bhanwarlal Jain would receive 1,50,00,000 warrants with aggregate consideration of Rs 903 crore, Mr. Venkataraman Rajamani would receive 45,00,000 warrants for Rs 270.90 crore, and Ardent Impex Private Limited would receive 15,00,000 warrants for Rs 90.30 crore. Under the Securities and Exchange Board of India, or SEBI, Issue of Capital and Disclosure Requirements regulations, 25% of the warrant subscription amount is payable upfront and 75% is payable on exercise.
The comparison in the filing shows each of the three named promoter-group holders with a higher fully diluted percentage after the proposed issue and warrant exercise. Ingot SG, however, would become the largest disclosed new investor at 15.57%, compared with 0.19% for Anchorage Capital Scheme II and 0.28% for Anchorage Capital Scheme III.
Will the arrangements change control of IIFL Finance?
No change in control is contemplated by the proposed transactions, according to IIFL Finance. Ingot SG and the two Anchorage funds would be classified as public shareholders after completion, while Mr. Nirmal Bhanwarlal Jain, Mr. Venkataraman Rajamani and Ardent Impex Private Limited would remain part of the promoter or promoter group.
Completion of Subscription Agreement 1 requires shareholder approval, applicable regulatory and statutory approvals, Competition Commission of India approval, and in-principle approvals from BSE Limited and National Stock Exchange of India Limited. The proposed issue under Subscription Agreements 2 and 3 also requires shareholder, regulatory or statutory, and stock-exchange in-principle approvals.
IIFL Finance has scheduled an extra-ordinary general meeting for December 4, 2026, at which shareholders will consider the preferential issue through a special resolution. A separate special resolution is required to incorporate Ingot SG’s special rights into the restated articles under Regulation 31B.
Conclusion
The proposed preferential issue would give Ingot SG governance protections tied to its continuing ownership while retaining its public-shareholder classification and without a stated transfer of control. A holding of about 10% supports two IIFL Finance board nominees, while about 7.5% supports one IIFL Finance nominee and three subsidiary-board nominees, alongside reserved-matter consent and pre-emptive participation rights at undisclosed thresholds.
The immediate disclosed event to watch is the December 4, 2026 extra-ordinary general meeting and its special resolutions on the preferential issue and restated articles. Completion also depends on the Competition Commission of India, BSE and National Stock Exchange approvals, while the detailed operation of the reserved-matter and pre-emptive rights remains undisclosed in the announcement.