










IIFL Finance plans Rs 5,000 crore Ingot SG investment
Key highlights
- IIFL Finance proposes about Rs 5,000 crore of CCPS for Ingot SG at Rs 602 per security.
- Ingot SG would hold 15.57% of IIFL Finance on a fully diluted post-issue basis.
- The two Anchorage schemes would receive about Rs 150 crore of CCPS for a combined 0.47% holding.
- IIFL Finance has scheduled shareholder voting on the proposal for December 4, 2026.
powered by IRIS
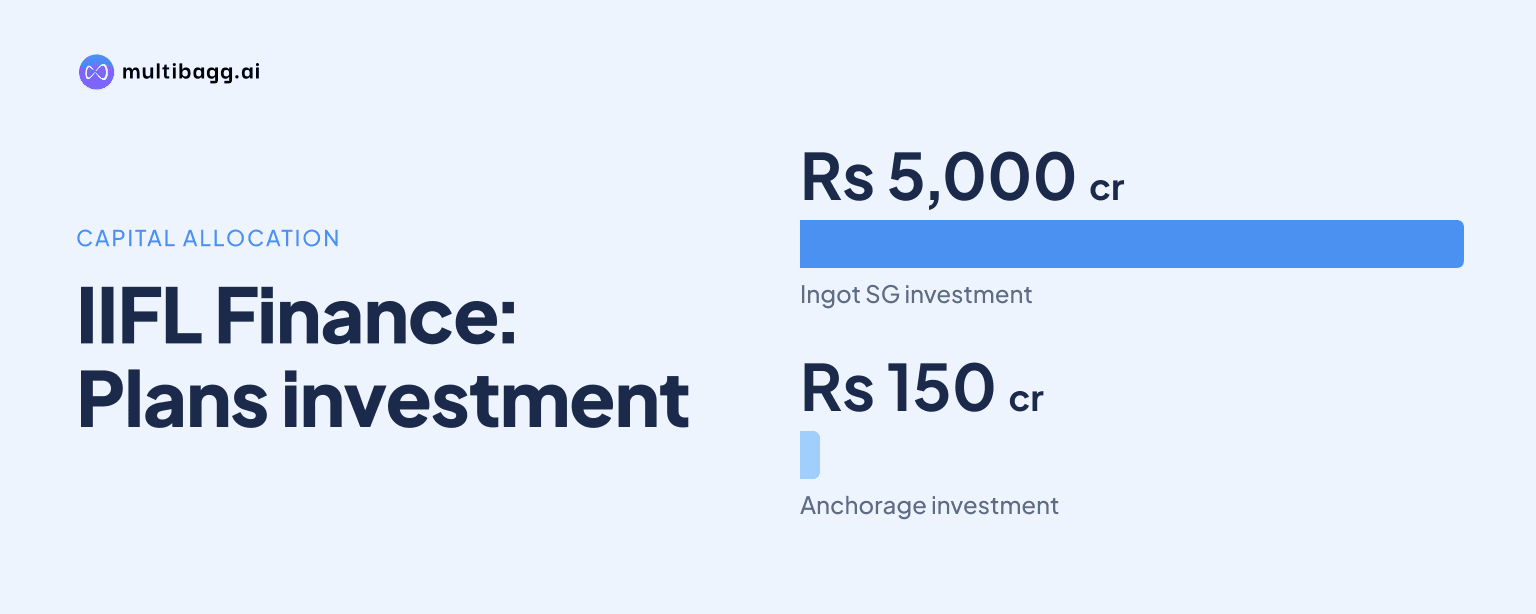
IIFL Finance Limited proposes to raise about Rs 5,000 crore from Ingot SG Pte. Ltd. through compulsorily convertible preference shares, giving the Blackstone-affiliate investment vehicle a 15.57% fully diluted holding after conversion. The preferential issue, agreed on November 10, 2026, remains subject to shareholder, regulatory and stock-exchange approvals.
Know IIFL Finance inside out
Results, valuation, peers and who's buying, in one view.
What is IIFL Finance issuing to Ingot SG?
IIFL Finance proposes to issue 8,30,56,478 compulsorily convertible preference shares, or CCPS, to Ingot SG for about Rs 5,000 crore at Rs 602 per security. Each CCPS has a face value of Rs 602 and will convert into one equity share, subject to adjustments for capital restructuring under Subscription Agreement 1 dated November 10, 2026.
Ingot SG is a Singapore-incorporated investment vehicle that is part of funds managed or advised by affiliates of Blackstone Inc. It held no IIFL Finance equity shares before the proposal, while its stated post-issue position is 8,30,56,478 equity shares, or 15.57%, on a fully diluted basis.
IIFL Finance said the Rs 602 subscription price was not below the floor price determined by an independent registered valuer. The company cited Regulation 164(1) and Regulation 166A of Chapter V of the Securities and Exchange Board of India, or SEBI, Issue of Capital and Disclosure Requirements regulations for the pricing process.
How does Ingot SG's allocation compare with other investors?
Ingot SG's proposed 15.57% fully diluted holding is larger than the combined 0.47% proposed for the two Anchorage Capital schemes. Anchorage Capital Scheme II would receive 9,96,678 CCPS for about Rs 60 crore and a 0.19% post-issue holding, while Anchorage Capital Scheme III would receive 14,95,017 CCPS for about Rs 90 crore and a 0.28% holding.
The difference is also clear in the prospective share count: Ingot SG would receive 8,30,56,478 shares on conversion, compared with 24,91,695 shares combined for the two Anchorage schemes. Neither Anchorage scheme held IIFL Finance shares before the proposed issue, and both are described as Category II alternative investment funds registered with SEBI.
The preferential issue also includes 2,10,00,000 promoter warrants at Rs 602 each. Mr. Nirmal Bhanwarlal Jain is proposed to receive 1,50,00,000 warrants for Rs 903 crore, Mr. Venkataraman Rajamani 45,00,000 warrants for Rs 270.90 crore, and Ardent Impex Private Limited 15,00,000 warrants for Rs 90.30 crore.
How would the issue affect IIFL Finance promoter shareholdings?
IIFL Finance's filing shows Mr. Nirmal Bhanwarlal Jain's shares increasing by 1,50,00,000 to 6,84,40,570 after the proposed warrant exercise. His disclosed holding is 12.52% before the issue and 12.83% after it, although the pre-issue and post-issue percentages use the filing's respective stated bases.
Mr. Venkataraman Rajamani's proposed shares would rise from 1,23,01,441 to 1,68,01,441, with the filing showing his percentage at 2.88% before and 3.15% after the issue. Ardent Impex's shares would increase from 36,32,115 to 51,32,115, while its stated percentage would move from 0.85% to 0.96%.
The post-issue percentages assume allotment and conversion of all subscription securities, exercise of all relevant warrants, and conversion of employee stock options granted or vested at the disclosure date. The filing therefore presents potential ownership after the new CCPS and warrants rather than only the current paid-up equity capital.
Got a follow-up? Ask IRIS
When will IIFL Finance securities convert into equity?
IIFL Finance's CCPS issued to Ingot SG and the Anchorage investors must convert into equity at the earlier of a mutually agreed date or 17 months and 15 days after allotment. Each CCPS converts into one fully paid equity share, and the shares issued on conversion will rank equally with existing equity shares from their allotment date.
The promoter warrants have an 18-month exercise window from allotment and may be exercised in one or more tranches. The promoters must pay 25% of their relevant subscription amount when the warrants are allotted and the remaining 75% when they exercise them.
If a promoter does not exercise warrants during the 18-month period, the warrants will lapse and the upfront amount will be forfeited under the SEBI regulations, according to the filing. In contrast, Ingot SG and the two Anchorage investors must pay 100% of their CCPS consideration at subscription and allotment.
What governance rights could Ingot SG receive in IIFL Finance?
Ingot SG could receive board nomination, reserved-matters and pre-emptive rights after completion, subject to shareholder approval of amended and restated articles of association. The proposed rights arise under Subscription Agreement 1 and would take effect from completion, rather than merely from the November 10, 2026 agreement date.
If Ingot SG and its affiliates hold at least 5,35,68,952 equity shares or CCPS, described as about 10%, they could nominate two retiring non-executive directors to the IIFL Finance board. At 4,01,76,714 shares or CCPS, described as about 7.5%, they could nominate one retiring non-executive director to IIFL Finance, one to IIFL Home Finance Limited and two to IIFL Samasta Finance Limited.
The proposal also provides for affirmative-vote or written-consent rights on specified reserved matters while Ingot SG's holding stays above thresholds set in Subscription Agreement 1. Ingot SG would also have a pre-emptive right to subscribe to further IIFL Finance issuances while it and its affiliates meet the applicable holding thresholds.
What approvals does IIFL Finance need before completion?
IIFL Finance needs shareholder approval, applicable statutory and regulatory approvals, and in-principle approvals from BSE Limited and National Stock Exchange of India Limited before the issue can complete. Subscription Agreement 1 specifically includes approval from the Competition Commission of India among the required conditions precedent.
The company has called an extraordinary general meeting, or EGM, for December 4, 2026 at 11:00 a.m. Indian Standard Time through video conference or other audio-visual means. Shareholders will consider the preferential issue, the authorised-capital change, amendments to the articles, Ingot SG's proposed special rights and Mr. Rajamani's redesignation as a non-executive non-independent director.
IIFL Finance proposes to increase authorised share capital from Rs 971.05 crore to Rs 5,621.05 crore. The amended structure would retain 235,52,50,000 equity shares with a Rs 2 face value and provide for 8,55,48,173 preference shares with a Rs 602 face value.
Conclusion
The proposed transaction would introduce Ingot SG as a 15.57% fully diluted shareholder through about Rs 5,000 crore of CCPS, alongside about Rs 150 crore of CCPS for the two Anchorage schemes. The promoter warrant component totals Rs 1,264.20 crore, but it has different cash timing because only 25% is payable upfront and exercise remains optional within 18 months.
The next disclosed event is the December 4, 2026 EGM, where shareholders will vote on the securities issue, capital increase, amended articles and proposed investor rights. Completion also depends on Competition Commission of India, stock-exchange and other applicable approvals; an allotment date would then begin the 17-month-and-15-day mandatory conversion timetable for the CCPS.