










IndiGo discloses Rs 2,418.5 crore incentives tax exposure
Key highlights
- IndiGo disclosed Rs 2,418.5 crore of potential tax exposure through AY 2022-23 if aircraft and engine incentives are held taxable, excluding interest and penalties.
- The company disclosed a separate Rs 1,822.7 crore tax effect on carried-forward losses and has recorded no provision for the dispute.
- Tax authority appeals against favourable ITAT rulings remain pending before the High Court of Delhi as at 30 September 2026.
- IndiGo reported a standalone loss before tax of Rs 2,437.1 crore for the half year ended 30 September 2026, compared with Rs 218.4 crore a year earlier.
powered by IRIS
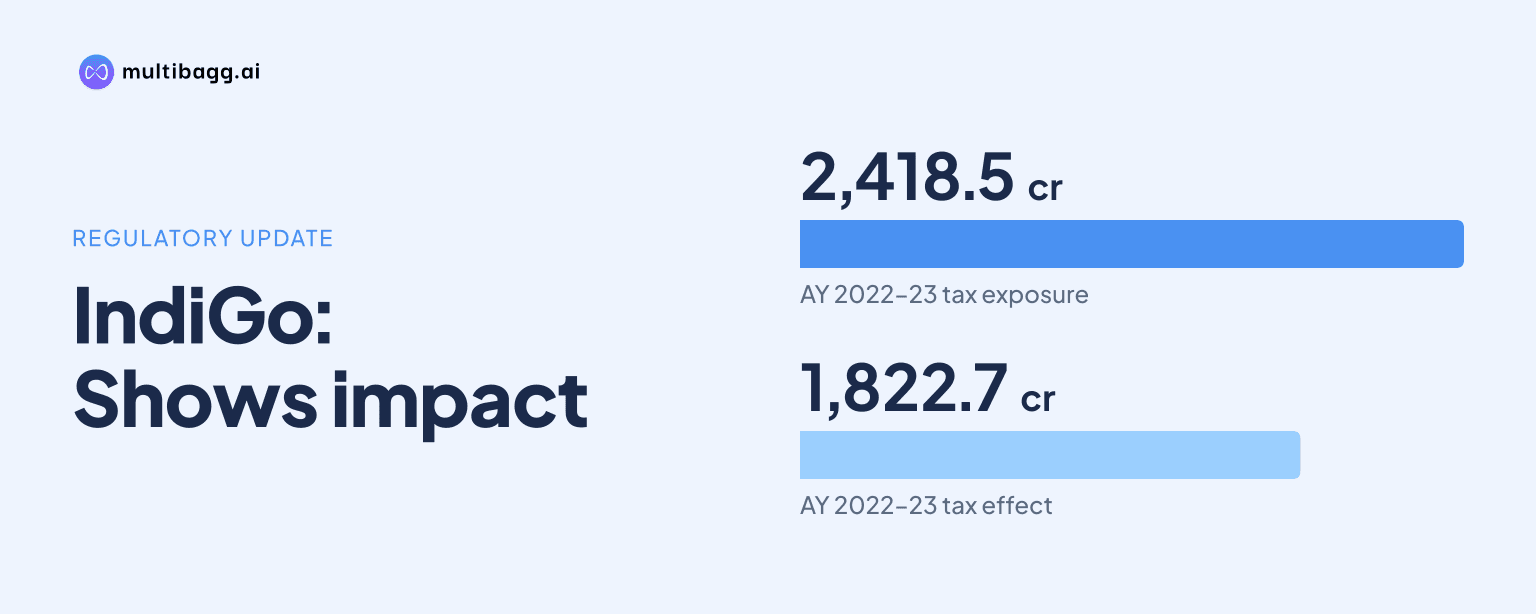
InterGlobe Aviation Limited (IndiGo) disclosed Rs 2,418.5 crore of tax exposure through assessment year (AY) 2022-23 if aircraft and engine manufacturer incentives are held taxable. The amount excludes interest and penalties and is accompanied by a separate Rs 1,822.7 crore potential tax effect on carried-forward losses. IndiGo has recorded no provision.
Know Interglobe Aviation inside out
Results, valuation, peers and who's buying, in one view.
What is IndiGo's incentives tax dispute about?
IndiGo's dispute concerns the income-tax treatment of incentives received from manufacturers on the acquisition of aircraft and engines, as well as certain expense disallowances made by tax authorities. The tax authority has assessed IndiGo's income-tax returns up to AY 2022-23, while assessment orders for subsequent years have not yet been received.
The filing does not separately quantify the expense disallowances and the incentives issue. Instead, it gives a combined tax exposure of Rs 2,418.5 crore for matters disallowed through AY 2022-23, the last year assessed, if the incentives are ultimately held taxable. That amount specifically excludes interest and penalty.
IndiGo has received favourable rulings from the Income Tax Appellate Tribunal (ITAT) on these matters. The ITAT Special Bench gave a favourable order for AY 2012-13, while the ITAT Divisional Bench gave favourable orders for certain years through AY 2015-16. The income-tax authority has appealed those decisions to the High Court of Delhi.
The litigation has therefore not reached a final outcome as at 30 September 2026. IndiGo says the High Court of Delhi appeals remain pending, and the filing does not give a date for a judgment. It also does not quantify whether similar treatment in years after AY 2022-23 could create further exposure once those assessments are completed.
How much tax exposure has IndiGo disclosed?
IndiGo has disclosed Rs 2,418.5 crore of direct tax exposure and a separate Rs 1,822.7 crore tax effect on carried-forward losses. The direct exposure is net of Rs 533.2 crore of minimum alternate tax (MAT) recoverable that had been written off in earlier years.
The Rs 1,822.7 crore loss-related figure is not described as an additional current tax demand. IndiGo says the stated exposure would also affect carried-forward losses with that tax effect. The disclosure therefore distinguishes between the direct exposure and the potential effect on tax losses rather than presenting them as one stated liability.
The assessment cut-off is significant because Rs 2,418.5 crore covers only matters assessed through AY 2022-23. IndiGo has not received assessment orders for later years, according to the 30 September 2026 filing. The document consequently does not state a comparable tax exposure for those unassessed years.
Why has IndiGo recorded no provision for the dispute?
IndiGo has recorded no provision because it believes the favourable ITAT views are sustainable in higher courts, based on legal advice from counsels. That judgement relies on the Special Bench order for AY 2012-13 and Divisional Bench orders for certain years through AY 2015-16.
No provision does not resolve the matter, because the income-tax authority's appeals remain before the High Court of Delhi as at 30 September 2026. The disclosed Rs 2,418.5 crore amount is conditional on the incentives being held taxable, and it does not include interest or penalties that could arise in an adverse result.
The unaudited consolidated results for the quarter and half year ended 30 September 2026 were reviewed by IndiGo's Audit Committee and approved by its Board of Directors on 29 October 2026. The statutory auditors issued an unmodified conclusion following their limited review of the consolidated results, which include subsidiaries and a controlled trust.
The filing distinguishes between the company assessments and the group litigation position. The income-tax authority assessed the Company's returns through AY 2022-23, while the Group received the favourable ITAT orders and concluded that no provision was required in its books. IndiGo does not disclose a separate standalone provision figure for the incentive matter.
Got a follow-up? Ask IRIS
What do IndiGo's latest financial results show alongside this exposure?
IndiGo's standalone loss before tax widened to Rs 2,437.1 crore in the half year ended 30 September 2026 from Rs 218.4 crore in the half year ended 30 September 2025. The Rs 2,418.5 crore direct tax exposure is close in scale to that latest six-month pre-tax loss, although the two figures measure different matters.
The standalone statement reported a current-tax credit of Rs 40 lakh for the half year ended 30 September 2026, compared with current-tax expense of Rs 234.6 crore a year earlier. These income-statement figures do not establish the eventual result of the incentives litigation, which remains subject to the pending appeals.
On the consolidated balance sheet, IndiGo reported net income-tax assets of Rs 2,115 crore at 30 September 2026, compared with Rs 1,977.5 crore at 31 March 2026. Current tax liabilities were nil at 30 September 2026, versus Rs 43 lakh at 31 March 2026. The filing does not directly connect either balance-sheet line to the incentives dispute.
Is IndiGo's IGST claim part of the income-tax exposure?
IndiGo's Integrated Goods and Services Tax (IGST) matter is separate from the Rs 2,418.5 crore income-tax exposure. It concerns IGST paid under protest on the re-import of repaired aircraft, aircraft engines and certain aircraft parts, with cumulative payments of Rs 2,400 crore at 30 September 2026.
IndiGo paid Rs 106.8 crore under protest during the quarter ended 30 September 2026. It has filed, or plans to file, appeals before appellate authorities and records the cumulative payments as recoverable, based on favourable court orders and legal advice.
For imports before 19 July 2021, IndiGo received three favourable orders from the Customs, Excise and Service Tax Appellate Tribunal. The Supreme Court dismissed one departmental appeal on 14 July 2025 and rejected the related review petition on 17 February 2026. Two departmental appeals remain pending, and no stay had been granted on the tribunal orders as at 30 September 2026.
A separate Delhi High Court ruling in March 2025 found the levy of IGST on re-imported items repaired abroad unconstitutional and invalid. The department appealed to the Supreme Court on 29 August 2025, where the case remained pending without a stay as at 30 September 2026. This litigation concerns customs treatment on repaired imports, not the income-tax treatment of manufacturer incentives.
Conclusion
IndiGo has placed a quantified figure on the incentive-related tax matter assessed through AY 2022-23: Rs 2,418.5 crore of direct exposure if incentives are treated as taxable, net of Rs 533.2 crore of previously written-off MAT recoverable. A further Rs 1,822.7 crore tax effect relates to carried-forward losses, while no accounting provision has been recorded.
The next development to watch is the High Court of Delhi's decision on the tax authority's appeals involving AY 2012-13 and certain years through AY 2015-16. Assessment orders for years after AY 2022-23 have not yet been received, leaving the treatment and potential exposure for subsequent periods unresolved in the 30 September 2026 filing.