










Indo Count Q2 profit triples as EBITDA margin reaches 15.3%
Key highlights
- Indo Count reported Q2 FY27 profit after tax of Rs 132 crore, up 238% year on year.
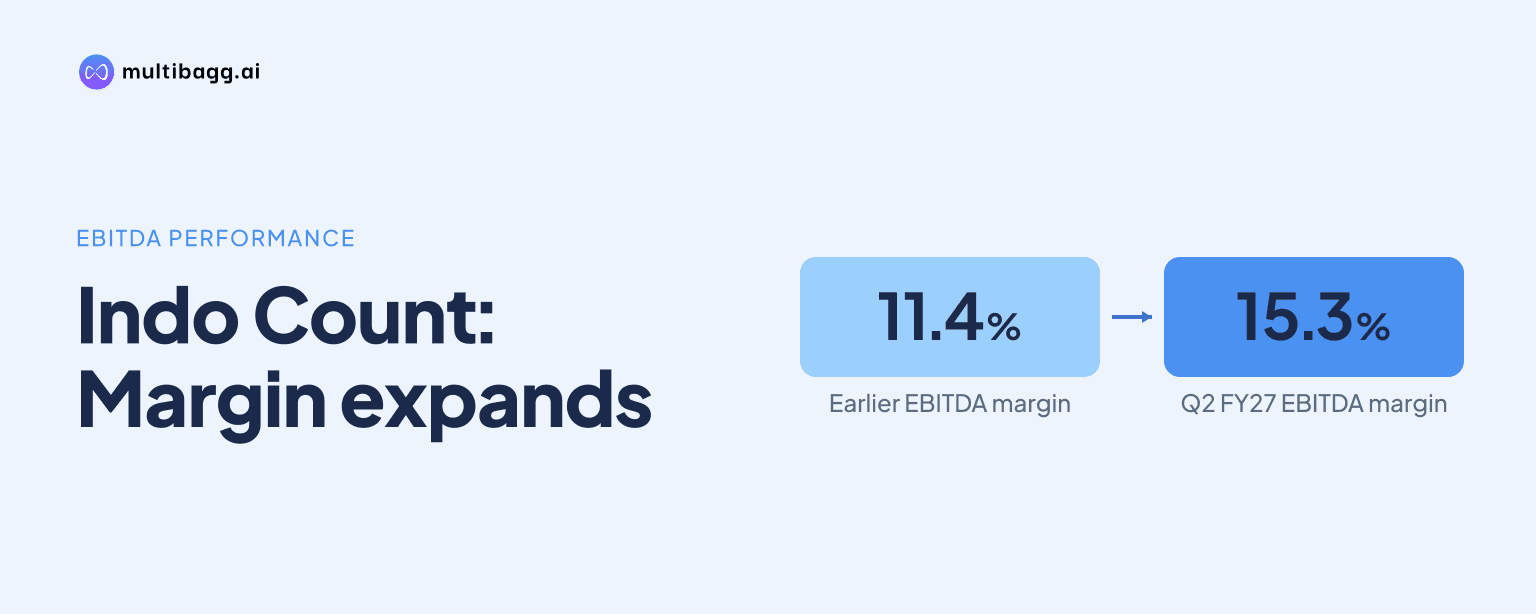
- Q2 FY27 EBITDA rose 111% to Rs 259 crore and margin expanded to 15.3% from 11.4%.
- H1 FY27 new-business revenue was Rs 890 crore, representing 30% of total revenue.
- Net cash from operating activities was Rs 382 crore in Sep’26, versus Rs 361 crore in Sep’25.
powered by IRIS
Indo Count Industries Limited reported Q2 FY27 profit after tax of Rs 132 crore, up 238% year on year, as earnings before interest, tax, depreciation and amortisation margin rose 380 basis points to 15.3% and total income reached Rs 1,699 crore.
Know Indo Count Industries inside out
Results, valuation, peers and who's buying, in one view.
How did Indo Count’s Q2 FY27 profit change?
Indo Count’s Q2 FY27 profit after tax was Rs 132 crore, compared with Rs 39 crore in Q2 FY26 and Rs 63 crore in Q1 FY27. The year-on-year increase was 238%, while the quarter-on-quarter increase was 109%; earnings per share rose to Rs 6.66 from Rs 1.97 a year earlier.
The profit increase exceeded income growth because operating earnings rose faster. Earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 111% year on year to Rs 259 crore, while depreciation increased to Rs 46 crore from Rs 39 crore and finance cost increased to Rs 37 crore from Rs 32 crore. Profit before tax rose 239% to Rs 176 crore from Rs 52 crore.
What drove Indo Count’s revenue and margin expansion?
Indo Count attributed Q2 FY27 income growth to market-share gains, higher wallet share from customers and product mix, alongside accelerating traction in branded products. Total income increased by Rs 617 crore from Q2 FY26 and by Rs 475 crore from Q1 FY27, representing year-on-year growth of 57% and sequential growth of 39%.
Management said improved asset utilisation across domestic and international operations and operational efficiencies supported EBITDA growth. The 15.3% Q2 FY27 margin was 380 basis points above Q2 FY26’s 11.4% and 200 basis points above Q1 FY27’s 13.1%. Volume reached 28.1 million metres, compared with 25.2 million metres a year earlier and 23.0 million metres in the preceding quarter.
The revenue mix also changed between the two Q2 periods. Core bed-linen business generated Rs 1,197 crore in Q2 FY27, up from Rs 901 crore in Q2 FY26, while new businesses generated Rs 502 crore, compared with Rs 181 crore. New businesses comprise utility bedding and the USA brand business, and contributed nearly 30% of H1 FY27 revenue.
How did Indo Count perform in H1 FY27?
Indo Count recorded H1 FY27 total income of Rs 2,923 crore, up 43% from Rs 2,049 crore in H1 FY26, while profit after tax rose 150% to Rs 195 crore from Rs 78 crore. H1 EBITDA increased 73% to Rs 420 crore, and its margin expanded 250 basis points to 14.4% from 11.8%.
New businesses accounted for 30% of H1 FY27 revenue, double their 15% contribution in H1 FY26, while core business’s contribution declined to 70% from 85%. In absolute terms, H1 core-business revenue was Rs 2,033 crore and new-business revenue was Rs 890 crore. The presentation said capacity utilisation exceeded 65% across all three utility-bedding facilities.
The longer-term segment data also show faster expansion in new businesses. New-business revenue was Rs 792 crore in FY26 and reached Rs 890 crore in H1 FY27, while core-business revenue was Rs 3,419 crore in FY26 and Rs 2,033 crore in H1 FY27. Indo Count reported a 128% compound annual growth rate for new businesses, compared with 5% for core business.
Got a follow-up? Ask IRIS
What do Indo Count’s cash flow and debt figures show?
Indo Count generated net cash from operating activities of Rs 382 crore in Sep’26, compared with Rs 361 crore in Sep’25. Cash generated from operations was Rs 390 crore after an Rs 11 crore working-capital change, compared with Rs 364 crore in the prior-year period.
Cash and cash equivalents ended Sep’26 at Rs 316 crore, compared with Rs 114 crore at the beginning of the financial year and Rs 62 crore at Sep’25. Investing activities used Rs 44 crore, versus Rs 97 crore a year earlier, while financing activities used Rs 135 crore, compared with Rs 308 crore in Sep’25.
Net debt was Rs 518 crore at Sep’26, with net debt to equity of 0.2 times, according to the presentation. Total equity increased to Rs 2,549 crore from Rs 2,355 crore at Mar’26. Annualised return on equity was 15.3% and annualised return on capital employed was 21.4% at the September reporting date.
What is Indo Count targeting for FY27 and beyond?
Indo Count’s FY27 guidance calls for volume of 105 million to 110 million metres and total income of about Rs 5,500 crore, compared with 94.1 million metres and Rs 4,211 crore in FY26. H1 FY27 volume was 51 million metres, or 49% of the guidance range, while H1 income of Rs 2,923 crore represented 52% of the income guidance.
Management’s FY27 EBITDA-margin guidance was 14.4%, compared with 11.0% in FY26; Indo Count reported that same 14.4% margin in H1 FY27. Executive Chairman Anil Kumar Jain said Indo Count expected to outperform its guidance because of business momentum in the second half of FY27, which is a management expectation rather than a reported outcome.
Indo Count plans FY27 capital expenditure of Rs 250 crore, funded through a mix of internal accruals and debt and targeted for completion within 12 to 18 months. The programme includes Rs 95 crore for an effluent treatment plant at Bhilad, Rs 85 crore for a 24,000-spindle brownfield spinning expansion and modernisation, and Rs 70 crore for maintenance and other capital expenditure. Indo Count also aspires to double revenue by 2028 over its FY25 base.
Conclusion
Indo Count’s Q2 FY27 performance combined 57% total-income growth with a 380-basis-point EBITDA-margin increase, resulting in profit after tax of Rs 132 crore. The H1 trend was similar, with EBITDA growing 73% against 43% income growth and new businesses contributing 30% of revenue, compared with 15% a year earlier.
The next disclosures to watch are progress against FY27 guidance of about Rs 5,500 crore in total income and 105 million to 110 million metres of volume, after H1 achievement of 52% and 49%, respectively. Delivery of the Rs 250 crore capital-expenditure programme within 12 to 18 months and management’s expectation to exceed FY27 income and margin guidance remain key unresolved measures.