










Indsil cash balance rises as operating flow turns negative
Key highlights
- Indsil reported a Rs 4.21 crore operating cash outflow for the half year ended 30 September 2026, versus a Rs 5.16 crore inflow a year earlier.
- Indsil's cash and cash equivalents rose to Rs 5.79 crore at 30 September 2026 from Rs 3.42 crore at 31 March 2026.
- Indsil reported Rs 5.66 crore of net financing cash inflow, including a Rs 5.22 crore increase in short-term loans and advances.
- Indsil's profit before tax fell to Rs 3.23 crore from Rs 9.97 crore, while power cost rose to Rs 15.14 crore from Rs 10.52 crore.
powered by IRIS
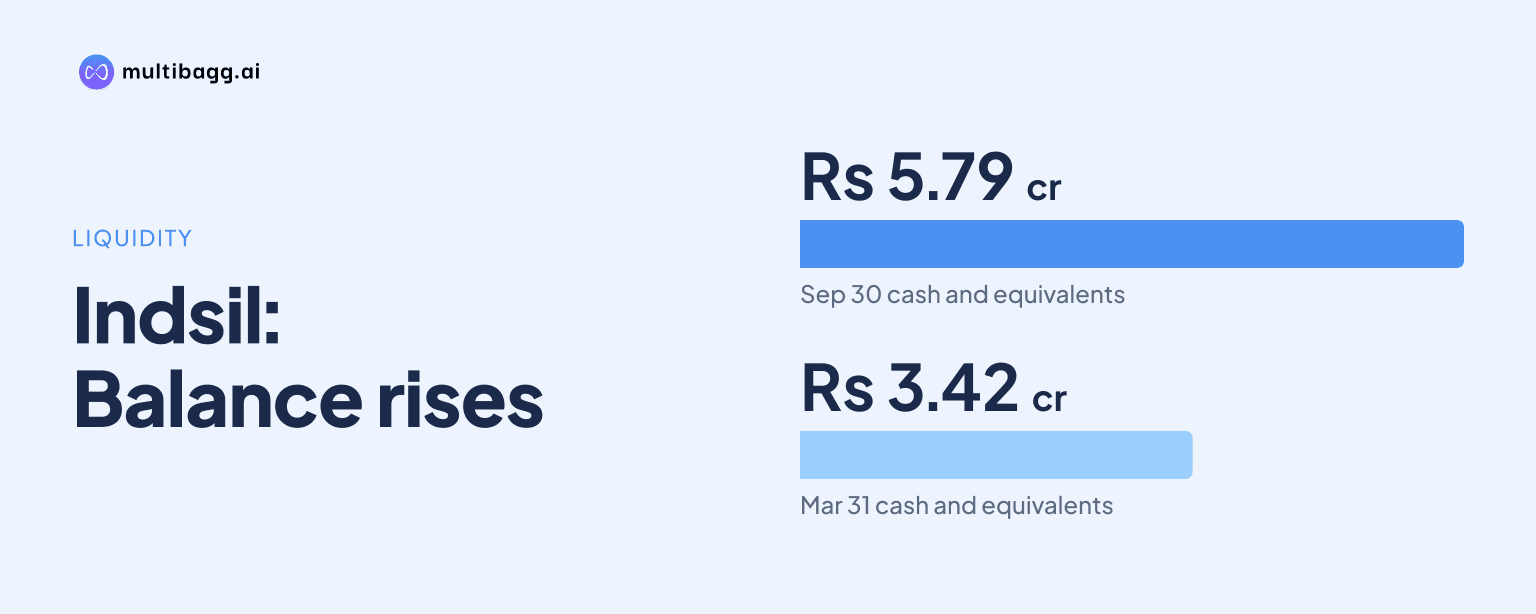
Indsil Hydro Power and Manganese Limited reported a Rs 4.21 crore net operating cash outflow for the half year ended 30 September 2026, compared with a Rs 5.16 crore inflow a year earlier, while cash and cash equivalents rose to Rs 5.79 crore from Rs 3.42 crore at 31 March 2026.
Know Indsil Hydro Power & Manganese inside out
Results, valuation, peers and who's buying, in one view.
Why did Indsil's operating cash flow turn negative?
Indsil's operating cash flow turned negative after lower operating profit before working-capital changes, working-capital movements and cash taxes. Net cash used in operating activities was Rs 4.21 crore in the half year ended 30 September 2026, reversing from net cash generated of Rs 5.16 crore in the corresponding 2025 half year.
Operating profit before working-capital changes fell to Rs 1.96 crore from Rs 14.56 crore a year earlier. After the disclosed working-capital adjustments, cash generated from operations was negative Rs 91.44 lakh, against positive Rs 5.65 crore in the prior-year half, and direct taxes paid were Rs 2.26 crore compared with Rs 49.17 lakh.
The cash-flow statement records a Rs 3.04 crore movement in a current-asset line, Rs 1.52 crore in another adjustment, a negative Rs 3.94 crore movement in a current-liability line and negative Rs 4.51 crore in other current liabilities. As these lines are not fully labelled in the supplied statement, the filing shows their cash effects but does not provide a detailed commercial explanation for each movement.
How did Indsil's cash balance increase despite the outflow?
Indsil's cash and cash equivalents increased by Rs 2.37 crore during the half year because financing inflows exceeded the operating outflow and investing outflow. Closing cash and cash equivalents were Rs 5.79 crore at 30 September 2026, compared with an opening balance of Rs 3.42 crore at 1 April 2026.
Net cash from financing activities was Rs 5.66 crore, while net cash used in investing activities was only Rs 7.84 lakh. The financing inflow was lower than Rs 11.41 crore reported in the corresponding 2025 half year, but it was sufficient to offset the Rs 4.21 crore operating outflow in the current period.
The financing section includes a Rs 5.22 crore increase in short-term loans and advances, Rs 2.01 crore of increase or decrease in deferred tax, and a Rs 46.88 lakh decrease in long-term loans and advances. It also records Rs 67,000 of financial charges and interest and a Rs 15.39 lakh decrease in other bank balances that are not cash equivalents.
The filing identifies cash in hand and bank balances, short-term investments in debt-based liquid funds, and short-term borrowings in its cash-equivalent note. It reports the same Rs 5.79 crore closing cash-and-cash-equivalents balance in that note, against Rs 3.42 crore at 31 March 2026.
How did Indsil's earnings compare with the previous half year?
Indsil's lower earnings coincided with the decline in operating cash generation. Revenue from operations was Rs 76.53 crore in the half year ended 30 September 2026, down from Rs 77.43 crore a year earlier, while profit before tax declined to Rs 3.23 crore from Rs 9.97 crore.
Total income decreased to Rs 78.08 crore from Rs 78.62 crore, but total expenses increased to Rs 74.85 crore from Rs 68.65 crore. The gap between the movement in income and expenses reduced profit before tax by Rs 6.74 crore year on year.
Power cost increased to Rs 15.14 crore from Rs 10.52 crore, while cost of materials consumed rose to Rs 45.98 crore from Rs 45.41 crore. Purchase of stock-in-trade was Rs 91.93 lakh in the current half year, compared with negative Rs 16.69 lakh in the prior-year half, based on the amounts reported in the results statement.
Profit for the period was Rs 95.95 lakh, compared with Rs 10.03 crore in the corresponding 2025 half year. The difference between this accounting result and negative operating cash flow reflects the reported non-cash adjustments, working-capital movements and Rs 2.26 crore of direct taxes paid.
Got a follow-up? Ask IRIS
Can the cash outflow be assigned to Indsil's business segments?
Indsil's filing does not provide a cash-flow split between its Ferre-Alloys and Power segments, so the Rs 4.21 crore operating outflow cannot be attributed to either segment from the supplied disclosure. The company states that it has organised its business into Ferre-Alloys and Power segments under Indian Accounting Standards, or Ind AS, segment-reporting principles.
The standalone results disclose total revenue from operations of Rs 76.53 crore for the half year ended 30 September 2026, but the supplied segment table is not sufficiently complete to establish segment cash generation. The cash-flow statement is therefore the relevant disclosure for the half-year operating outflow rather than a segment-level measure.
Indsil reported property, plant and equipment of Rs 48.84 crore at 30 September 2026, compared with Rs 48.99 crore at 31 March 2026. Capital work in progress was unchanged at Rs 55.19 lakh, while the investing section reported Rs 1.48 crore for purchase of fixed assets.
The investing cash outflow narrowed to Rs 7.84 lakh from Rs 15.87 crore in the prior-year half. The statement also lists Rs 1.39 crore relating to investments made during the year, Rs 1.24 crore for a long-term investment line, Rs 79.10 lakh in another investing line and Rs 45.26 lakh for profit or loss on sale of assets or investments.
What does Indsil's filing say about review and reporting?
Indsil's standalone financial results for the quarter and half year ended 30 September 2026 were unaudited and approved by its board on 4 November 2026. The company said the results were reviewed by its statutory auditors and recommended by the audit committee before board approval.
The auditor performed a review under Standard on Review Engagements 2410, rather than an audit, and stated that nothing had come to its attention indicating that the financial statement contained a material misstatement. The review report is dated 4 November 2026 and covers the quarterly unaudited standalone financial results.
Indsil said the statement was prepared under Ind AS prescribed under Section 133 of the Companies Act, 2013. It also said previous-period figures were regrouped or rearranged where necessary to make them comparable with the current period.
The filing reports paid-up equity share capital of Rs 27.79 crore. It does not disclose a cash-flow target, refinancing plan or scheduled capital-expenditure programme, leaving the next reported working-capital and financing movements as the primary disclosures for assessing whether the September-half pattern changes.
Conclusion
Indsil's higher closing cash balance did not result from operating cash generation in the half year ended 30 September 2026. Operating cash flow shifted from a Rs 5.16 crore inflow to a Rs 4.21 crore outflow, while Rs 5.66 crore of financing inflow and a limited Rs 7.84 lakh investing outflow supported the Rs 5.79 crore closing cash balance.
The next results will show whether operating profit before working-capital changes recovers from Rs 1.96 crore and whether the current-asset, liability and tax movements that contributed to the outflow reverse. The filing also identifies the Rs 5.22 crore increase in short-term loans and advances within financing activities as a line to watch in subsequent statements.