










Inox Wind targets Rs 7,500 crore revenue and 20% FY28 margin
Key highlights
- IWL guides for about Rs 7,500 crore revenue and an EBITDA margin of about 20% in FY28.
- Equipment supply is planned to reach about 75% of future deliveries, compared with 27% in FY26.
- IWL's order book was about 3.8 GW in October 2026 and provided more than 24 months of revenue visibility.
- Q2 FY27 revenue was Rs 1,378 crore and reported EBITDA margin was about 17%.
powered by IRIS
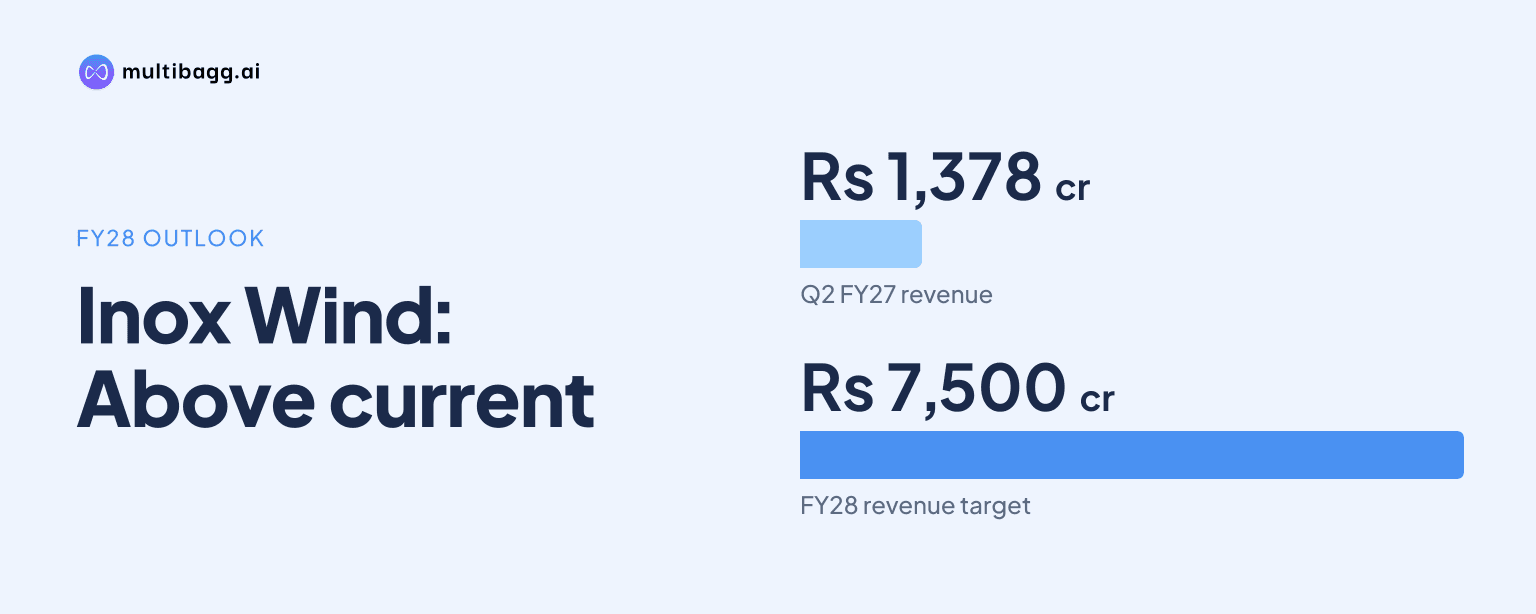
Inox Wind targets about Rs 7,500 crore of revenue and an earnings before interest, tax, depreciation and amortisation (EBITDA) margin of about 20% in FY28, as management plans to shift roughly 75% of future deliveries to equipment supply. The plan also relies on 4X MW turbine sales, manufacturing expansion and operations and maintenance consolidation.
Know Inox Wind inside out
Results, valuation, peers and who's buying, in one view.
What is IWL's FY28 revenue and margin guidance?
IWL guides for about Rs 7,500 crore of revenue and an EBITDA margin of about 20% in FY28. Management says both measures include other income, which is relevant when comparing the target with the company’s reported operating performance.
The FY28 revenue target is above IWL’s total income of Rs 4,569 crore in FY26 and Rs 2,250 crore in H1 FY27. In Q2 FY27, the company reported revenue of Rs 1,378 crore, up 58% quarter on quarter, alongside EBITDA of Rs 238 crore and an EBITDA margin of about 17%.
The FY28 margin target is below the 27% reported in FY25 and FY26, but near the approximately 20% consolidated margin management said Q2 FY27 would have recorded if Wind World operations and maintenance income had been recognised. Management attributed the reported 17% Q2 FY27 margin to commodity and raw-material inflation associated with the West Asia war.
How is IWL shifting from turnkey projects to equipment supply?
IWL plans for equipment supply, including orders with limited engineering, procurement and construction (EPC) scope, to represent about 75% of future deliveries, with end-to-end turnkey work at about 25%. This differs from Q1 FY24, when its delivered projects were approximately 100% turnkey.
The shift had started by FY26, when 73% of delivered projects were turnkey and 27% were equipment supply. In the October 2026 order book, equipment supply made up 61% of third-party order scope, compared with 39% for turnkey projects, placing the booked mix ahead of the FY26 delivery mix.
IWL said in Q2 FY27 that its pivot toward equipment sales and cash flows was beginning to yield revenue growth and lower debtor days. The presentation does not quantify debtor-day reduction or disclose a margin difference between turnkey and equipment-supply contracts, so the financial effect of the planned 75% mix remains a management objective rather than a reported outcome.
What does IWL's recent financial performance show?
IWL’s total income increased from Rs 1,799 crore in FY24 to Rs 3,702 crore in FY25 and Rs 4,569 crore in FY26, a company-stated compound annual growth rate of 59%. EBITDA rose from Rs 325 crore in FY24 to Rs 985 crore in FY25 and Rs 1,232 crore in FY26, while the margin increased from 18% to 27%.
The Q2 comparison showed a different pattern: revenue reached Rs 1,378 crore in Q2 FY27, compared with Rs 1,162 crore in Q2 FY26, while EBITDA declined to Rs 238 crore from Rs 306 crore. EBITDA margin fell to 17% from 26%, profit after tax declined to Rs 69 crore from Rs 121 crore, and cash profit after tax was Rs 165 crore versus Rs 220 crore.
For H1 FY27, IWL reported EBITDA of Rs 479 crore at a 21% margin, profit after tax of Rs 141 crore and cash profit after tax of Rs 327 crore. The company defines cash profit after tax as profit after tax plus depreciation, deferred taxes and minimum alternate tax credit entitlement; its EBITDA figures include other income and exclude expected credit-loss provisions and other one-time charges.
Got a follow-up? Ask IRIS
Which measures does IWL cite for reaching FY28?
IWL cites commercial sales of 4X MW turbines, transformer manufacturing and power-electronics production as operational measures for reaching its FY28 guidance. Its existing turbine platforms are in the 2 MW and 3 MW classes, while it says it is on track to launch 4X MW wind turbine generators.
The company also plans to ramp up transformer manufacturing and make power electronics including inverters, ECS and USS, or unit substations. IWL reports manufacturing capacity of more than 2.5 GW across five facilities and says its new nacelle and hub manufacturing unit is operating in full swing.
On the financial side, IWL expects higher EBITDA from Inox Green after consolidation of acquired operations and maintenance portfolios. Inox Green completed payment for the transfer of Wind World India Limited’s 4.5 GW wind operations and maintenance business through subsidiary Vibhav Energy Private Limited, with line-by-line financial consolidation scheduled from Q3 FY27.
Management says the higher contribution from Inox Green, which it describes as having higher margins, would lift consolidated EBITDA and margin. IWL also identifies long-term recurring orders through a framework agreement with its group independent power producer company, although the presentation does not disclose the agreement’s capacity, revenue value or duration.
What order book and market conditions support IWL's plan?
IWL had an order book of about 3.8 GW in October 2026, which it says provides more than 24 months of revenue visibility. By customer segment, auctions represented 54% of the book, commercial and industrial customers 34%, and public-sector undertakings 12%.
During Q2 FY27, IWL secured 350 MW of orders from public-sector undertakings and independent power producers. Its order book includes Inox Clean, NTPC, CESC, NLC India, Aditya Birla, Amplus/Gentari and Hero Future Energies, although the presentation does not provide contract values or capacities for individual customers.
The presentation records 3.2 GW of wind capacity installed in H1 FY27 after 6.06 GW in FY26. Management cites the Ministry of New and Renewable Energy’s September 2026 expectation of 7.5 GW to 8 GW of wind additions in FY27, while 3.1 GW, or 53%, of renewable capacity tendered in Q2 FY27 comprised wind, hybrid, firm and dispatchable renewable energy, and round-the-clock projects.
Conclusion
IWL’s FY28 plan combines a Rs 7,500 crore revenue target with an EBITDA margin of about 20%, but depends on a substantial change in delivery scope. Equipment supply is planned to rise from approximately zero in Q1 FY24 and 27% in FY26 to about 75% going forward, while the October 2026 order book was already 61% equipment supply by scope.
The next disclosed milestones are line-by-line consolidation of the 4.5 GW Wind World India Limited portfolio from Q3 FY27, commercial sales of 4X MW turbines, and the ramp-up of transformer and power-electronics manufacturing. Management has also said newly priced contracts should help normalise margins after Q2 FY27 cost pressures reduced reported EBITDA margin to 17%.