










Inox Wind Limited Q2 Revenue Rises to ₹1,354.30 Crore
Key highlights
- Inox Wind Limited reported Q2 FY27 consolidated revenue of ₹1,354.30 crore, compared with ₹1,119.18 crore in Q2 FY26.
- H1 FY27 consolidated revenue reached ₹2,168.39 crore, including Q1 FY27 revenue of ₹814.09 crore.
- PAT and EBITDA declined year on year in Q2 FY27, although the supplied report does not provide the corresponding figures.
- Inox Wind Limited identified a ₹300 crore QIP and the planned Wind World O&M acquisition as key developments.
powered by IRIS
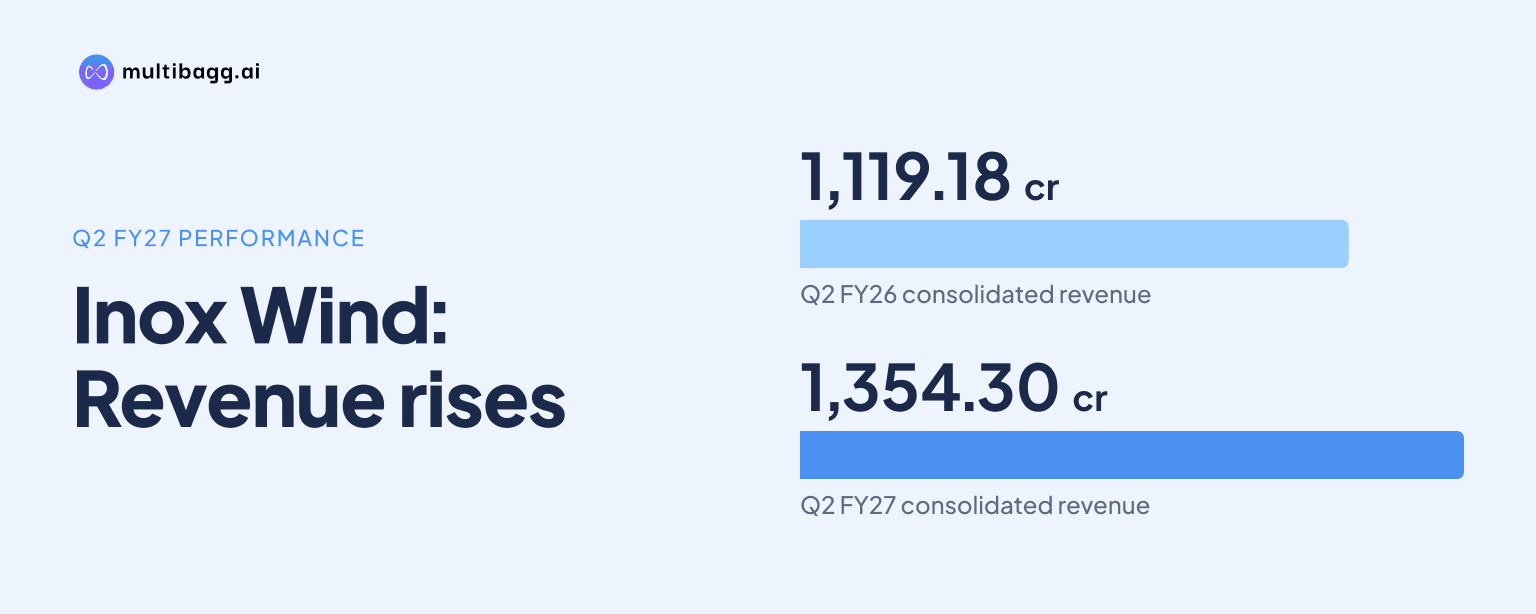
Inox Wind Limited reported Q2 FY27 consolidated revenue of ₹1,354.30 crore, while profit after tax and EBITDA declined year on year. The company’s H1 FY27 revenue reached ₹2,168.39 crore, and a ₹300 crore QIP alongside the planned Wind World O&M acquisition marked the period’s main corporate developments.
Know Inox Wind inside out
Results, valuation, peers and who's buying, in one view.
What did Inox Wind report for Q2 FY27?
Inox Wind reported consolidated revenue from operations of ₹1,354.30 crore for the quarter ended September 30, 2026. This was higher than revenue of ₹1,119.18 crore reported in Q2 FY26, based on the company’s filed quarterly-results data. The increase in quarterly revenue was ₹235.12 crore.
For the first half of FY27, consolidated revenue stood at ₹2,168.39 crore. The H1 figure includes Q1 FY27 revenue of ₹814.09 crore and the Q2 revenue reported for the September quarter. Revenue therefore improved sharply from the first quarter, although the source notes that profitability measures moved in the opposite direction on a year-on-year basis.
The interim report states that both profit after tax, or PAT, and EBITDA declined from the comparable Q2 period a year earlier. It does not provide the corresponding Q2 FY27 PAT and EBITDA figures in the supplied material. As a result, the reported revenue growth and the year-on-year profitability decline need to be assessed separately.
How did the quarter’s corporate developments unfold?
Inox Wind’s board was scheduled to meet on Friday, November 13, 2026, to approve the unaudited financial results for Q2 and H1 FY27. The company also scheduled a post-results conference call for analysts and institutional investors at 5:00 p.m. IST on the same day.
The call was set to include Kailash Tarachandani, Group CEO, Renewables Business at the InoxGFL Group, along with senior management. Its stated purpose was discussion of the financial results for the quarter and half year ended September 30, 2026. The supplied disclosure does not confirm the availability of a presentation, transcript, or recording.
A qualified institutional placement, or QIP, of ₹300 crore was identified as another key development during the period. The article data does not specify the issue price, investor participation, or use of proceeds. It therefore establishes the size of the fundraising but not its final allocation across operations, capital expenditure, or the proposed transaction.
The company was also progressing with a planned acquisition of Wind World’s operations and maintenance, or O&M, business. The available material identifies this as an important strategic development but does not disclose transaction value, closing conditions, financing terms, or a completion date.
What do the reported financial figures show?
The reported figures show higher Q2 and H1 revenue, while the company recorded lower year-on-year PAT and EBITDA for the September quarter. The gap between revenue performance and profitability is material because sales growth alone does not show the full financial outcome of a period.
The quarterly series available in the source also shows that revenue from operations was ₹814.09 crore in Q1 FY27. Q2 revenue of ₹1,354.30 crore was therefore ₹540.21 crore higher sequentially. However, the supplied information does not provide comparable quarterly EBITDA or PAT amounts that would allow a precise margin comparison.
Got a follow-up? Ask IRIS
Why do revenue growth and lower profit both matter?
Revenue growth indicates that Inox Wind recorded a higher level of operations in Q2 FY27 than in the year-earlier quarter. With H1 revenue at ₹2,168.39 crore, the company entered the second half with a larger reported revenue base than the ₹814.09 crore posted in Q1 alone.
But the decline in PAT and EBITDA means investors cannot treat the revenue increase as a direct measure of earnings improvement. EBITDA is a measure of operating performance before interest, tax, depreciation and amortisation, while PAT reflects profit after those costs and taxes. The supplied report does not identify the specific reasons for the year-on-year declines, so no cause can be assigned from the available disclosures.
Earlier company materials referenced growth guidance for FY27, including a 75% revenue-growth target. The source also notes that meeting this target would require a significant acceleration in the remaining period. That is a disclosed guidance context rather than a confirmed full-year result.
How could the QIP and O&M acquisition affect stakeholders?
The ₹300 crore QIP is relevant to shareholders because it is a capital-raising event, while the planned Wind World O&M acquisition is relevant to the company’s service operations. The materials supplied do not state the number of shares issued under the QIP or whether the acquisition will be funded through the placement.
For customers and wind-project operators, an expanded O&M platform could be significant because maintenance services are tied to the operation of installed wind assets. However, the disclosure does not provide the acquired asset base, customer contracts, geographic footprint, or expected revenue contribution from Wind World’s O&M business.
For investors, the main confirmed facts are the revenue increase, the decline in quarterly PAT and EBITDA, the ₹300 crore QIP, and the planned acquisition. Further assessment will depend on management’s disclosures on profitability, capital deployment, acquisition terms, and the company’s progress against its FY27 guidance.
Conclusion
Inox Wind Limited’s Q2 FY27 update presents a mixed financial picture. Consolidated revenue rose to ₹1,354.30 crore and H1 revenue reached ₹2,168.39 crore, but PAT and EBITDA declined year on year. The period also included a ₹300 crore QIP and progress on the planned Wind World O&M acquisition.
Investors will watch for management’s discussion of the Q2 and H1 results, including the factors behind lower profitability, the deployment of QIP proceeds, and transaction details for the O&M acquisition. The company’s disclosed FY27 growth guidance will also remain a reference point as it reports performance in the second half.