










Ion Exchange fully provides for legacy overruns after Q2 loss
Key highlights
- Treatment Solutions reported a Q2 FY27 EBIT loss of Rs 121.5 crore, compared with a Rs 12.2 crore loss in Q2 FY26.
- Ion Exchange said it recorded the full currently estimated legacy-project overrun impact in Q2 FY27.
- The legacy project is more than 90% complete but will spill into the next financial year.
- Ion Exchange reported a Rs 9,370 crore bid pipeline at September-end and Rs 813 crore of Q2 order inflow.
powered by IRIS
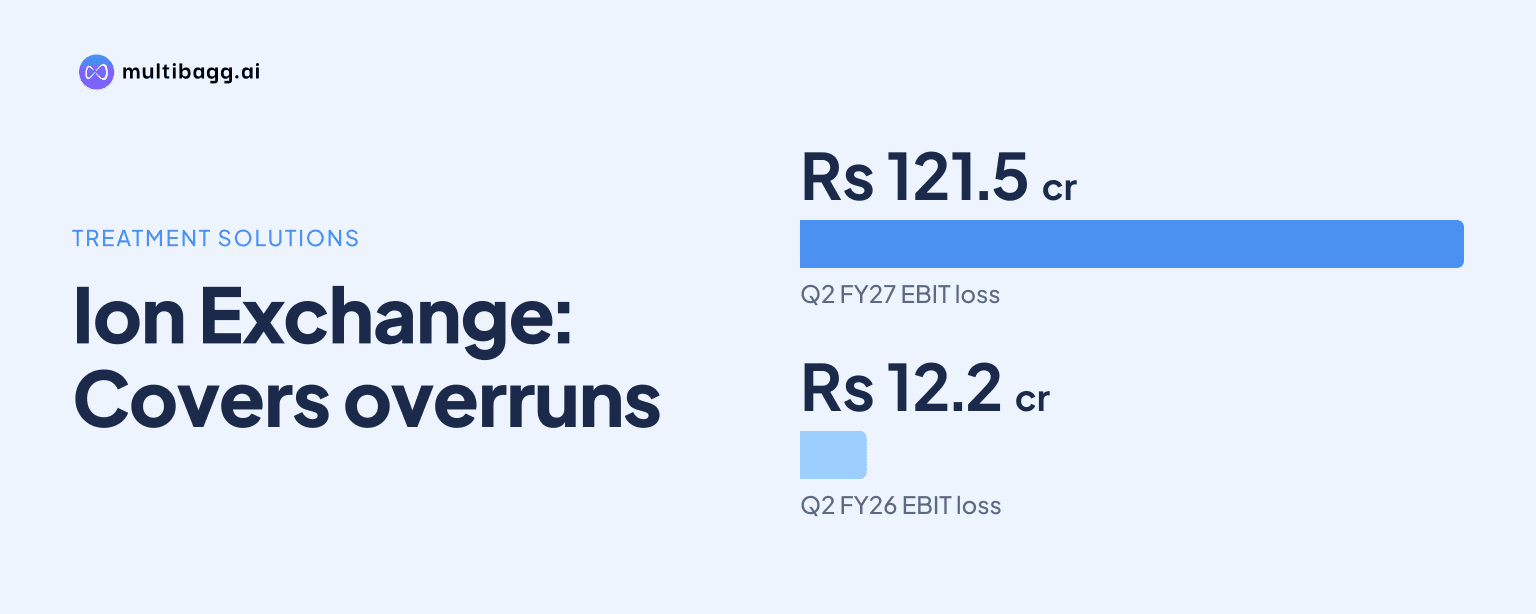
Ion Exchange said it recorded the entire currently estimated impact of legacy-project cost overruns in Q2 FY27, when Treatment Solutions reported an EBIT loss of Rs 121.5 crore on revenue of Rs 149.8 crore. Management said the relevant contract is more than 90% complete, but its execution will extend into the next financial year.
Know Ion Exchange (India) inside out
Results, valuation, peers and who's buying, in one view.
Why did Ion Exchange report a Treatment Solutions loss in Q2 FY27?
Ion Exchange said revised estimated costs to complete certain legacy projects were the main reason for the Treatment Solutions loss in Q2 FY27. Segment revenue fell to Rs 149.8 crore from Rs 295.8 crore in Q2 FY26, while EBIT, or earnings before interest and tax, widened to a loss of Rs 121.5 crore from a loss of Rs 12.2 crore.
The company gave three reasons for the revenue reduction in Treatment Solutions. Some high-volume work in the existing backlog was contractually scheduled for the second half of FY27, certain Gulf Cooperation Council dispatches were deferred because of the Middle East crisis, and revenue recognised on some contracts was reversed under the applicable accounting standard to match costs. In the first half of FY27, segment revenue was Rs 359.7 crore against Rs 479.7 crore a year earlier, and EBIT was a loss of Rs 138.9 crore.
The Q2 comparison shows that the Treatment Solutions revenue decline was much larger than the changes in the other disclosed operating segments. Industrial Products revenue rose by about 35% to Rs 136.0 crore, while Specialty Chemicals increased by about 17% to Rs 254.6 crore and Consumer Products rose by about 30% to Rs 100.5 crore.
Has Ion Exchange fully accounted for legacy cost overruns?
Ion Exchange said it included the entire impact of its current estimate of the legacy-project overruns in Q2 FY27 financial results. Management said it now has a “very good estimate” of the exposure and believes the cost-overrun and profitability risk discussed on calls for about eight quarters has reached “the bottom of the barrel.”
An analyst said the charge contributed around 90% of the quarter’s negative profit before tax, or PBT, but Ion Exchange did not independently quantify that contribution. Management confirmed that the project remains unfinished, distinguishing between recognising the estimated overrun in Q2 FY27 and completing the remaining physical execution.
Management said its current assessment is that the remaining work should not result in a further material adverse impact on that contract. That is an assessment rather than a guarantee: Ion Exchange said it would continue to monitor the situation as the project moves into the next financial year.
When will Ion Exchange finish the legacy project?
Ion Exchange said the legacy project is more than 90% complete but will spill into the next financial year. The project had previously been expected to finish in the current financial year, but management now expects the balance of the work to be completed after FY27.
The delayed completion coincides with deferred Middle East dispatches and a second-half execution schedule for other high-value Treatment Solutions work. Management said it has greater confidence in revenue from the existing backlog and believes orders planned for the region should proceed according to its plan, despite dispatch disruptions during the first half.
Ion Exchange also received an international filtration-unit contract from Hyundai Engineering and Construction Company Limited for the Middle East. Management described the contract as having a better margin profile and said it was working with the customer to recognise a portion of its revenue in FY27, although it did not disclose the expected contribution from that individual contract.
Got a follow-up? Ask IRIS
What margin outlook has Ion Exchange given for Treatment Solutions?
Ion Exchange said it expects Treatment Solutions to return to its average margin and expects higher single-digit margins in the balance of FY27. Management said the Q1 FY27 margin should be maintained and that second-half execution could provide some upside.
The outlook follows a sharply loss-making first half for the segment, with EBIT at negative Rs 138.9 crore in H1 FY27 and negative Rs 121.5 crore in Q2 alone. Management linked the potential improvement to planned backlog execution, rather than presenting a margin outcome as assured.
Ion Exchange said it expects to finish FY27 close to the previous full-year Treatment Solutions revenue level, based on the order backlog, planned execution and potential FY27 contribution from the Hyundai contract. Management said it expected to provide a clearer year-end outlook after the next quarter because the first half of FY27 had been softer.
How did Ion Exchange's other segments perform in Q2 FY27?
Ion Exchange reported revenue growth in Industrial Products, Specialty Chemicals and Consumer Products in Q2 FY27, while Lifecycle Services revenue was lower than a year earlier. Industrial Products revenue reached Rs 136.0 crore from Rs 100.9 crore and EBIT increased to Rs 8.6 crore from Rs 7.4 crore; first-half revenue was Rs 241.1 crore and EBIT was Rs 21.0 crore, compared with Rs 12.4 crore in H1 FY26.
Specialty Chemicals revenue increased to Rs 254.6 crore from Rs 218.1 crore in Q2 FY26, while EBIT was Rs 22.5 crore. Management said margins were affected by higher input costs associated with the West Asia crisis and costs at the Roha facility. It quantified the Roha effect at around 7% at segment level and the unpassed input-cost effect at about 7% to 8%, with higher exchange gains in the previous year accounting for the balance of roughly 18%.
Lifecycle Services reported Q2 revenue of Rs 70.6 crore against Rs 77.0 crore a year earlier, with EBIT of Rs 5.9 crore, although first-half revenue rose to Rs 142.2 crore from Rs 132.9 crore. Consumer Products revenue climbed to Rs 100.5 crore from Rs 77.1 crore, but EBIT loss widened to Rs 4.1 crore from Rs 2.3 crore as Ion Exchange continued investment intended to scale that business.
Ion Exchange’s bid pipeline stood at Rs 9,370 crore at the end of September, while Q2 order inflow was Rs 813 crore. Management said the pipeline was largely industrial, across domestic and international markets, with refining, power and steel among the contributing sectors. It also said the order backlog supports higher Treatment Solutions turnover in the second half of FY27.
Conclusion
Ion Exchange’s Q2 FY27 Treatment Solutions loss combined the accounting effect of its current estimate of legacy-project overruns with lower revenue from planned second-half execution, deferred Gulf Cooperation Council dispatches and contract-related revenue reversals. The company has accounted for the estimated overrun but still has work remaining on a project that is more than 90% complete.
The next developments to watch are second-half backlog execution, the timing of deferred Middle East dispatches and any FY27 revenue from the Hyundai filtration contract. Management expects higher single-digit Treatment Solutions margins in the balance of FY27 and said it would offer a clearer full-year outlook after the next quarter.