










Shree Siddhivinayak Plans 60% Capacity Rise Without Order
Key highlights
- Shree Siddhivinayak proposes to add 750 TCD, increasing crushing capacity from 1,250 TCD to 2,000 TCD.
- The core IPO-funded equipment package totals Rs 23.54 crore, including Rs 3.59 crore of GST.
- Shree Siddhivinayak had not placed the core equipment order when it disclosed the expansion proposal.
- The company targets setup by December 2027 and assigns Rs 15.54 crore of capital expenditure to FY 2027-2028.
powered by IRIS
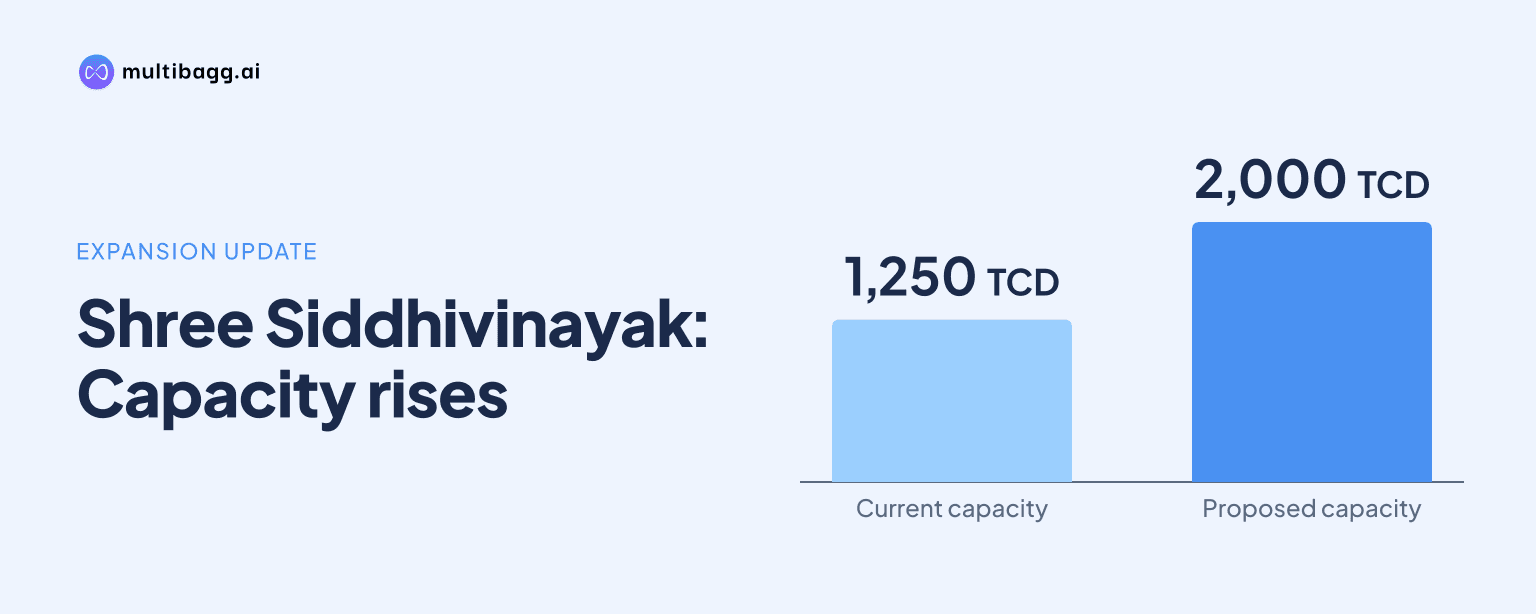
Shree Siddhivinayak Greentech Industries Limited plans to increase sugarcane crushing capacity by 60%, from 1,250 to 2,000 metric tonnes crushed per day (TCD), supported by a Rs 23.54 crore equipment package, but had not placed the equipment order when it disclosed the proposal. The expansion is targeted for setup by December 2027.
How will Shree Siddhivinayak’s 60% crushing capacity expansion work?
Shree Siddhivinayak intends to add 750 TCD at its existing factory at Gat No. 912, Khamaswadi, Kallam, Osmanabad, Maharashtra, raising crushing capacity from 1,250 TCD to 2,000 TCD. TCD means metric tonnes of sugarcane crushed per day. The company cites average utilisation of about 90% of the current 1,250-TCD capacity as the basis for the planned expansion.
Shree Siddhivinayak expects the larger plant to process more sugarcane during the crushing season and increase output of jaggery powder, Khandsari sugar, bagasse, molasses, press-mud and ash. This outcome is conditional on adequate sugarcane availability and prevailing market conditions. The company holds licences to crush 1,500 TCD for jaggery powder and 900 TCD for Khandsari sugar.
Shree Siddhivinayak has previously developed the same operating site. It spent Rs 37.85 crore excluding goods and services tax (GST) on the jaggery-powder factory in FY 2023-2024, Rs 9 lakh excluding GST on jaggery-based premix machinery in FY 2024-2025, and Rs 10.17 crore excluding GST on the Khandsari sugar facility expansion in FY 2025-2026.
What does Shree Siddhivinayak’s Rs 23.54 crore equipment package include?
Shree Siddhivinayak proposes to fund Rs 23.54 crore of milling-house and boiling-house equipment from initial public offering (IPO) proceeds. The amount comprises Rs 19.95 crore for equipment design, fabrication, supply, erection and commissioning, plus Rs 3.59 crore of GST at 18%, based on a quotation dated November 11, 2026 from M/s. N.R. Fabricators and Erectors.
The milling-house equipment list includes a changed cane-carrier drive, a zero mill with a 350-horsepower drive, four 24-inch by 48-inch TRPF units, raw-juice pumps, flow meters and a motor-control-centre panel. The boiling-house list includes two juice heaters, a 1,200-square-metre evaporator body, a 50-metric-tonne batch pan, a 60-metric-tonne air-cooled crystalliser, a centrifugal machine and a motor-control-centre panel.
The Rs 23.54 crore allocation covers only serial number 1 of the vendor quotation. It does not establish a total fixed project cost because serial numbers 2 to 6, along with several site obligations, are outside the specified IPO-funded equipment package. The vendor also states that material prices are based on prevailing market rates and may vary when the purchase order is issued.
Which Shree Siddhivinayak expansion costs are outside the quoted package?
Shree Siddhivinayak says it will fund quotation serial numbers 2 to 6 through internal accruals or general corporate purposes, as applicable. These are variable-rate activities: staging, structures and piping supply at Rs 100 per kilogram; erection at Rs 17 per kilogram; dismantling old equipment at Rs 12 per kilogram; fabrication at Rs 17 per kilogram; and new-material erection at Rs 19 per kilogram.
The vendor quotation also assigns civil foundations, factory lighting, factory building work, sugar-conveying systems, a sugar godown, air conditioning, a control cabin, an uninterruptible power supply, an effluent-treatment plant and laboratory requirements to Shree Siddhivinayak. The document does not state an aggregate cost for these activities, so total spending depends on quantities, material prices and site work needed at the existing factory.
The payment terms require a 40% advance with the purchase order and the balance 60%, plus 100% GST, against a proforma invoice. Delivery is stated as eight to 10 months after receipt of the purchase order and completion of civil foundation work. The quoted rates are valid for six months, making the timing and cost dependent on ordering and completion of company-funded prerequisites.
Got a follow-up? Ask IRIS
Has Shree Siddhivinayak placed the 2,000-TCD equipment order?
No, Shree Siddhivinayak states that it had not placed an order for the design, manufacturing, supply, erection and commissioning of the milling-house and boiling-house equipment. The November 11, 2026 quotation identifies a prospective supplier and equipment scope, but the company expressly distinguishes it from an order.
Shree Siddhivinayak estimates that the machinery, plant and equipment for the expansion will be set up on or before December 2027. Since the disclosed eight-to-10-month delivery period starts after both the purchase order and civil-foundation completion, the estimate requires the order, advance payment, civil work, delivery and installation to proceed on the company’s schedule.
The IPO deployment schedule assigns Rs 8 crore of capital expenditure to FY 2026-2027 and Rs 15.54 crore to FY 2027-2028. Shree Siddhivinayak intends to deploy IPO proceeds for the stated objects by March 31, 2028, but says unutilised amounts may be used in subsequent periods as decided by its board in accordance with applicable law.
What approvals and funding conditions affect Shree Siddhivinayak’s expansion?
Shree Siddhivinayak says it possesses licences for its existing manufacturing facility, although certain licences require amendment or revision for the expansion. It received Consent to Establish on August 10, 2026 under water-pollution, air-pollution and hazardous-waste rules. The company says it will apply for Consent to Operate after completing the expansion.
The disclosure also identifies a factory licence and a fire-safety certificate among approvals requiring revision or related action. The facility location is already leased for Shree Siddhivinayak’s operations, while the proposed equipment is described as new machinery rather than used equipment.
The wider IPO fund requirement includes Rs 23.54 crore for capital expenditure and Rs 48.50 crore for repayment or prepayment of borrowings, or Rs 72.04 crore before the unspecified general corporate-purpose amount. As of October 31, 2026, Shree Siddhivinayak reported Rs 50.54 crore of secured borrowings and proposed to use Rs 48.50 crore, equal to 95.96% of that portfolio, for repayment or prepayment.
Shree Siddhivinayak says its funding requirements and proposed deployment have not been appraised by a bank, financial institution or independent agency. If IPO proceeds are insufficient or project costs rise, the company may use internal accruals, additional equity or debt arrangements, or reallocate net proceeds in accordance with applicable law.
Conclusion
Shree Siddhivinayak’s plan to move from 1,250 TCD to 2,000 TCD is based on about 90% average use of existing capacity and identifies Rs 23.54 crore for core milling-house and boiling-house equipment. However, the equipment order remains unplaced, variable-rate work sits outside the quoted package, and the company retains responsibility for civil, utility, storage, environmental-treatment and laboratory-related requirements without a disclosed aggregate cost.
The next disclosed milestones are purchase-order placement, completion of civil foundations, revision or application for operating approvals, and the target to set up the expansion by December 2027. Shree Siddhivinayak also plans Rs 8 crore of capital expenditure in FY 2026-2027 and Rs 15.54 crore in FY 2027-2028, with March 31, 2028 identified for intended deployment of IPO proceeds.