










iServeU returns to positive EBITDA but misses margin guidance
Key highlights
- iServeU net revenue rose 15% quarter on quarter to Rs 18.1 crore in Q2 FY27.
- iServeU adjusted EBITDA was Rs 1.2 crore in Q2 FY27, compared with a Rs 0.5 crore loss in Q1 FY27.
- iServeU's reported 6.8% adjusted EBITDA margin was below management's 20% to 25% Q2 FY27 guidance.
- iServeU UPI GTV increased to Rs 1,134 crore in Q2 FY27 from Rs 703 crore in Q1 FY27.
powered by IRIS
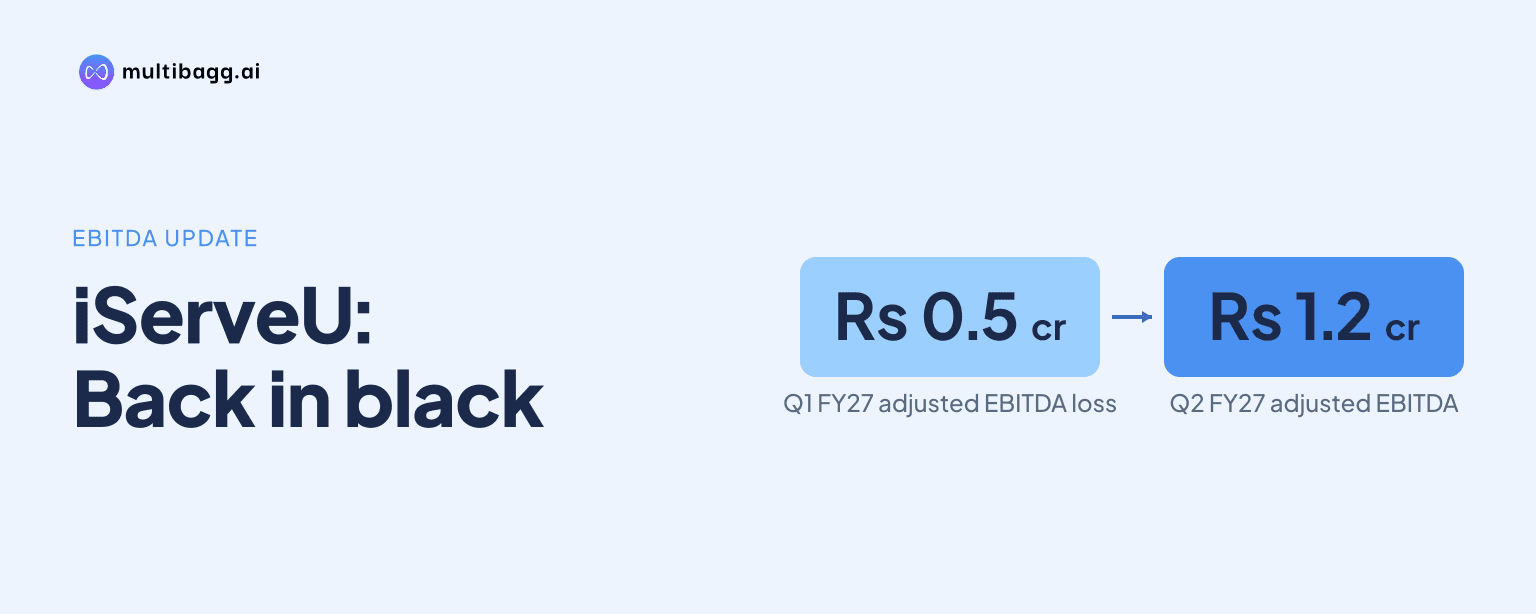
iServeU returned to positive adjusted EBITDA of Rs 1.2 crore in Q2 FY27 from a Rs 0.5 crore loss in Q1 FY27, but its reported 6.8% adjusted EBITDA margin remained below management's 20%-25% guidance. Net revenue rose 15% sequentially to Rs 18.1 crore, supported by program-management, SaaS and payment activity.
Know Niyogin Fintech inside out
Results, valuation, peers and who's buying, in one view.
How did iServeU perform in Q2 FY27?
iServeU improved sequentially in Q2 FY27, with net revenue of Rs 18.1 crore versus Rs 15.8 crore in Q1 FY27. The 15% quarter-on-quarter increase also put net revenue 5% above Rs 17.2 crore in Q2 FY26, although it remained below Rs 21.2 crore in Q3 FY26 and Rs 21.1 crore in Q4 FY26.
Adjusted EBITDA, or earnings before interest, tax, depreciation and amortisation after adjustments, was Rs 1.2 crore in the Q2 FY27 financial table, compared with a Rs 0.5 crore loss in Q1 FY27. The chart narrative separately states Rs 1.3 crore for Q2 FY27, a Rs 0.1 crore difference within the presentation; both disclosures show a return to positive adjusted EBITDA, while the table shows a 65% decline from Rs 3.5 crore in Q2 FY26.
Reported profit before tax, or PBT, remained negative at Rs 3.4 crore in Q2 FY27, although the loss narrowed from Rs 5.6 crore in Q1 FY27. The Q2 result also compares with a reported PBT profit of Rs 1.0 crore in Q2 FY26, while depreciation and amortisation of Rs 2.6 crore and finance cost of Rs 3.3 crore exceeded reported EBITDA of Rs 2.5 crore.
What drove iServeU's sequential revenue growth?
iServeU's Q2 FY27 net-revenue growth was led by program management, which rose 54% sequentially to Rs 7.4 crore from Rs 4.8 crore. Technology service provider, or TSP, and software-as-a-service, or SaaS, revenue increased 2% to Rs 9.3 crore from Rs 9.1 crore, meaning the two lines together contributed Rs 16.7 crore of Q2 net revenue.
TSP/SaaS revenue was 142% above Rs 3.8 crore in Q2 FY26, compared with Rs 9.3 crore in Q2 FY27. Recurring SaaS contributed Rs 6.0 crore, up from Rs 5.0 crore in Q1 FY27, and represented 65% of TSP/SaaS revenue; other operational income declined 27% sequentially to Rs 1.4 crore from Rs 1.9 crore.
Payment activity also increased, with Unified Payments Interface, or UPI, gross transaction value, or GTV, rising to Rs 1,134 crore in Q2 FY27 from Rs 703 crore in Q1 FY27 after multiple payment aggregators were onboarded. iServeU also reported quarterly soundbox deployments of 61.3 thousand units and cumulative installations of about 600 thousand units, while noting that deployment depends on device availability and supply conditions.
Got a follow-up? Ask IRIS
How far was iServeU below its profitability guidance?
iServeU was below management's Q2 FY27 revenue and profitability guidance despite the sequential recovery. Net revenue of Rs 18.1 crore was below the earlier Rs 21 crore to Rs 24 crore estimate, and the reported 6.8% adjusted EBITDA margin was below the 20% to 25% range.
The Q2 margin was also below iServeU's FY26 adjusted EBITDA margin of 22.4%. Management retained a 20% to 25% adjusted EBITDA-margin estimate for Q3 FY27 and FY27, alongside net-revenue estimates of Rs 20 crore to Rs 25 crore for Q3 FY27 and Rs 80 crore to Rs 100 crore for FY27, compared with Rs 74.7 crore of FY26 net revenue.
The presentation says delivery of the FY27 outlook depends on customer implementation, revenue realisation, funding availability and prevailing business conditions. Its disclosed order book of about Rs 546 crore is an outstanding contract base rather than recognised revenue, because recognition depends on implementation schedules and customer utilisation.
What costs and execution priorities affect iServeU's outlook?
iServeU's reported EBITDA rose to Rs 2.5 crore in Q2 FY27 from Rs 0.7 crore in Q1 FY27, while operating expenses moved in different directions. Employee expenses were Rs 5.4 crore versus Rs 5.3 crore, information-technology expense declined 8% to Rs 3.4 crore, communication expense rose 14% to Rs 2.6 crore, and other expense increased 10% to Rs 4.2 crore.
Gross revenue fell 15% year on year to Rs 34.3 crore from Rs 40.1 crore in Q2 FY26, even as net revenue rose 5% to Rs 18.1 crore from Rs 17.2 crore. Communication expense was 76% above Rs 1.5 crore a year earlier, and other expense was 31% above Rs 3.2 crore, indicating that the quarterly recovery in net revenue occurred alongside higher costs in those two lines.
Management's stated priorities include converting signed contracts into revenue-generating engagements, expanding recurring SaaS, improving infrastructure utilisation and pursuing institutional partnerships. The new soundbox and device model added select aggregators in Q2 FY27, and iServeU said execution readiness is improving as chip availability normalises; recurring SaaS revenue of Rs 6.0 crore is the current reported base for that plan.
Conclusion
iServeU's Q2 FY27 results show a sequential operating recovery, with net revenue rising Rs 2.3 crore, adjusted EBITDA returning to positive territory and UPI GTV increasing Rs 431 crore from Q1 FY27. Program management supplied the largest revenue increase, while recurring SaaS reached Rs 6.0 crore; however, the reported 6.8% adjusted EBITDA margin remained below management's 20% to 25% range.
The next disclosed milestones are management's Q3 FY27 estimates of Rs 20 crore to Rs 25 crore in net revenue and a 20% to 25% adjusted EBITDA margin. The pace of conversion from the approximately Rs 546 crore order book, customer implementation and utilisation, and soundbox deployment as device supply conditions change are the disclosed factors to watch.