










Isgec expects Rs 1,200 crore expansion revenue by FY29
Key highlights
- Isgec expects its Rs 500 crore manufacturing expansion to add Rs 1,200 crore of revenue by FY29.
- Isgec expects less than Rs 100 crore of expansion-linked revenue in the current year.
- Isgec discussed consolidated products revenue potential of about Rs 4,000 crore by FY29.
- Products represented 38% of Isgec's consolidated order book above Rs 10,000 crore.
powered by IRIS
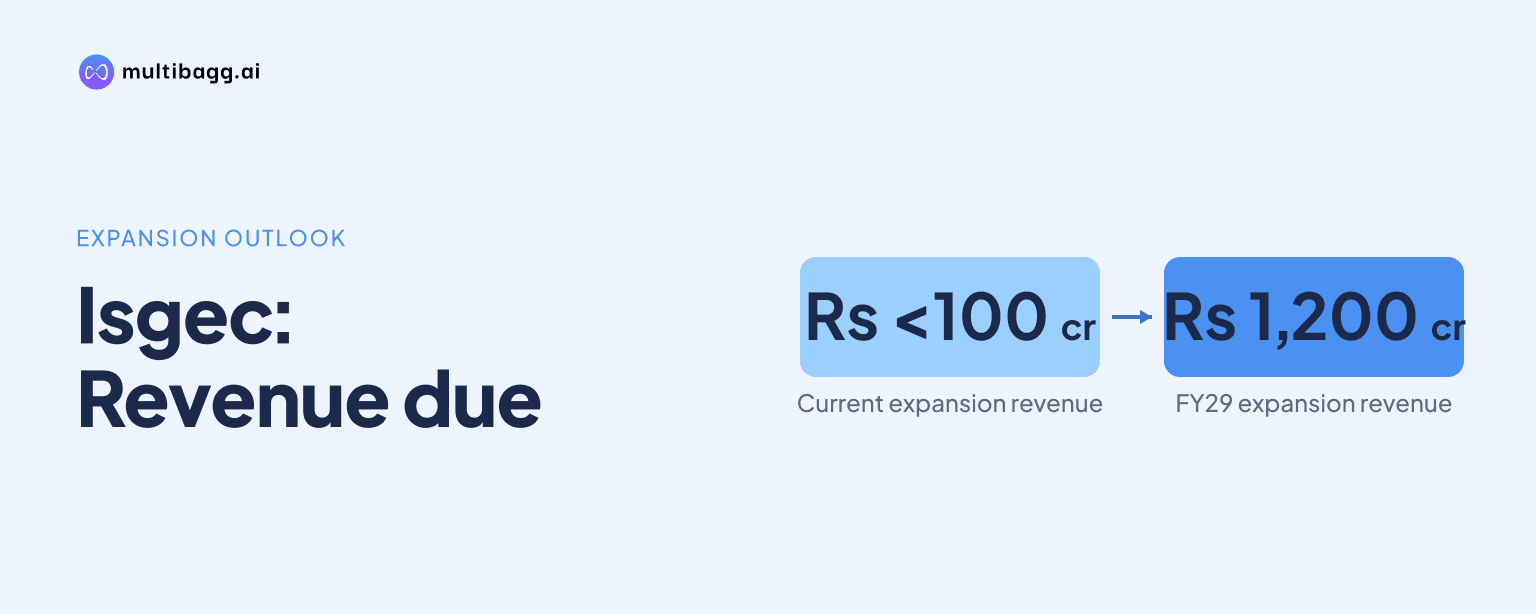
Isgec Heavy Engineering Limited expects its ongoing Rs 500 crore manufacturing expansion to generate Rs 1,200 crore of incremental revenue by FY29. Management said less than Rs 100 crore should be recognised in the current year, while the major contribution is expected in the next year and the following year.
Know ISGEC Heavy Engineering inside out
Results, valuation, peers and who's buying, in one view.
What revenue will Isgec's expansion generate by FY29?
Isgec expects the existing Rs 500 crore expansion programme to add Rs 1,200 crore of revenue by FY29. Management gave the FY29 deadline when asked whether the incremental revenue could instead arrive in FY30, stating that it would be there in FY29.
The Rs 1,200 crore figure is incremental revenue from the current capacity programme, rather than a forecast based on potential future spending. Management had earlier said the ongoing expansion could support Rs 3,500 crore of products revenue over the next two to three years, and agreed on the call that about Rs 4,000 crore of consolidated products revenue by FY29 was a reasonable figure.
The Rs 4,000 crore potential was discussed on a consolidated basis. An analyst described products revenue as already above Rs 2,700 crore and suggested a higher figure than Rs 3,500 crore after adding the Rs 1,200 crore expansion opportunity; management agreed with the Rs 4,000 crore consolidated assessment.
When will Isgec recognise revenue from new capacity?
Isgec expects less than Rs 100 crore of the Rs 1,200 crore incremental revenue in the current year. Management said the major part would start coming in from the next year and the following year, indicating that the revenue ramp-up precedes the stated FY29 completion point.
Management said the expansions are largely on schedule and that it is taking certain orders in anticipation of their completion. It said it did not see significant delays in customer commitments and expected those orders to be executed on time, though it did not disclose commissioning dates by plant or product line.
The phased timing matters because capacity utilisation and order execution will determine how quickly the programme converts into sales. Management did not provide quarterly revenue targets for the new facilities, so the less-than-Rs 100 crore current-year contribution is the only near-term numerical marker disclosed on the call.
What demand is supporting Isgec's manufacturing expansion?
Isgec said demand was robust across almost all product and project lines when domestic and export markets were considered together. Management identified automobiles, oil and gas, petrochemicals, cement and steel among the industries from which orders were coming.
The consolidated order book had crossed Rs 10,000 crore, according to an analyst on the call, and products represented 38% of that order book. The analyst said the products share had historically been around 25% to 28%, so the 38% level marks a higher products mix before all capex programmes have come on stream.
Management clarified that the 38% share was consolidated and included Isgec Heavy Engineering as well as Isgec Hitachi Zosen. It did not disclose a product-wise revenue split for presses, boilers or heat exchangers, saying the mix changes between quarters and years and that providing such figures would not be meaningful.
Management said it believed market share had improved and that its products were being well received, while expressing optimism that demand would continue. Those are management views, not quantified market-share data, and the call did not separate domestic and export order values within the Rs 10,000 crore-plus order book.
Got a follow-up? Ask IRIS
Will Isgec increase capex beyond Rs 500 crore?
Isgec is evaluating further capital expenditure, but it has not finalised any addition to the Rs 500 crore programme. Asked whether robust domestic and international demand could lead to a capex top-up over the next two or three years, management said there was a good possibility but no firm decision.
The disclosed Rs 1,200 crore revenue target therefore applies to the existing programme. Management gave neither an amount nor a timetable for possible additional capacity, so any future top-up cannot be included in the FY29 revenue potential stated on the call.
Management also said it expected to maintain earnings before interest and tax, or EBIT, margins of 12% to 13%. It did not give a separate EBIT margin target specifically for the Rs 1,200 crore of incremental expansion revenue, so the 12% to 13% range applies to the broader products-related discussion.
How is Isgec addressing pricing and execution risk?
Isgec said most product orders are fixed-price contracts, while project contracts are handled case by case and not many include price-variation clauses. In manufactured products, management said material costs typically account for 50% to 60%, depending on the product.
To manage that exposure, management said it generally discusses back-to-back offers with suppliers before bidding, uses rate contracts for certain items and retains contingencies. It said this process means the company usually knows the cost of most items when it bids rather than relying solely on assumptions.
For projects, Isgec said it is avoiding very long-duration work and contracts that would form a significant share of total order value. Management said its shift toward shorter-cycle and more technology-oriented projects reduces uncertainty, improves cash flows and reduces the risk of customer liquidity problems before completion.
This operating approach is relevant to the expansion because management is accepting some orders ahead of capacity completion. However, it did not provide a value for orders specifically linked to the Rs 500 crore programme, nor did it disclose a product-level allocation of the Rs 1,200 crore incremental revenue target.
Conclusion
Isgec has set a defined target for its existing capacity programme: Rs 500 crore of manufacturing expansion is expected to add Rs 1,200 crore of revenue by FY29. The target is being pursued alongside a products share of 38% in a consolidated order book above Rs 10,000 crore, compared with the 25% to 28% range cited for earlier periods.
The next measures to watch are the less-than-Rs 100 crore contribution expected in the current year, the main ramp-up in the next two years and whether management turns its evaluation of further capex into an approved plan. Management’s FY29 delivery target and its stated expectation of maintaining 12% to 13% EBIT margins provide the disclosed benchmarks for tracking progress.