










Jio Platforms Limited valuation leaves little target upside
Key highlights
- Jio Platforms Limited's average 12-month analyst target is ₹1,430, implying 2.99% upside from ₹1,395.90.
- Jio Platforms' P/E was 40.24 and P/B was 3.34 as of November 20, 2026.
- Elara forecasts Jio Platforms' FY26-FY29E adjusted PAT CAGR at 23% and EBITDA margin at 53.8% in FY29E.
- Jio Platforms generated trailing 12-month free cash flow of about ₹374 billion in the supplied DCF assessment.
powered by IRIS
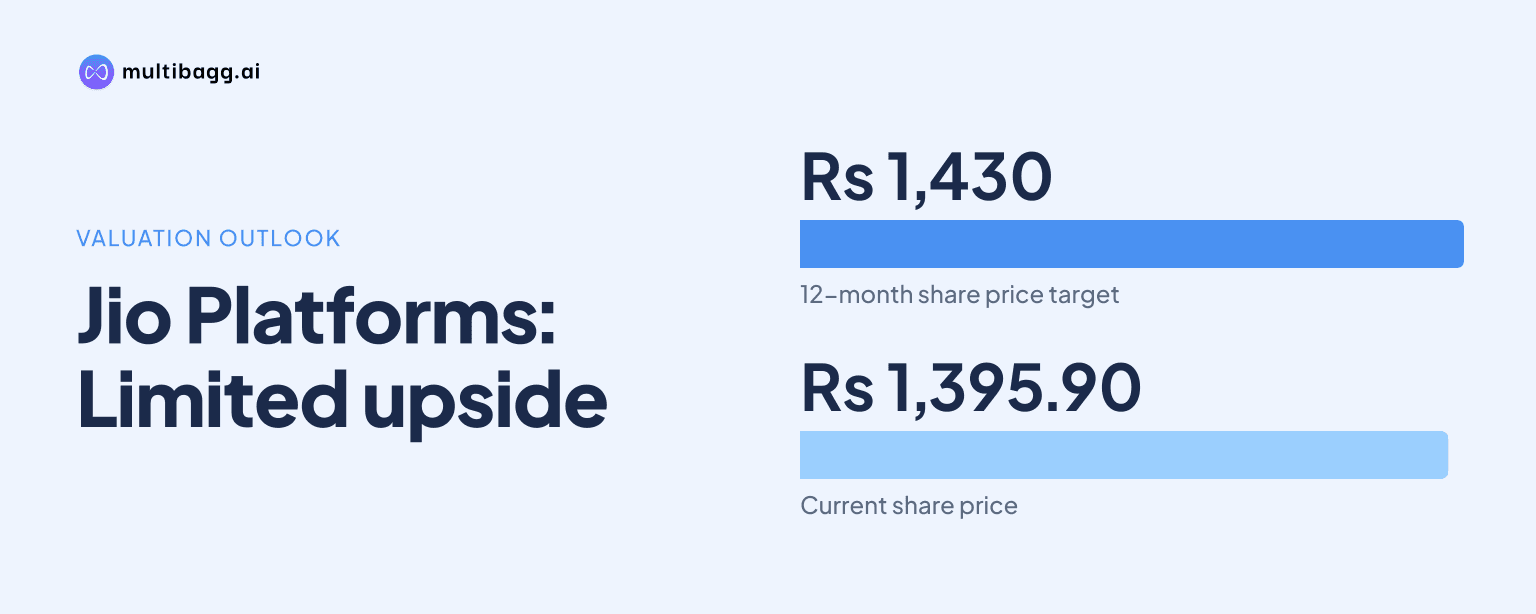
Jio Platforms Limited traded at ₹1,395.90 in the supplied valuation assessment, while the average 12-month analyst target of ₹1,430 indicated only 2.99% upside. The company has strong projected growth and positive analyst ratings, but its current valuation already reflects much of that expected improvement.
Why is Jio Platforms Limited's target upside limited?
Jio Platforms' published analyst targets cluster close to the prevailing share price, limiting the implied near-term return. The average 12-month target from three analysts is ₹1,430, while the median target cited separately is ₹1,401. Both are near the assessed market price of ₹1,395.90, even though the highest published target is ₹1,515.
The target range also shows that brokerage views are not uniformly more optimistic than the market. Motilal Oswal has a Buy rating and a ₹1,515 target, but Elara Capital's ₹1,367 target and Nomura's ₹1,340 target sit below the ₹1,440 comparison price in the supplied brokerage table. That makes execution on earnings, margins and tariffs important for any further re-rating.
Is Jio Platforms fairly valued at its current price?
Jio Platforms appears broadly fairly valued on the supplied discounted cash flow assessment, which places its intrinsic value close to the current share price. The model starts with trailing 12-month free cash flow of about ₹374 billion and assumes free cash flow rises over the next decade rather than remaining flat.
Relative valuation signals are less comfortable. As of November 20, 2026, the supplied data showed a price-to-earnings ratio of 40.24 and a price-to-book ratio of 3.34, alongside a valuation score of one out of five labelled overvalued. Another market commentary cited a P/E near 43.9 and P/B of 3.60 against return on equity of 8.95%, underscoring the concern that the share price embeds sizeable expectations.
Got a follow-up? Ask IRIS
What growth is expected from Jio Platforms through FY29?
Jio Platforms is forecast by Elara Securities to deliver revenue, EBITDA and adjusted profit growth through FY29, with profit growing faster than sales. Elara's estimates imply revenue CAGR of 13%, EBITDA CAGR of 16% and adjusted PAT CAGR of 23% between FY26 and FY29E.
Margin expansion is central to that projection. Consolidated revenue is estimated to rise from ₹1,468,853 million in FY26 to ₹2,100,842 million in FY29E, while EBITDA margin is projected to increase from 50.0% to 53.8%. A separate forecast expects average revenue growth of 12% annually over the next three years, above the 6.6% forecast for Asia's wireless telecom industry.
What could change the Jio Platforms stock outlook?
Jio Platforms' outlook could improve if tariff increases lift average revenue per user, 5G monetisation advances and free cash flow continues to improve. The supplied discussion identifies 300 million 5G subscribers, EBITDA margin above 51%, rising ARPU and possible tariff hikes as factors supporting the investment case.
The risks are equally clear. The Indian telecom market remains highly competitive, network expansion requires substantial capital investment, and the company must prove it can monetise its broad digital ecosystem efficiently. Its leadership in subscriber base and revenue market share provides scale, but investors will still need evidence of pricing discipline, subscriber stickiness and digital-service execution.
Conclusion
Jio Platforms combines market leadership, a large free-cash-flow base and forecasts for stronger margins and profit growth. However, the available analyst targets suggest limited immediate upside from around ₹1,395.90, while P/E and P/B measures indicate that investors are already paying for a meaningful share of the expected growth.
The next focus is whether tariff actions, ARPU gains and 5G monetisation translate into the projected FY26-FY29E revenue and margin gains. Investors should also watch how the share price performs after its October 28, 2026 market debut, particularly because it already stands above two of the published brokerage targets.