










Jubilant Agri EBIT falls 87% as rainfall curbs fertiliser demand
Key highlights
- Jubilant’s Agri Products EBIT fell 87% year on year to Rs 3.6 crore in Q2 FY27.
- Agri Products net sales declined 7% to Rs 206.8 crore in Q2 FY27.
- Jubilant reported a seasonal rainfall deficit of more than 12% and delayed sowing of major crops.
- H1 FY27 Agri Products EBIT fell 76% to Rs 10.1 crore on net sales of Rs 348.5 crore.
powered by IRIS
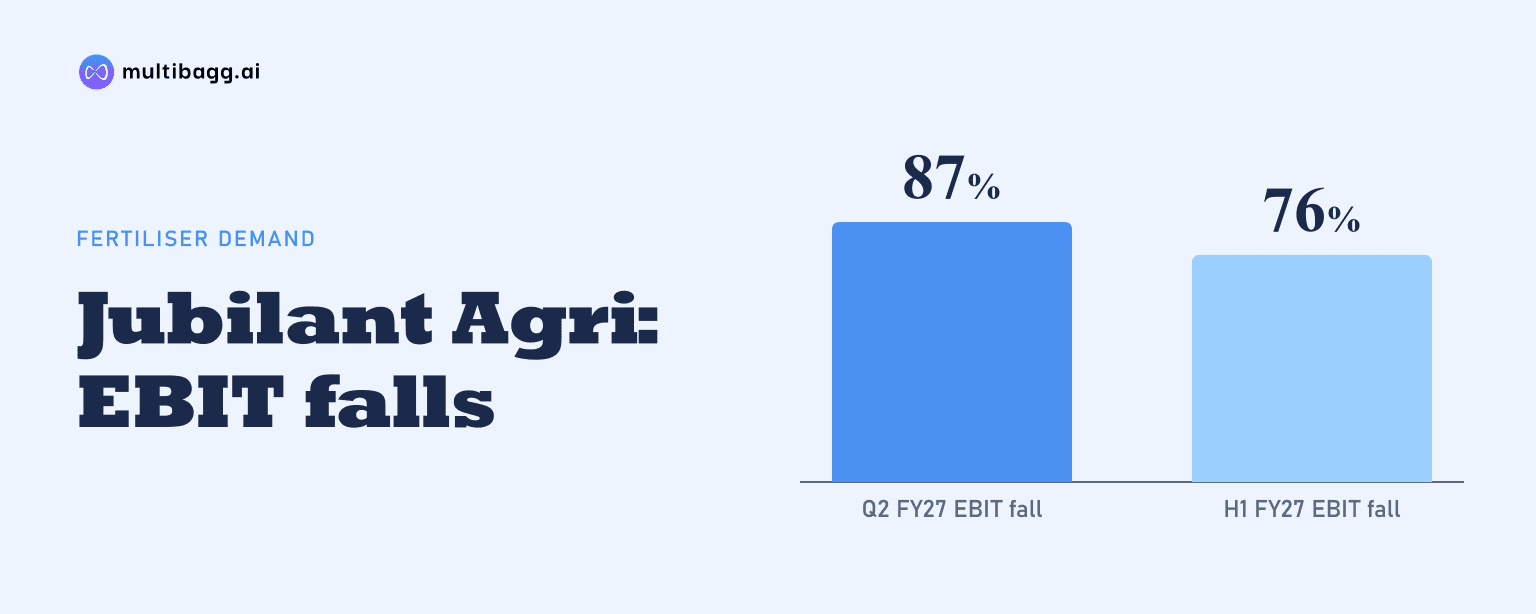
Jubilant Agri & Consumer Products reported an 87% year-on-year fall in Agri Products segment EBIT to Rs 3.6 crore in Q2 FY27, as management linked subdued fertiliser demand to El Niño conditions, a rainfall deficit exceeding 12%, delayed sowing and erratic rainfall. Segment net sales fell 7% to Rs 206.8 crore.
Know Jubilant Agri & Consumer Products inside out
Results, valuation, peers and who's buying, in one view.
Why did Jubilant Agri Products EBIT fall 87% in Q2 FY27?
Jubilant’s Agri Products EBIT fell to Rs 3.6 crore in Q2 FY27 from Rs 28.9 crore in Q2 FY26, while net sales declined to Rs 206.8 crore from Rs 223.2 crore. The 87% EBIT decline was substantially larger than the 7% reduction in sales, reflecting the weather-led demand and supply conditions described by management.
Management said El Niño conditions during the year significantly affected India’s agricultural environment and resulted in subdued fertiliser demand. The season had an overall rainfall deficit of more than 12%, while delayed sowing and erratic rainfall affected the timely planting of major crops and lowered fertiliser application.
The quarterly decline followed a return to annual profitability in FY26. Agri Products recorded segment EBIT of Rs 46.9 crore in FY26, compared with losses of Rs 5.7 crore in FY25 and Rs 19.4 crore in FY24, showing that Q2 FY27 remained profitable but was materially below the prior-year quarter.
How did rainfall and delayed sowing reduce fertiliser demand?
Jubilant said the more-than-12% rainfall deficit, delayed sowing and uneven rainfall reduced fertiliser application for major crops in Q2 FY27. Farmers’ disrupted planting schedules reduced the immediate requirement for fertiliser, contributing to the segment’s Rs 16.4 crore year-on-year fall in quarterly net sales.
Lower fertiliser demand also slowed inventory liquidation, according to management, increasing working-capital requirements as stock remained deployed for longer. Jubilant did not disclose the value of inventory or working capital, but said liquidation of stock in key operating regions would be a focus for unlocking working capital.
The demand issue did not apply equally to every activity within the segment. Agri Products covers crop nutrition, crop growth regulator and crop protection, with products sold under the Ramban umbrella brand, while Jubilant said the Agri Nutrient business delivered strong double-digit growth through portfolio expansion and wider market coverage.
Jubilant has entered eight new states over the past two years and operates two manufacturing locations. Despite those disclosed expansion steps and Agri Nutrient growth, total Agri Products sales fell to Rs 206.8 crore in Q2 FY27, indicating that weaker fertiliser conditions outweighed growth in that business line.
What did supply disruption mean for margins and working capital?
Jubilant said supply-chain disruption affected the availability of key raw materials in Q2 FY27, putting pressure on gross margins and working-capital deployment. This was distinct from the demand effect: lower fertiliser application slowed sales and inventory turnover, while raw-material disruption affected supply conditions and costs.
The disclosed numbers show the combined operating effect without separating each cause. Agri Products revenue declined by Rs 16.4 crore year on year, but segment EBIT fell by Rs 25.3 crore, from Rs 28.9 crore to Rs 3.6 crore; the presentation does not quantify the individual impact of raw-material supply, inventory holding or reduced demand.
At the consolidated level, Jubilant reported revenue from operations of Rs 592.1 crore in Q2 FY27, up 15% from Rs 513 crore in Q2 FY26. Earnings before interest, tax, depreciation and amortisation, or EBITDA, fell 56% to Rs 28.4 crore, and EBITDA margin declined to 4.8% from 12.5% a year earlier.
The Adhesives segment provided a contrast with the agri result. Adhesives net sales rose 20% to Rs 153.2 crore and segment EBIT increased 9% to Rs 12.2 crore in Q2 FY27, whereas Agri Products recorded a 7% sales decline and an 87% EBIT decline.
Got a follow-up? Ask IRIS
How did the first half compare with the second quarter?
Jubilant’s Agri Products net sales fell 5% year on year to Rs 348.5 crore in H1 FY27, while segment EBIT dropped 76% to Rs 10.1 crore. In H1 FY26, the segment reported net sales of Rs 365.7 crore and EBIT of Rs 42.4 crore, showing that the earnings pressure extended across the six-month period.
Q2 FY27 sales of Rs 206.8 crore were higher than Q1 FY27 sales of Rs 141.7 crore, but Q2 EBIT of Rs 3.6 crore was below Q1 EBIT of Rs 6.4 crore. The sequential comparison indicates that higher quarterly sales did not offset the Q2 demand, margin and working-capital pressures identified by management.
Over the preceding three financial years, Agri Products revenue rose from Rs 295.6 crore in FY24 to Rs 456.8 crore in FY25 and Rs 692.3 crore in FY26. EBIT moved from losses in FY24 and FY25 to a Rs 46.9 crore profit in FY26, placing the Q2 and H1 FY27 deterioration against a recently improved earnings base.
What is Jubilant’s outlook for demand and input costs?
Jubilant expects fertiliser demand to remain subdued in the near term and plans to liquidate stock in key operating regions to unlock working capital. Management did not provide a target for inventory reduction or a timetable for demand normalisation following the Q2 FY27 rainfall and sowing disruption.
Management expects the Agri Nutrient business to grow in double digits, following the strong double-digit growth it reported in Q2 FY27. That expectation relates to Agri Nutrient, supported by portfolio expansion and wider market coverage, rather than representing a numerical forecast for the full Agri Products segment.
Jubilant also expects input costs to remain under pressure amid ongoing geopolitical uncertainty. The presentation does not identify specific raw materials, expected cost movements or price actions for Agri Products, while its stated operating response is stock liquidation alongside continued Agri Nutrient portfolio and market expansion.
Conclusion
Jubilant’s Q2 FY27 Agri Products results show the combined earnings effect of weather-disrupted fertiliser demand and raw-material supply conditions. A rainfall deficit exceeding 12%, delayed sowing and erratic rainfall reduced fertiliser application, while supply disruption affected gross margins and working-capital deployment, contributing to a 7% sales decline and an 87% EBIT fall.
The next disclosed issues to watch are the planned liquidation of stock in key operating regions, the duration of subdued demand and input-cost pressure from geopolitical uncertainty. Management expects double-digit growth in Agri Nutrient, making its expansion relative to the wider Agri Products segment central to subsequent results.