










Jubilant Performance Polymers sales rise 33%, EBIT falls 33%
Key highlights
- Jubilant's Performance Polymers & Chemicals Q2 FY27 net sales rose 33% to Rs 385.3 crore.
- Q2 FY27 segment EBIT fell 33% year on year to Rs 26.2 crore from Rs 38.8 crore.
- H1 FY27 sales increased 30% to Rs 766.8 crore, while segment EBIT declined 2% to Rs 91.5 crore.
- A Rs 50 crore brownfield expansion proposes 30,000 metric tonnes per annum of added capacity, with SBR Latex due by mid-Q4 FY27.
powered by IRIS
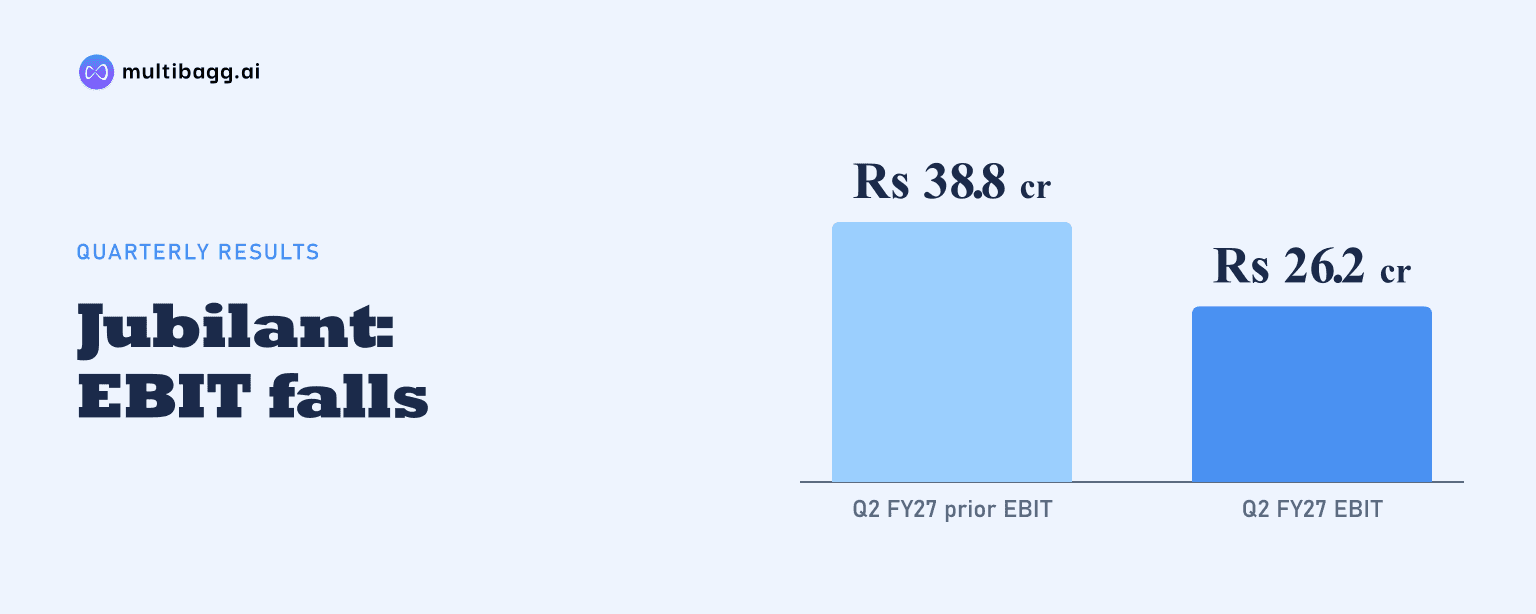
Jubilant Agri & Consumer Products reported 33% year-on-year growth in Performance Polymers & Chemicals net sales to Rs 385.3 crore in Q2 FY27, while segment EBIT fell 33% to Rs 26.2 crore. Higher input costs and continued marketing spending affected gross margins, while geopolitical disruptions and logistics challenges affected export volumes.
Know Jubilant Agri & Consumer Products inside out
Results, valuation, peers and who's buying, in one view.
Why did Jubilant's Q2 sales and EBIT diverge?
Jubilant's Q2 FY27 sales and EBIT diverged because domestic demand and market-share gains lifted revenue, while input-cost increases and marketing spending reduced gross margins. Performance Polymers & Chemicals net sales increased from Rs 289.7 crore in Q2 FY26 to Rs 385.3 crore in Q2 FY27, a rise of Rs 95.6 crore. Segment EBIT, however, declined from Rs 38.8 crore to Rs 26.2 crore over the same comparison.
The Q2 FY27 figures indicate that earnings did not keep pace with revenue growth during the quarter. Segment EBIT was about 6.8% of net sales in Q2 FY27, compared with about 13.4% in Q2 FY26, based on the disclosed figures. The presentation attributes gross-margin pressure to continued marketing initiatives and increased input costs, while describing domestic demand as healthy.
How did Jubilant perform in the first half of FY27?
Jubilant delivered 30% Performance Polymers & Chemicals sales growth in H1 FY27, while segment EBIT was 2% lower than a year earlier. H1 FY27 net sales reached Rs 766.8 crore, compared with Rs 589.2 crore in H1 FY26, whereas segment EBIT was Rs 91.5 crore compared with Rs 93.2 crore. The half-year result therefore retained revenue growth but showed lower earnings than the prior-year period.
The H1 comparison was less severe than the Q2 comparison because Q1 FY27 segment EBIT was Rs 65.4 crore on revenue of Rs 381.5 crore. In Q2 FY27, revenue rose slightly sequentially to Rs 385.3 crore, but segment EBIT fell to Rs 26.2 crore. The Rs 39.2 crore sequential decline in segment EBIT came despite a Rs 3.8 crore increase in sales.
The business had also expanded before FY27. Segment revenue increased from Rs 957.7 crore in FY24 to Rs 1,104.2 crore in FY25 and Rs 1,198.8 crore in FY26. Segment EBIT rose from Rs 134.7 crore in FY24 to Rs 165 crore in FY25 and Rs 166.3 crore in FY26, meaning the Q2 FY27 decline followed two years of reported annual revenue and EBIT growth.
Got a follow-up? Ask IRIS
Which parts of Jubilant's portfolio were affected in Q2 FY27?
Jubilant's Performance Polymers & Chemicals portfolio includes consumer products, food polymers, acid and latex. Consumer products include adhesives and wood finishes, while latex products include VP Latex, SBR Latex and NBR Latex. The food-polymers range includes Solid Poly Vinyl Acetate, and Jubilant said it gained SBR Latex market share in key accounts during Q2 FY27.
Domestic demand remained healthy in Q2 FY27, but export volumes were affected in key international markets by geopolitical disruptions and logistics challenges, according to the presentation. The sales increase to Rs 385.3 crore was therefore reported alongside export-volume disruption. The presentation does not disclose the domestic-versus-export revenue split or quantify the reduction in export volumes.
Adhesives, a consumer-products category within the broader portfolio, recorded a different Q2 pattern. Adhesives revenue increased 20% year on year to Rs 153.2 crore in Q2 FY27, and its segment EBIT increased 9% to Rs 12.2 crore. This contrasts with the broader Performance Polymers & Chemicals business, where sales grew 33% but segment EBIT declined 33%.
What is Jubilant planning to address margin pressure?
Jubilant said pricing actions in Q2 and Q3 are expected to progressively flow through from Q3 onward because of a lag effect, which management expects to improve gross margins. The company also cited productivity-improvement initiatives and stabilising input costs as factors expected to support continued growth momentum. These are management expectations rather than reported Q2 FY27 outcomes.
Management cautioned that raw-material costs and supply-chain disruption may continue to affect gross margin in the short term. It also said export demand could remain volatile amid geopolitical tensions and logistics-related disruptions in key international markets. The Q2 FY27 contrast was between healthy domestic demand and uncertainty around exports and the input-cost base.
Jubilant is also adding capacity at its Vadodara site through a Rs 50 crore brownfield expansion. The programme proposes 30,000 metric tonnes per annum of combined additional capacity. Phase 1 for adhesives began commercial production in Q1 FY27, while the new SBR Latex capacity is scheduled for completion by the middle of Q4 FY27.
Conclusion
Jubilant's Q2 FY27 Performance Polymers & Chemicals result shows revenue growth running ahead of earnings growth: sales rose 33% to Rs 385.3 crore, while segment EBIT fell 33% to Rs 26.2 crore. Domestic demand and SBR Latex market-share gains supported sales, but higher inputs and marketing expenditure affected gross margins as export volumes faced geopolitical and logistics disruption.
The next developments to watch are management's expected Q3 flow-through from pricing actions, the course of raw-material and supply-chain costs, and export-demand volatility in affected international markets. The other disclosed milestone is completion of the new SBR Latex capacity by the middle of Q4 FY27 within the Rs 50 crore brownfield expansion proposing 30,000 metric tonnes per annum of additional capacity.