










Kedia Construction restates comparatives from April 2024
Key highlights
- Kedia Construction restated comparative financial information from April 1, 2024 under the Kirti Investments amalgamation scheme.
- The National Company Law Tribunal, Mumbai Bench approved the scheme on April 6, 2026.
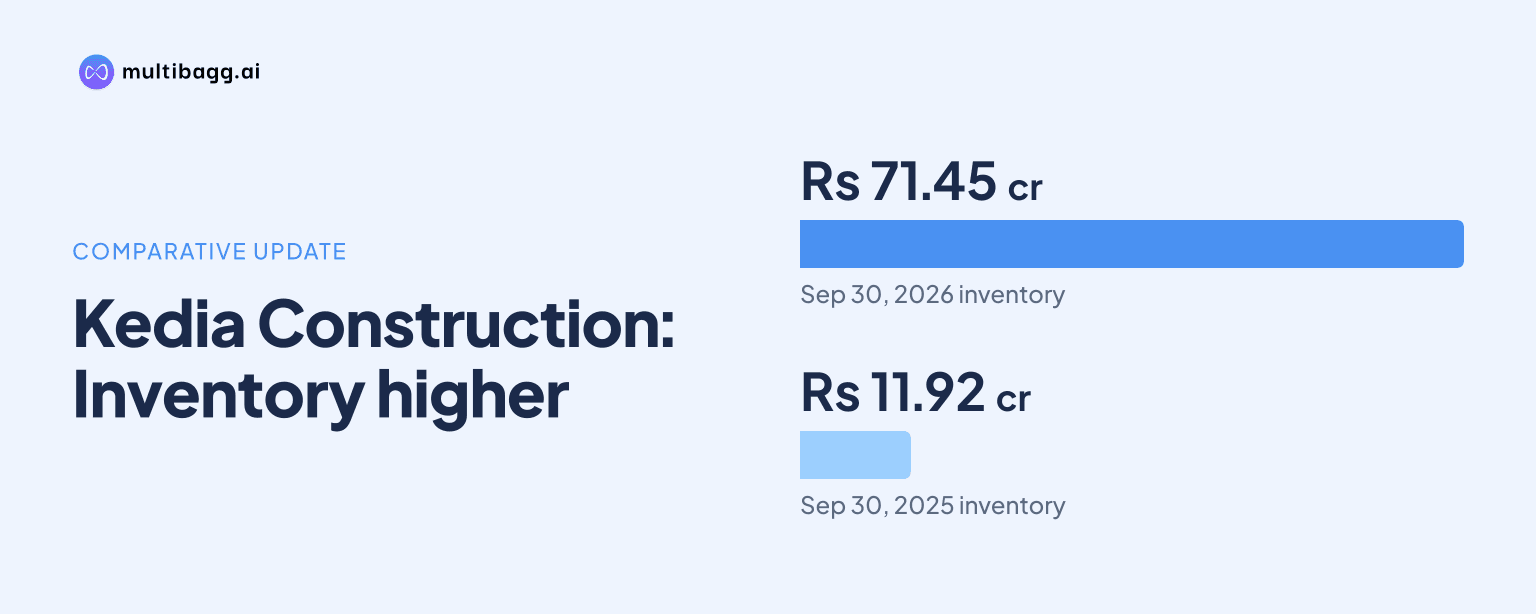
- Inventory was Rs 71.45 crore at September 30, 2026, versus Rs 11.92 crore in the restated September 2025 column.
- Ridge Road Property is carried in inventory at Rs 112.99 lakh and remains under litigation with LIC of India.
powered by IRIS
Kedia Construction Company Limited has restated comparative financial information from April 1, 2024 after the National Company Law Tribunal, Mumbai Bench approved its amalgamation with Kirti Investments Limited on April 6, 2026. The recast changes the basis of comparison for the unaudited quarter and half year ended September 30, 2026.
Know Kedia Construction Company inside out
Results, valuation, peers and who's buying, in one view.
Why did Kedia Construction restate its comparative financial information?
Kedia Construction restated prior-period information because the approved Scheme of Arrangement and Amalgamation set April 1, 2024 as its appointed date. The auditor’s November 3, 2026 limited-review report says the scheme covered the amalgamation of Kirti Investments, the transferor company, with Kedia Construction, the transferee company.
The scheme also provided for a reduction of Kedia Construction’s share capital, according to the auditor’s emphasis-of-matter disclosure. The filing does not disclose the number of shares affected, the amount of capital reduced, an exchange ratio, or a monetary value assigned to the amalgamation. It therefore establishes the reason and starting date for the recast, rather than a quantified merger-adjustment bridge.
The auditor said comparative financial information in the accompanying statement was restated from the beginning of the preceding period, April 1, 2024. This means the September 30, 2026 results should be compared with the recast figures shown in the statement, rather than mechanically with earlier financial presentations that may have used a different reporting perimeter.
The tribunal approval date and appointed date are different. The National Company Law Tribunal approved the scheme on April 6, 2026, while April 1, 2024 is the effective accounting date stated in the scheme. Kedia Construction’s board approved the quarter and half-year results on November 3, 2026, nearly seven months after the tribunal order.
Which financial periods are affected by the Kedia Construction recast?
Kedia Construction’s filing identifies April 1, 2024 as the beginning of the comparative recast period. The results submitted to BSE cover the quarter ended September 30, 2026 and the six-month period from April 1, 2026 to September 30, 2026, with comparative information presented alongside them.
The company’s financial-results notes separately say prior-period figures have been regrouped or recast wherever necessary to conform with the current-period grouping. That general presentation note sits alongside the specific auditor disclosure that the comparative information was restated from April 1, 2024 because of the Kirti Investments scheme.
Kedia Construction reported that it is engaged in the construction business and has no separate reportable segment under Indian Accounting Standard 108, or Ind AS 108. Consequently, the filing does not provide a construction-versus-investment or transferor-versus-transferee segment bridge for the restated figures at September 30, 2026.
The announcement also does not state a cumulative impact of the merger on revenue, profit, assets, liabilities or equity. That omission matters because a restated comparative can reflect the scheme’s accounting treatment without revealing, in this filing, how much of each balance or period result arose from Kirti Investments, eliminations, regrouping, or other adjustments.
Got a follow-up? Ask IRIS
How does the restated presentation affect inventory comparisons?
Kedia Construction’s assets-and-liabilities statement displays inventory of Rs 71.45 crore at September 30, 2026. It also shows a September 30, 2025 restated inventory figure of Rs 11.92 crore and another September 2025 comparative inventory figure of Rs 4.24 crore, demonstrating that the two historical presentations are not on the same stated basis.
The Rs 11.92 crore restated September 2025 figure is Rs 7.68 crore above the other Rs 4.24 crore September 2025 figure displayed in the statement. The filing does not allocate that difference among acquired balances, merger accounting entries, reclassifications, or any other mechanism, so it does not support a precise explanation for the gap.
At September 30, 2026, inventory of Rs 71.45 crore was substantially above the restated Rs 11.92 crore shown for September 30, 2025. This is a reported balance-sheet comparison, not evidence that the full increase resulted from the amalgamation, because the company provides no inventory movement analysis separating the scheme’s impact from changes during the period.
The filing also shows property, plant and equipment of Rs 0.32 lakh at both September 30, 2026 and in the restated September 30, 2025 column. Non-current investments were Rs 10.99 lakh in each of those two columns, illustrating that not every disclosed line item changed between the current and restated comparative presentations.
What did the auditor say about the restatement and property litigation?
Kedia Construction’s statutory auditor issued a limited-review report dated November 3, 2026, not a full audit opinion. The report says the review was conducted under Standard on Review Engagements 2410 and provides moderate assurance through inquiries and analytical procedures, which is less assurance than an audit.
Based on its review, the auditor said nothing had come to its attention that caused it to believe the unaudited standalone results for the quarter ended September 30, 2026 and the April 1 to September 30, 2026 period were materially misstated or inadequately disclosed under the applicable requirements. The auditor did not modify its conclusion for the amalgamation restatement.
The same report includes an emphasis of matter on litigation involving Ridge Road Property, carried as inventory at Rs 112.99 lakh. Kedia Construction and a group company have pending litigation against LIC of India concerning that property, and the company has not made a provision for diminution in value.
Kedia Construction says the Ridge Road matter is sub judice, meaning it remains before a court. The auditor did not modify its conclusion for this matter either, but the filing gives no expected resolution date, possible settlement amount, or quantified downside if the litigation outcome differs from the carrying value of Rs 112.99 lakh.
Conclusion
Kedia Construction’s September 2026 results use recast comparative information beginning April 1, 2024 because of the Kirti Investments amalgamation approved on April 6, 2026. The separately displayed September 2025 inventory figures of Rs 11.92 crore on a restated basis and Rs 4.24 crore in the other comparative column show why historical comparisons need to use the stated recast basis.
What to watch next is Kedia Construction’s subsequent financial reporting for additional detail on the scheme’s accounting effects, particularly as the November 3, 2026 filing does not provide a quantified merger bridge. The unresolved Ridge Road Property litigation is also material to monitor because the inventory carrying amount is Rs 112.99 lakh and no diminution provision has been recorded.