










KIMS approves merger of zero-turnover hospital subsidiary
Key highlights
- KIMS approved the amalgamation of KIMS Hospitals on November 4, 2026.
- KIMS Hospitals reported nil turnover and a Rs 50 lakh loss after tax for the year ended March 31, 2026.
- KIMS reported Rs 1,701.5 crore of turnover and Rs 260.7 crore of profit after tax for the year ended March 31, 2026.
- The scheme involves no cash consideration, no new KIMS shares and no change in KIMS's shareholding pattern.
powered by IRIS
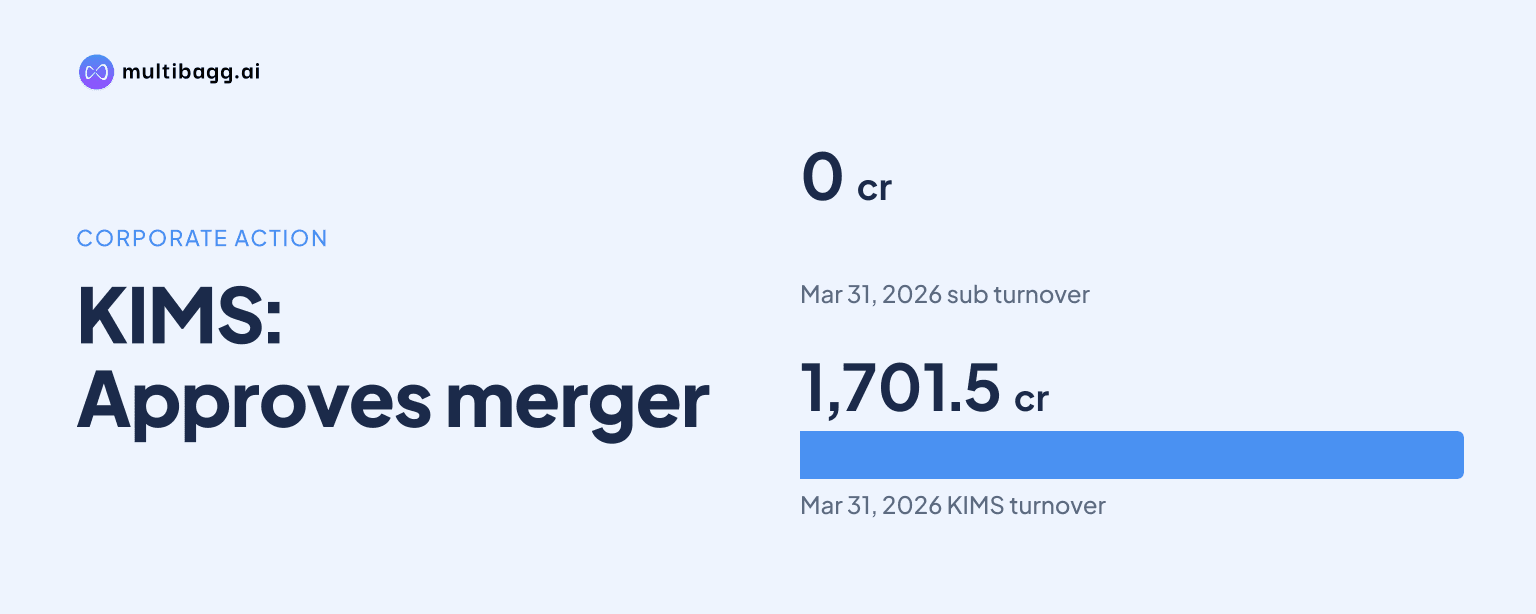
Krishna Institute of Medical Sciences Limited approved the merger of wholly owned subsidiary KIMS Hospitals Private Limited into KIMS on November 4, 2026, after KIMS Hospitals reported nil turnover and a Rs 50 lakh profit-after-tax loss for the year ended March 31, 2026. KIMS said the scheme requires neither cash consideration nor new shares.
Know Krishna Institute of Medical Sciences inside out
Results, valuation, peers and who's buying, in one view.
What did KIMS approve on November 4, 2026?
KIMS approved a scheme of amalgamation under which KIMS Hospitals will merge into KIMS, with the subsidiary designated as the transferor company and KIMS as the transferee company. The board approved the scheme at its November 4, 2026 meeting following a recommendation from the audit committee, under the Companies Act, 2013 and other applicable laws.
The November 4 disclosure was made under Regulation 30 of the Securities and Exchange Board of India (SEBI) Listing Obligations and Disclosure Requirements Regulations, 2015. KIMS notified the Bombay Stock Exchange, where its scrip code is 543308, and the National Stock Exchange, where its trading symbol is KIMS; the International Securities Identification Number is INE967H01025.
The transaction is an internal reorganisation because KIMS already owns 100% of KIMS Hospitals. Both entities are engaged in healthcare activities, according to the filing, so the scheme combines a wholly owned healthcare subsidiary with its holding company rather than adding a disclosed new business segment.
Why is KIMS merging KIMS Hospitals into the parent?
KIMS said the merger is intended to simplify the group corporate structure and eliminate multiple legal entities. Since both KIMS and KIMS Hospitals operate in healthcare, the stated plan is to replace their separate parent-subsidiary legal structure with a unified operating and management framework following implementation of the amalgamation.
Management cited operational and administrative efficiencies from pooling resources and management functions. KIMS also listed focused management and unified decision-making among the scheme's intended outcomes, although the November 4, 2026 announcement did not provide a completion date or a quantified operational-efficiency target.
The filing further identified asset utilisation, lower statutory compliances and cost savings as mechanisms behind the proposed merger. These are management-stated objectives rather than forecast financial results: KIMS did not disclose a rupee savings target, expense-reduction estimate or timetable for achieving the stated cost benefits.
KIMS also said the scheme is intended to strengthen its consolidated financial position and enhance shareholder value. The disclosure does not provide pro forma turnover, profit after tax, assets, liabilities or a post-merger balance sheet, leaving the financial effect beyond removal of KIMS Hospitals as a separate legal entity unspecified.
Got a follow-up? Ask IRIS
What do KIMS Hospitals' financial figures show?
KIMS Hospitals reported nil turnover and a Rs 50 lakh loss after tax for the year ended March 31, 2026, while KIMS reported Rs 1,701.5 crore of turnover and Rs 260.7 crore of profit after tax in the same period. The disclosed figures show no reported revenue at the subsidiary and a profitable parent operation during the same reporting period.
The comparison shows a Rs 1,701.5 crore turnover difference between KIMS and KIMS Hospitals for the year ended March 31, 2026. KIMS Hospitals recorded a Rs 50 lakh loss despite nil turnover, but the filing does not explain its expense base, the source of the loss or why it reported no turnover.
KIMS Hospitals has paid-up capital of 6,59,99,999 equity shares with a face value of Rs 10 each, amounting to Rs 65.999999 crore. KIMS has paid-up capital of 42,00,06,484 equity shares with a face value of Rs 2 each, amounting to Rs 84.0012968 crore, according to the annexure to the November 4 disclosure.
The paid-up-capital amounts describe the two legal entities but do not establish a share-exchange value for KIMS investors. KIMS already owns the subsidiary's 6,59,99,999 shares, and the announced scheme provides for neither an exchange ratio nor the issue of additional KIMS shares.
Will the merger change KIMS shareholders' holdings or require payment?
KIMS said the merger will involve no cash consideration and no issue of new shares because KIMS Hospitals is wholly owned by KIMS. The company also stated that KIMS's shareholding pattern will remain unchanged, indicating no disclosed dilution or ownership change in the listed holding company from this scheme.
The filing classifies the transaction as a related-party transaction because it is between a holding company and its wholly owned subsidiary. KIMS said the transaction is exempt under Regulation 23(5)(b) of the SEBI Listing Obligations and Disclosure Requirements Regulations, 2015, which applies to the disclosed holding-company and wholly owned-subsidiary arrangement.
There is no cash outflow, share-swap ratio or payment to external owners disclosed in the November 4, 2026 filing. KIMS marked changes in its shareholding pattern as not applicable, consistent with the 100% ownership of KIMS Hospitals and the absence of new KIMS shares under the scheme.
KIMS disclosed board approval and the principal transaction terms, but it did not state a legal completion date or identify subsequent approval milestones. The two-page filing therefore confirms the board's November 4, 2026 decision while leaving the timing of completion unresolved.
Conclusion
The approved scheme would fold KIMS Hospitals, which recorded nil turnover and a Rs 50 lakh loss for the year ended March 31, 2026, into KIMS, which reported Rs 1,701.5 crore in turnover and Rs 260.7 crore in profit after tax. The transaction does not involve cash consideration, new shares or a stated change in KIMS's shareholding pattern.
The next item to watch is progress from board approval to legal implementation, because KIMS did not disclose a completion date, savings target or pro forma financial outcome. Management's plan identifies pooled resources, reduced statutory compliances, asset utilisation and unified decision-making as the mechanisms for the merger, so later disclosures may clarify timing and measurable effects.