










Krishival targets Rs 1,500 crore consolidated revenue by FY29
Key highlights
- Krishival targets Rs 1,500 crore of consolidated revenue in FY29 versus a Rs 290 crore FY26 planning base.
- Ice cream is targeted to contribute 50% to 55% of topline in FY28, up from 31% in FY26.
- The deep-freezer network is targeted to reach 35,000 units in FY28E from 3,732 units in FY25.
- FY26 revenue from operations was Rs 292.67 crore and net profit was Rs 22.20 crore.
powered by IRIS
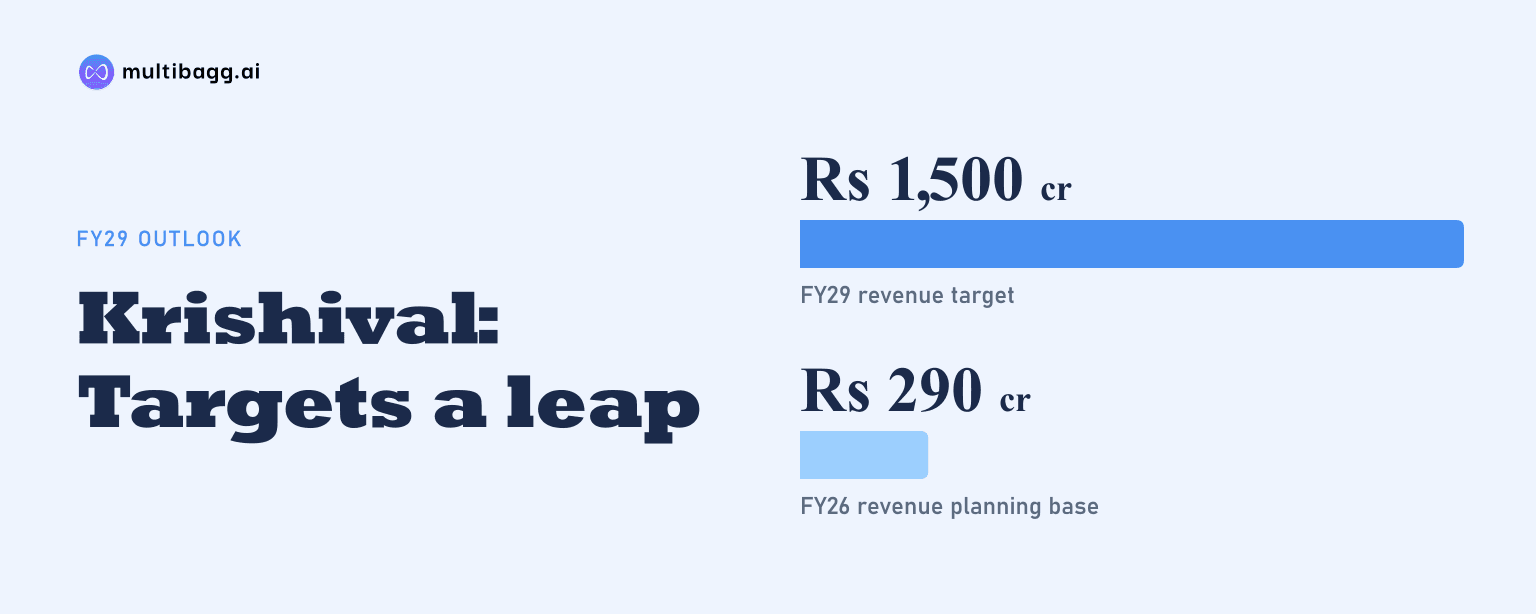
Krishival Nuts targets Rs 1,500 crore of consolidated revenue in FY29, about five times its Rs 290 crore FY26 planning base, under a plan that targets ice cream at 50% to 55% of topline by FY28 and a 35,000-unit deep-freezer network by FY28E.
Know Krishival Foods inside out
Results, valuation, peers and who's buying, in one view.
How does Krishival plan to reach Rs 1,500 crore by FY29?
Krishival plans to use a dual-engine fast-moving consumer goods (FMCG) model, with Krishival Nuts described as the cash generator and Melt N Mellow as the high-growth engine. Management’s Rs 1,500 crore FY29 consolidated-revenue target compares with the Rs 290 crore FY26 planning base and implies compound annual growth of about 73% over three years.
The presentation sets milestones before FY29. For FY27, management targets 50% growth in sales and profit after tax (PAT), while its FY28 objective is for ice cream to account for about 50% to 55% of topline. The plan therefore relies on a substantial shift in category mix as well as growth in the nuts and dry-fruits business.
The Rs 290 crore planning base is close to, but not identical with, Krishival’s reported FY26 financial measures. The consolidated income statement records revenue from operations of Rs 292.67 crore and total income of Rs 304.41 crore for 2025-26. The target slide uses consolidated revenue, while the income statement separates other income of Rs 11.73 crore.
Why is ice cream central to Krishival’s FY29 plan?
Ice cream is central because management targets its share of Krishival topline at about 50% to 55% in FY28, compared with 31% in FY26. Melt N Mellow is identified as the high-growth engine, so meeting the mix target would make ice cream roughly half of consolidated revenue before the FY29 target year.
Melt N Mellow has installed ice-cream capacity of 1,00,000 litres per day, with utilisation described as ramping alongside the freezer rollout. Management targets 100% capacity utilisation in Q1 FY29 and associates that level with revenue potential of about Rs 600 crore. That potential is below the Rs 1,500 crore consolidated target, leaving a substantial contribution required from nuts and other operations.
The stated mechanisms are wider distribution, higher freezer penetration and stronger brand visibility for Melt N Mellow. Management also plans to increase premium and value-added products across both verticals, but it does not disclose a separate ice-cream volume, price or margin target. Its disclosed measures are the revenue mix, litres-per-day capacity and freezer deployment.
How will Krishival expand its freezer network and capacity?
Krishival targets 35,000 deep freezers in FY28E, up from 3,732 in FY25 and 15,490 in FY26. The network is presented as last-mile cold-chain infrastructure for both engines, particularly ice cream. For FY27E, which is management’s estimate for fiscal 2027, the detailed schedule specifies 26,500 units.
In finished nuts, Krishival commissioned 10 metric tonnes per day of capacity in March FY26 and added another 10 metric tonnes per day in Phase 1 during May FY26. Phase 2 targets about 25% utilisation of the additional 10 metric tonnes per day in FY27E. Phase 3 is planned to add 20 metric tonnes per day in FY28E, taking total capacity to 40 metric tonnes per day.
The capacity additions precede the FY29 revenue objective, while freezer rollout is linked by management to full capacity utilisation across both engines. The presentation does not disclose the capital expenditure for the planned 35,000 freezers or 40-metric-tonnes-per-day nuts capacity. It also gives no nuts-facility utilisation target beyond the Phase 2 target of about 25%.
Got a follow-up? Ask IRIS
What distribution plan supports Krishival’s growth target?
Krishival plans to deepen distribution across more than 300 towns and places, focusing on Tier II, Tier III and Tier IV markets. Its channels include modern trade, general trade and quick commerce, with named online partners including Amazon, Blinkit, Zepto, Instamart and Flipkart. The physical freezer network is intended to extend this reach for cold-chain products.
The plan also identifies Singapore, Japan and the United States as three export markets for a stronger export footprint. Krishival lists nuts business-to-business partnerships including Haldiram’s, Meetha, Om Sweets & Snacks and Manak Mewa, and modern-trade partners including Nature’s Basket, Reliance Retail, Metro and Food Square. It does not quantify sales from exports, individual partners or any channel.
Management says it will use integrated sourcing, procurement and global sourcing relationships to support quality, supply security and input-cost management. It also cites higher capacity utilisation and disciplined scale-up as mechanisms for operating leverage. No dated procurement-cost, export-revenue or retail-outlet target is disclosed alongside the more specific freezer-network targets.
What does Krishival’s FY26 financial record show?
Krishival reported FY26 revenue from operations of Rs 292.67 crore, 45% higher than Rs 202.23 crore in FY25. Total income increased 48% to Rs 304.41 crore from Rs 206.31 crore, including other income of Rs 11.73 crore compared with Rs 4.07 crore a year earlier.
Earnings before interest, tax, depreciation and amortisation (EBITDA) rose 55% to Rs 39.07 crore in FY26 from Rs 25.23 crore in FY25. EBITDA margin increased by 87 basis points to 13.35% from 12.48%; one basis point is one-hundredth of a percentage point. Employee benefits expense rose to Rs 11.89 crore from Rs 6.27 crore over the same period.
Net profit increased 64% to Rs 22.20 crore in FY26 from Rs 13.55 crore in FY25, and net profit margin rose to 7.59% from 6.70%. Finance costs increased to Rs 3.12 crore from Rs 1.16 crore, while depreciation and amortisation rose to Rs 7.41 crore from Rs 4.35 crore. The presentation does not provide an FY29 EBITDA, net-profit or margin target.
Conclusion
Krishival’s FY29 plan combines a Rs 1,500 crore consolidated-revenue target with an intended shift toward ice cream, whose share of topline is targeted at 50% to 55% in FY28 from 31% in FY26. The operating build-out includes a deep-freezer network of 35,000 units in FY28E and finished-nuts capacity of 40 metric tonnes per day.
The next disclosed checkpoints are management’s FY27 targets for 50% sales and PAT growth, 26,500 deep freezers and about 25% utilisation of the additional 10-metric-tonnes-per-day nuts capacity. Management also targets 100% utilisation of Melt N Mellow’s 1,00,000-litres-per-day capacity in Q1 FY29, associated with about Rs 600 crore of revenue potential.