










Krishival Caps Nuts Growth at 25%, Targets 15%-16% EBITDA
Key highlights
- Krishival expects nuts growth of 20% to 25% over the next two to three quarters.
- Krishival targets a 15% to 16% nuts EBITDA margin and says EBITDA above 18% is challenging.
- Krishival plans to raise kernel-production capacity from 20 to 40 metric tonnes per day by March 2028.
- Ice cream sales were almost Rs 74 crore in the first six months, nearly three times the prior-year level cited by management.
powered by IRIS
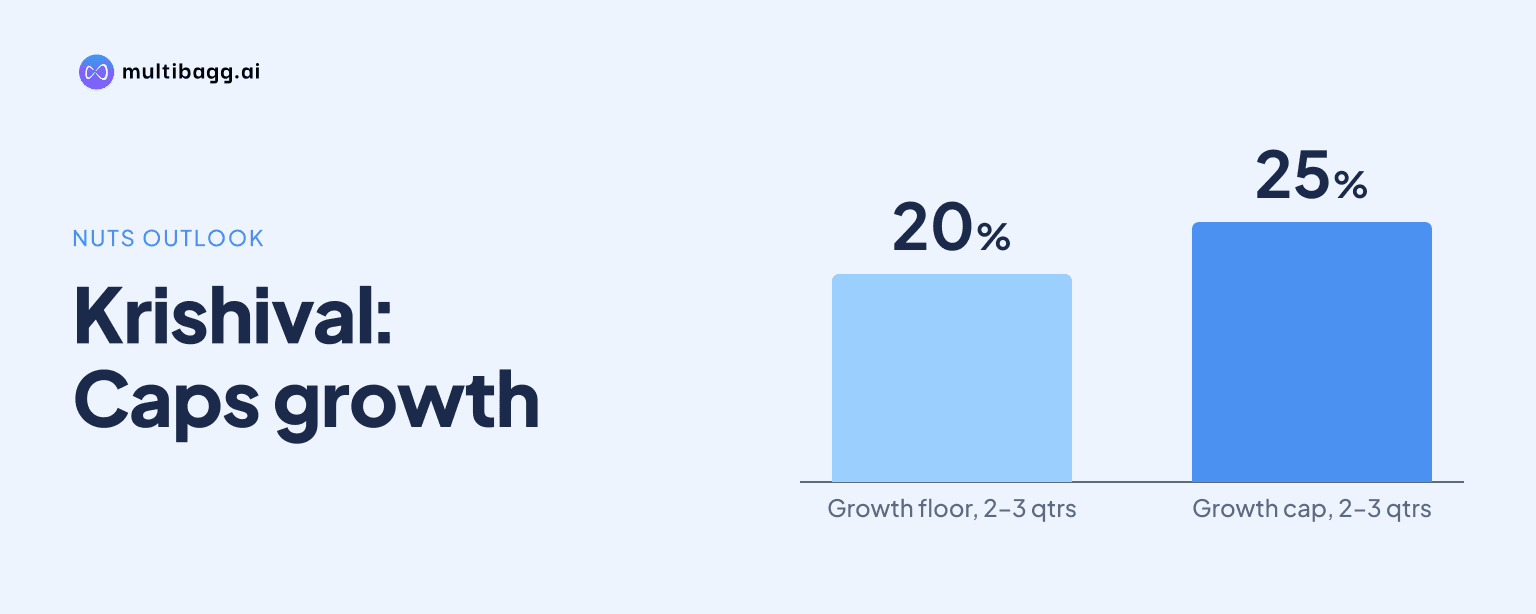
Krishival expects its nuts segment to grow 20% to 25% over the next two to three quarters and targets a 15% to 16% earnings before interest, tax, depreciation and amortisation (EBITDA) margin. Management said nuts EBITDA above 18% is challenging, despite the segment maintaining roughly 14% to 16% for about 1.5 to two years.
Know Krishival Foods inside out
Results, valuation, peers and who's buying, in one view.
What nuts growth does Krishival expect next?
Krishival expects nuts growth of 20% to 25% during the next two to three quarters. Management compared this with growth of 15% to 20% over the previous three or four quarters, which it attributed to cost control, input-price management and distribution tailored to business-to-consumer (B2C) and business-to-business (B2B) channels.
The 20% to 25% outlook is therefore above the 15% to 20% range cited for the past three or four quarters, but it does not assume an immediate acceleration from the planned capacity expansion. Management said profitability would remain central as it increases capacity utilisation in the nuts segment in a staggered manner.
Management said ice cream growth is almost double the nuts segment rate, partly because ice cream is growing from a lower base and partly because of industry dynamics. Krishival described ice cream growth as much higher than nuts growth, while its specific near-term expectation for nuts remains 20% to 25%.
Why is Krishival not projecting faster nuts growth immediately?
Krishival said nuts capacity utilisation will be deployed progressively rather than all at once. The company plans to increase kernel-production capacity from 20 metric tonnes per day to 40 metric tonnes per day by March 2028, while maintaining its stated focus on segment profitability.
The March 2028 capacity plan is paired with wider distribution across India and potential exports. Management said nuts growth could rise beyond current levels in the coming years as capacity utilisation, domestic distribution and export activity develop together, distinguishing that longer-term plan from the next two to three quarters.
The 20-to-40-metric-tonnes-per-day expansion is a capacity target, not a disclosed near-term sales forecast. Management's stated nuts growth expectation remains 20% to 25%, whereas the higher percentage growth in ice cream reflects both its lower base and industry-related conditions.
What EBITDA margin does Krishival view as sustainable in nuts?
Krishival identifies a 15% to 16% EBITDA margin as its target, or ideal, range for nuts. Management said EBITDA beyond 18% in the nuts business is very challenging and described performance above its 15% to 16% target as a bonus rather than a base-case outcome.
Management said the nuts segment has maintained EBITDA of almost 14% to 16% for about 1.5 to two years. It attributed that range to sourcing and supply-chain management, including planned purchases of raw materials and ingredients used in the nuts and dry-fruit segment.
Inventory rose during the quarter as Krishival built stock to manage raw-material availability and costs, according to management. It cited El Niño effects and inflationary pressure as factors behind the build-up, saying supply-chain management helps it maintain both product availability and cost control.
Got a follow-up? Ask IRIS
How do Krishival’s sales channels affect nuts profitability?
Krishival said its B2B nuts business is limited to mithai, or Indian-sweets, ingredient partners rather than general reseller channels. Management cited Prashant Corner, Meetha by Radisson, Haldiram Delhi and Home Sweet Gurgaon as examples, saying good kernels supplied to these customers earn rates that support profitability comparable with B2C.
Management contrasted those ingredient partnerships with supplying resellers, which it said can become a commodity-led activity. This channel choice is part of Krishival's approach to keeping B2B profitability broadly similar to B2C profitability while targeting a 15% to 16% EBITDA margin in nuts.
B2C channels also became a bigger part of the nuts mix during the first six months. Management said e-commerce and modern trade accounted for 20% of the B2C mix in that period, compared with 5% to 7% in the last financial year, a change it said contributed to higher receivables.
How do ice cream results and receivables compare with nuts?
Krishival said its ice cream EBITDA was almost 16% in the reported quarter and 10.25% in the first quarter, above management's 8% target. Management attributed the result to extra caution in cost management, but said its 15% to 16% ice cream margin target applies when optimum capacity utilisation is reached in financial year 2029.
The ice cream result does not alter the 15% to 16% target stated for nuts. Management said it was EBITDA-positive in ice cream from March 2026, whereas it had not achieved positive EBITDA in that business until the last financial year, and it expects ice cream growth to remain almost double the nuts rate.
Management said receivables rose partly because nearly Rs 55 crore of quarterly sales of about Rs 85 crore occurred in September. July and August are slack months for ice cream, while September sales increased in both ice cream and nuts ahead of the September-October festive period for nuts and dry fruits.
Ice cream sales were almost Rs 74 crore in the first six months, nearly three times the prior-year ice cream sales cited by management. Krishival said that higher sales level, alongside the rise in B2C channels, increased receivables as it managed a larger distribution ecosystem, while 31 December receivables are expected to be minimal.
Conclusion
Krishival has set a measured near-term framework for nuts: 20% to 25% growth over the next two to three quarters and a 15% to 16% EBITDA target. The company is expanding kernel-production capacity from 20 to 40 metric tonnes per day, but management does not present that plan as grounds for assuming margins above 18% or immediate growth beyond its stated range.
The next point to watch is the staggered ramp-up toward 40 metric tonnes per day by March 2028, alongside distribution expansion in India and possible exports. Management also targets optimum ice cream capacity utilisation in financial year 2029, while the seasonal concentration of sales, including nearly Rs 55 crore in September, may continue to affect reported receivables at interim period ends.