










Laser Power order book grows 49.3% as capital days reach 129
Key highlights
- Laser Power’s FY26 order book was Rs 3,243.4 crore, up 49.3% from Rs 2,172.7 crore in FY24.
- Manufacturing pending orders rose to Rs 1,668.9 crore in FY26 from Rs 543.8 crore in FY24.
- Working capital reached Rs 1,020.7 crore and working-capital days increased to 129 in FY26.
- FY26 EBITDA margin was 13.0%, up from 9.6% in FY25, while revenue declined to Rs 2,326.1 crore.
powered by IRIS
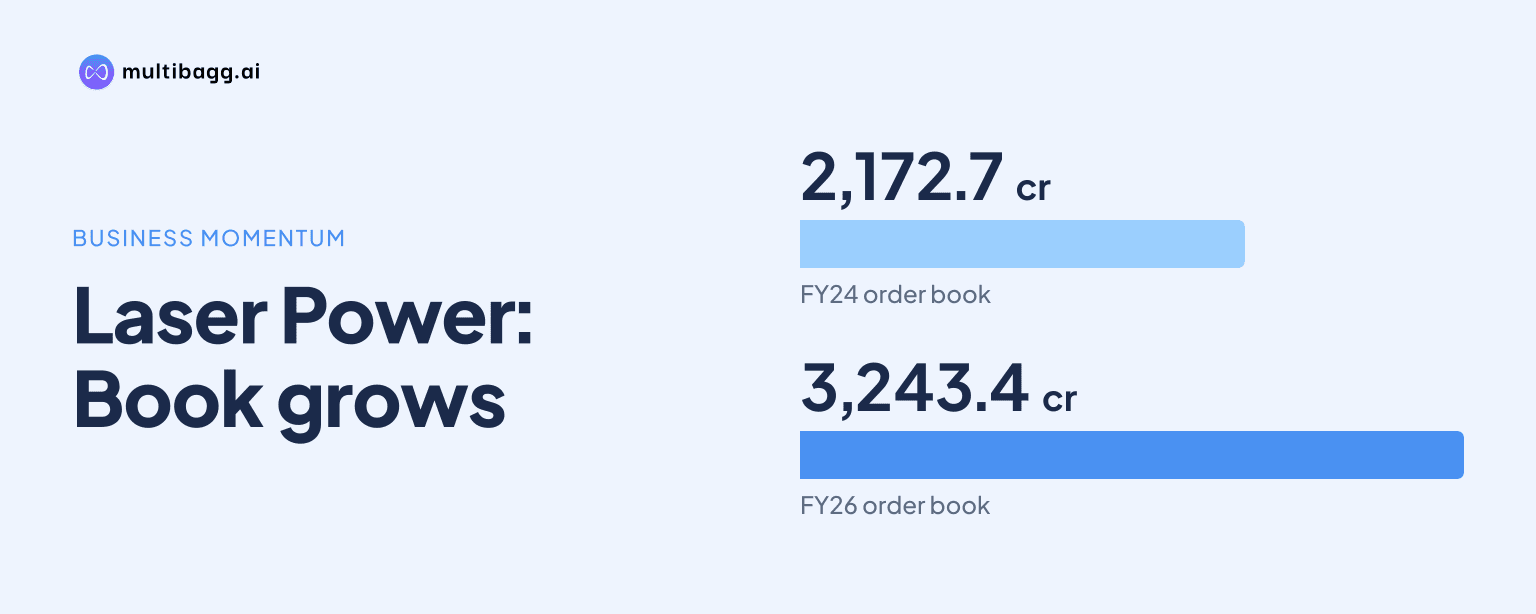
Laser Power & Infra reported a Rs 3,243.4 crore order book at the end of FY26, up 49.3% from FY24, while working-capital days increased to 129 from 86. The increase in pending manufacturing orders to Rs 1,668.9 crore drove the backlog expansion, while the engineering, procurement and construction backlog remained below its FY24 level.
Know Laser Power & Infra inside out
Results, valuation, peers and who's buying, in one view.
How did Laser Power’s order book change through FY26?
Laser Power’s total order book rose to Rs 3,243.4 crore in FY26 from Rs 2,172.7 crore in FY24, as stated in the presentation. It was Rs 2,317.2 crore in FY25, meaning the FY26 increase of Rs 926.2 crore exceeded the Rs 144.5 crore rise recorded in FY25.
Manufacturing pending orders increased by Rs 1,125.1 crore between FY24 and FY26, while EPC pending orders were Rs 54.4 crore lower over the same period. Laser Power defines manufacturing backlog as third-party customer orders, excluding internal EPC orders; the EPC backlog includes cables internally sourced from manufacturing.
The disclosed EPC scope includes high-voltage distribution systems in semi-urban and rural areas, 33/11 kilovolt substations, underground cabling and last-mile connectivity. Laser Power also reported 20 EPC projects awarded across FY24 to FY26, with an aggregate value of Rs 3,159.5 crore including goods and services tax.
What drove Laser Power’s manufacturing order inflow?
Laser Power’s manufacturing order inflow rose in each reported year, reaching Rs 2,123.2 crore in FY26 from Rs 1,354.3 crore in FY24. Pending manufacturing orders grew faster than inflow over that period, reaching Rs 1,668.9 crore in FY26 from Rs 543.8 crore in FY24.
Private-sector manufacturing inflow was the largest FY26 client category at Rs 1,067.3 crore, narrowly above Rs 1,005.3 crore from government customers. Government-sector inflow rose by Rs 532.4 crore from FY24 to FY26, compared with a Rs 294.2 crore increase in private-sector inflow.
Outside-India manufacturing inflow was Rs 50.6 crore in FY26, compared with Rs 108.2 crore in FY24 and Rs 22.2 crore in FY25. The FY26 figure therefore recovered from FY25 but remained below the FY24 level.
Why did Laser Power’s working-capital days increase to 129?
Laser Power reported 129 working-capital days in FY26, up from 86 in FY24, but did not disclose a cause for the increase. Days first declined to 77 in FY25 before rising by 52 days in FY26, alongside an increase in the reported working-capital balance.
Working capital rose to Rs 1,020.7 crore in FY26 from Rs 403.8 crore in FY24 and Rs 619.1 crore in FY25. Revenue from operations, however, declined to Rs 2,326.1 crore in FY26 from Rs 2,438.5 crore in FY25, following revenue of Rs 1,617.9 crore in FY24.
The presentation reported working capital of Rs 1,158.7 crore and working-capital days of 181 in H1 FY27, the first half of FY27. It provided no full-year FY27 working-capital target, cash-flow forecast or stated explanation for the H1 FY27 movement.
Laser Power’s debt-to-equity ratio was 1.1 in FY26, compared with 0.7 in FY24 and 0.8 in FY25. The ratio was 0.4 in H1 FY27, when capital expenditure was Rs 23.2 crore, against Rs 45.5 crore in FY26.
Got a follow-up? Ask IRIS
How did revenue and profit change alongside the backlog?
Laser Power’s FY26 revenue from operations fell 4.6% to Rs 2,326.1 crore from Rs 2,438.5 crore in FY25, even as its order book rose to Rs 3,243.4 crore. The presentation reports a 19.9% compound annual growth rate for revenue between FY24 and FY26.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, increased to Rs 301.7 crore in FY26 from Rs 234.4 crore in FY25 and Rs 149.6 crore in FY24. EBITDA margin increased to 13.0% in FY26 from 9.6% in FY25 and 9.2% in FY24.
Profit after tax, or PAT, was Rs 119.2 crore in FY26, compared with Rs 100.5 crore in FY25 and Rs 37.9 crore in FY24. PAT margin rose to 5.1% from 4.1%, while H1 FY27 revenue, EBITDA and PAT were Rs 1,149.8 crore, Rs 141.7 crore and Rs 51.7 crore, respectively.
The revenue mix moved towards government customers in FY26, when government-sector revenue was Rs 1,515.7 crore, or 65.2% of revenue. That compares with Rs 1,437.0 crore, or 58.9%, in FY25, while private-sector revenue declined to Rs 810.4 crore from Rs 1,001.5 crore.
What expansion plans has Laser Power disclosed?
Laser Power says it plans to diversify into specialty and high-performance conductors through research and development, high-temperature low-sag and high-temperature very low-sag conductor adoption, and its manufacturing agreement with TS Conductor Corp. The presentation provides no capital-expenditure amount or completion date for these initiatives.
Laser Power also says it intends to expand its EPC portfolio into water distribution and solar EPC using its engineering, execution and project-management capabilities. Its plan includes pursuing opportunities through strategic joint ventures and consortiums, including projects linked to the Revamped Distribution Sector Scheme, Saubhagya and National Electricity Plan 2.0.
The company identifies manufacturing execution systems, enterprise resource planning and Power BI as elements of its automation plan. It also cites capacity expansion and new-client acquisition to support domestic government work, exports and overseas EPC opportunities, without disclosing numerical capacity or export targets.
Conclusion
Laser Power’s FY26 backlog expansion was led by manufacturing, where pending orders more than tripled from FY24 to Rs 1,668.9 crore, while EPC backlog was still below its FY24 level. The company also recorded a FY26 revenue decline from FY25, even as EBITDA margin rose to 13.0% and PAT margin reached 5.1%.
The next disclosures to watch are conversion of the Rs 3,243.4 crore FY26 order book into revenue and the working-capital trajectory after days reached 181 in H1 FY27. Management’s disclosed plans cover advanced conductors, water and solar EPC, automation, capacity expansion and international markets, but the presentation does not provide quantified targets or completion dates for those plans.