










Laxmi Dental FY26 revenue reaches Rs 277.86 crore, PAT falls
Key highlights
- Laxmi Dental reported FY26 revenue from operations of Rs 277.86 crore, versus Rs 136.85 crore in FY22.
- Laxmi Dental's FY26 PAT after joint ventures was Rs 28.92 crore, down from Rs 31.83 crore in FY25.
- Laxmi Dental reported negative Rs 5 crore of FY26 operating cash flow after a Rs 42.55 crore working-capital outflow.
- Laxmi Dental's international laboratory revenue rose to Rs 78.40 crore in FY26 from Rs 60.70 crore in FY25.
powered by IRIS
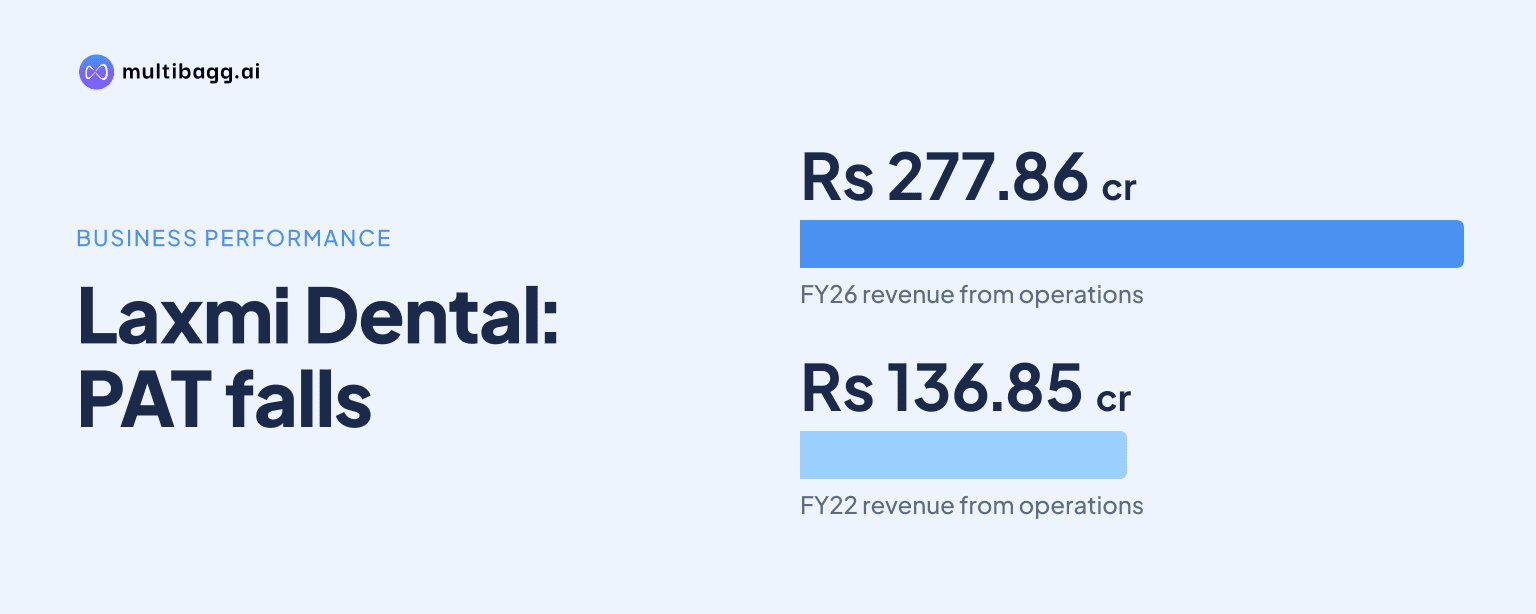
Laxmi Dental Limited reported financial year 2026 (FY26) revenue from operations of Rs 277.86 crore, up from Rs 136.85 crore in FY22, while profit after tax (PAT) after joint ventures declined to Rs 28.92 crore from Rs 31.83 crore and operating cash flow turned negative Rs 5 crore.
Know Laxmi Dental inside out
Results, valuation, peers and who's buying, in one view.
How did Laxmi Dental's revenue and earnings change from FY22 to FY26?
Laxmi Dental more than doubled revenue from operations over the five reported financial years, reaching Rs 277.86 crore in FY26 from Rs 136.85 crore in FY22. Revenue increased each year in the series, from Rs 161.63 crore in FY23 to Rs 193.56 crore in FY24 and Rs 239.11 crore in FY25, according to the consolidated profit and loss statement.
Earnings before interest, tax, depreciation and amortisation (EBITDA) rose to Rs 43.40 crore in FY26 from Rs 5.42 crore in FY22. FY26 EBITDA was also Rs 1.53 crore above FY25 EBITDA of Rs 41.87 crore, although the EBITDA margin declined to 15.6% from 17.5% as revenue expanded and costs rose.
The reported PAT record moved from a loss of Rs 18.67 crore in FY22 to profits in FY24, FY25 and FY26. However, FY26 PAT after joint ventures was Rs 2.91 crore below FY25, while basic earnings per share declined to Rs 5.27 from Rs 6.07.
Which businesses drove Laxmi Dental's FY26 sales?
Laxmi Dental's laboratory business was its largest disclosed revenue stream, generating Rs 166.80 crore in FY26 compared with Rs 140.90 crore in FY25 and Rs 101.10 crore in FY23. The presentation states an 18% compound annual growth rate from FY23 to FY26 for laboratory revenue, excluding scanner sales.
International laboratory revenue increased to Rs 78.40 crore in FY26 from Rs 60.70 crore in FY25, while domestic laboratory revenue rose to Rs 88.40 crore from Rs 80.20 crore. International sales therefore supplied Rs 17.70 crore of the laboratory business's Rs 25.90 crore year-on-year revenue increase in FY26.
Aligner solutions produced Rs 73.20 crore in FY26, up from Rs 68.40 crore in FY25 and Rs 34.70 crore in FY23, with a stated FY23-FY26 compound annual growth rate of 28%. Vedia revenue rose to Rs 33.80 crore from Rs 28.90 crore, while Bizdent revenue was broadly unchanged at Rs 39.40 crore versus Rs 39.50 crore.
Kids-e-Dental recorded Rs 21.10 crore of revenue in FY26, down from Rs 26.30 crore in FY25 and Rs 26.70 crore in FY24. Laxmi Dental states that Kids-e-Dental is jointly controlled and not consolidated under Indian Accounting Standards, so its stated 38% FY23-FY26 growth rate and revenue are presented only as a 100% reference figure.
Got a follow-up? Ask IRIS
Why did Laxmi Dental's FY26 PAT trail FY25?
Laxmi Dental's PAT after the share of profit or loss from joint ventures was Rs 28.92 crore in FY26, compared with Rs 31.83 crore in FY25 despite Rs 38.75 crore of additional revenue. The PAT margin after joint ventures fell to 10.4% from 13.3% in the preceding year.
The gross profit margin declined to 70.4% in FY26 from 76.1% in FY25, as cost of goods sold increased to Rs 82.19 crore from Rs 57.24 crore. Employee cost rose to Rs 102.10 crore from Rs 85.77 crore, while other expenses fell to Rs 50.17 crore from Rs 54.22 crore.
Below EBITDA, depreciation and amortisation increased to Rs 15.88 crore in FY26 from Rs 15.02 crore in FY25, while finance cost declined to Rs 1.37 crore from Rs 5.39 crore. Other income rose to Rs 8.55 crore from Rs 3.34 crore, but the share of profit from joint ventures declined to Rs 2.49 crore from Rs 7.17 crore.
Laxmi Dental also reported adjusted EBITDA of Rs 51.15 crore in FY26, slightly below Rs 51.61 crore in FY25. The company defines this non-standard measure by adjusting reported EBITDA for non-cash employee stock-option expenses, specified shares of Kids-e-Dental and IDBG AI Dent PAT, and an IDS event expense recorded in the fourth quarter of FY25.
What do Laxmi Dental's FY26 cash flow and balance sheet show?
Laxmi Dental generated operating profit before working-capital changes of Rs 44.23 crore in FY26, close to Rs 44.40 crore in FY25, but reported a Rs 42.55 crore working-capital outflow. After Rs 6.68 crore of direct taxes paid net of refunds, net cash from operating activities was negative Rs 5 crore, compared with an inflow of Rs 43.83 crore in FY25.
The cash-flow statement does not provide a line-item explanation for the Rs 42.55 crore working-capital movement. At 31 March 2026, trade receivables were Rs 45.54 crore against Rs 36.68 crore a year earlier, other current financial assets were Rs 81.81 crore against Rs 6.11 crore, and inventories increased to Rs 21.75 crore from Rs 18.65 crore.
Investing activities used Rs 79.58 crore in FY26, compared with Rs 29.24 crore in FY25, while financing activities used Rs 17.75 crore after an inflow of Rs 110.64 crore in FY25. Cash and cash equivalents ended FY26 at Rs 8.40 crore, compared with Rs 109.36 crore at the beginning of the year in the cash-flow statement.
Total assets rose to Rs 293.97 crore at 31 March 2026 from Rs 284.67 crore a year earlier, while total liabilities declined to Rs 49.86 crore from Rs 75.97 crore. Total equity increased to Rs 244.11 crore from Rs 208.70 crore, and the FY26 balance sheet does not report amounts in its current or non-current borrowings rows, compared with combined borrowings of Rs 11.37 crore in FY25.
Conclusion
Laxmi Dental's five-year statements show a substantial expansion in revenue, EBITDA and reported profitability, moving from a Rs 18.67 crore FY22 loss after joint ventures to FY26 PAT of Rs 28.92 crore. The FY26 comparison also shows that higher revenue and EBITDA did not translate into higher final PAT or operating cash flow, with a Rs 42.55 crore working-capital outflow affecting cash conversion.
The next disclosed operating marker is management's target to raise domestic laboratory digital penetration from about 75% in FY26 to more than 90%. The presentation also identifies iScope 360 and PEOT launches, investment in AI Dent, and 17% FY26 Taglus revenue growth, but does not quantify their expected future financial contribution.