










LG Electronics India Q2 revenue rises 19.5%, margin reaches 9.5%
Key highlights
- LGEIL's Q2'FY27 revenue from operations rose 19.5% year-on-year to Rs 7,380 crore.
- LGEIL's Q2'FY27 EBITDA margin expanded 63 basis points year-on-year to 9.5%.
- LGEIL's H&A sales rose 20.9% to Rs 4,772 crore, while HE sales rose 17.2% to Rs 2,608 crore.
- LGEIL ended Q2'FY27 with Rs 5,051 crore of cash after a Rs 656 crore quarterly decline.
powered by IRIS
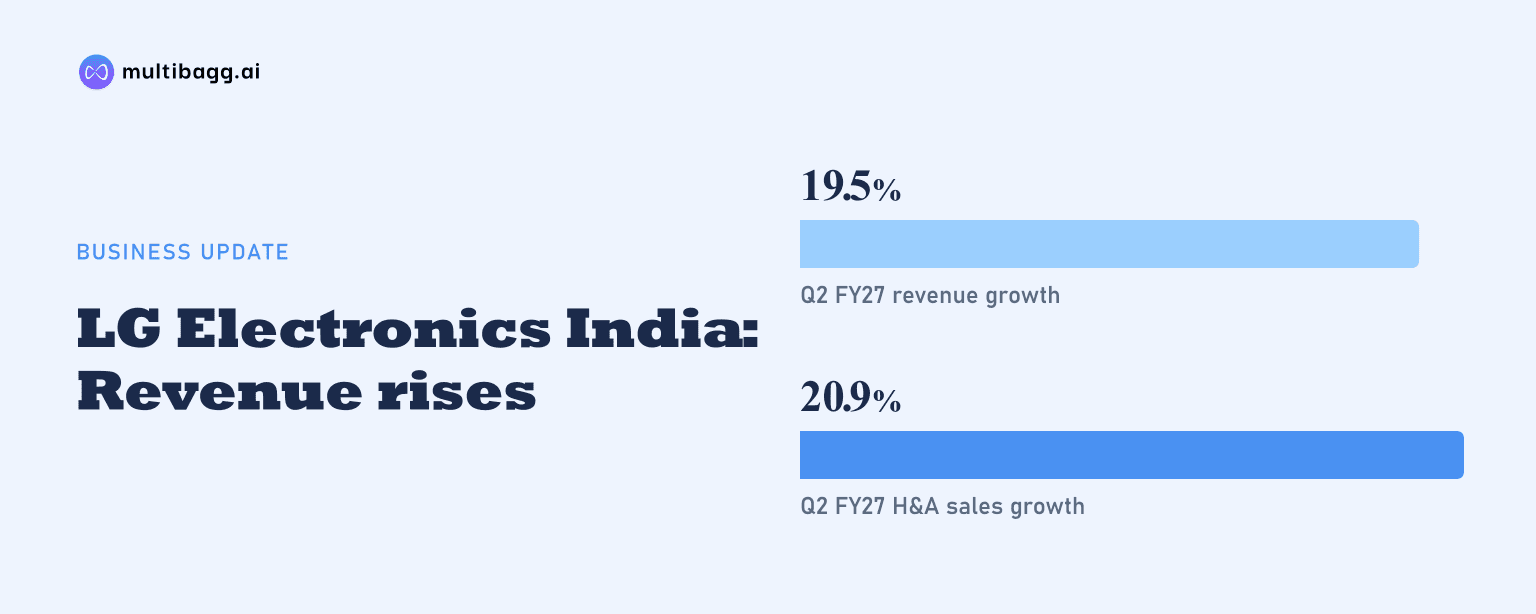
LG Electronics India reported Rs 7,380 crore of revenue from operations in Q2'FY27, a 19.5% year-on-year increase, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin expanded 63 basis points to 9.5%. LGEIL attributed the result to volume growth, premium product mix, operating leverage and export momentum across its two operating segments.
Know LG Electronics India inside out
Results, valuation, peers and who's buying, in one view.
How did LGEIL's Q2'FY27 revenue and profitability change?
LGEIL increased revenue from operations by 19.5% year-on-year to Rs 7,380 crore in Q2'FY27, following Rs 6,174 crore in Q2'FY26 and Rs 7,233 crore in Q1'FY27. The 2.0% sequential increase marked a second consecutive quarter of double-digit year-on-year growth. Management said both volume and value growth contributed, with demand across mass and premium categories supplemented by exports.
EBITDA rose to Rs 701 crore from Rs 548 crore a year earlier, while EBITDA margin reached 9.5%, compared with 8.9% in Q2'FY26 and 12.5% in Q1'FY27. Management cited operating leverage and a richer premium mix for the reported 63-basis-point year-on-year margin expansion. A basis point equals one-hundredth of a percentage point.
LGEIL's profit after tax was Rs 489 crore, up Rs 100 crore from Rs 389 crore in Q2'FY26 but down Rs 164 crore from Rs 653 crore in Q1'FY27. Profit before tax was Rs 655 crore, up Rs 130 crore year-on-year and down Rs 223 crore sequentially. Depreciation and amortisation increased to Rs 123 crore from Rs 93 crore a year earlier, while finance costs were unchanged at Rs 9 crore.
Which LGEIL segments drove Q2'FY27 sales growth?
LGEIL's Home Appliances and Air Solution (H&A) segment produced the larger sales contribution, with revenue of Rs 4,772 crore in Q2'FY27, up 20.9% from Rs 3,948 crore in Q2'FY26. H&A sales were, however, 14.4% below Rs 5,577 crore in Q1'FY27. The segment includes air conditioners, refrigerators, washing machines, dishwashers, compressors, water purifiers and air purifiers.
Management said washing machines, refrigerators and room air conditioners led H&A's growth, while dishwashers delivered breakout growth. It also cited the LG Essential range and the launch of chest freezers as portfolio additions. H&A EBIT, or earnings before interest and tax, rose to Rs 416 crore from Rs 324 crore, and the EBIT margin increased to 8.7% from 8.2%.
Home Entertainment (HE) sales rose 17.2% year-on-year to Rs 2,608 crore, compared with Rs 2,226 crore in Q2'FY26, and increased 57.4% from Rs 1,657 crore in Q1'FY27. HE includes televisions, signage, projectors, audio-visual products, monitors and personal computers. Management said television value growth exceeded volume growth and information displays added to sales growth.
HE recorded EBIT of Rs 337 crore in Q2'FY27, up Rs 56 crore from Rs 281 crore a year earlier, with EBIT margin rising to 12.9% from 12.6%. Its margin was below Q1'FY27's 19.0%, even as quarterly sales increased. The two segment EBIT totals exceed consolidated EBIT because LGEIL allocates some expenses outside the segments.
Why did LGEIL's margin rise despite higher costs?
LGEIL said its 9.5% Q2'FY27 EBITDA margin reflected operating leverage and premium mix despite elevated commodity prices, rupee depreciation and go-to-market investment before the festive season. In H&A, management specifically identified copper, aluminium and polypropylene as higher-cost inputs. H&A EBIT margin nevertheless rose 0.5 percentage point year-on-year to 8.7% as higher volumes and premium products offset those pressures.
HE EBIT margin increased 0.3 percentage point year-on-year to 12.9%, supported by higher volumes and improved profitability in business-to-business operations, according to management. The segment also faced commodity inflation, foreign-exchange headwinds and festive-season selling investment. Its margin declined 6.1 percentage points from 19.0% in Q1'FY27, showing a different sequential outcome from the year-on-year comparison.
Consolidated EBIT was Rs 578 crore in Q2'FY27, up from Rs 454 crore in Q2'FY26 but down from Rs 792 crore in Q1'FY27. Consolidated EBIT margin was 7.8%, against 7.4% a year earlier and 11.0% sequentially. That measure differs from the 9.5% EBITDA margin because depreciation and amortisation are deducted in arriving at EBIT.
Got a follow-up? Ask IRIS
What did LGEIL report on cash flow and investment?
LGEIL ended Q2'FY27 with Rs 5,051 crore of cash, compared with Rs 4,284 crore at the end of Q2'FY26. Cash declined by Rs 656 crore during the quarter, versus a Rs 291 crore reduction in the corresponding prior-year period. Cash flow from operating activities was negative Rs 164 crore, compared with positive Rs 86 crore a year earlier.
The operating cash-flow movement included a Rs 672 crore net working-capital outflow, larger than the Rs 306 crore outflow in Q2'FY26. Investing cash outflow was Rs 461 crore, including Rs 544 crore for net increases in tangible assets, while financing cash outflow was Rs 32 crore for lease-obligation repayments. Cash at the beginning of Q2'FY27 was Rs 5,707 crore.
LGEIL expects its Sri City plant to commence operations in Q3'FY27 with compressor manufacturing. Management said the facility is expected to enhance localisation, support domestic and export demand, and double existing capacity. The presentation did not disclose a project cost, output volume or a more specific commissioning date.
What is LGEIL's FY'27 and Q3'FY27 outlook?
LGEIL reaffirmed management's FY'27 targets of mid-teen revenue growth and an early double-digit EBITDA margin after reporting Q2'FY27 revenue of Rs 7,380 crore and EBITDA margin of 9.5%. These are management targets, not reported outcomes. The company cited its premium portfolio, LG Essential range and expanding export business as support for the festive-season period.
For H&A, management expects festive and wedding demand to favour premium, energy-efficient and larger-capacity appliances in Q3'FY27. French-door refrigerators and dishwashers are expected to retain momentum, while exports and the Sri City compressor facility are intended to support the next growth phase. LGEIL identified commodity and currency trends as matters to monitor.
For HE, LGEIL expects festive demand to support television sales, particularly larger-screen and advanced-display products. The Q2'FY27 range included Mini LED televisions alongside QNED and OLED products, while management said offline television market share reached a record high. It also expects business-to-business profitability to continue contributing alongside television.
Conclusion
LGEIL combined 19.5% year-on-year revenue growth with a 63-basis-point increase in EBITDA margin in Q2'FY27. H&A grew faster year-on-year at 20.9%, while HE delivered the stronger sequential sales increase of 57.4%. The comparison with Q1'FY27 was more mixed, as revenue rose 2.0% but EBITDA, profit after tax and consolidated EBIT margin declined.
The next disclosed milestone is the expected Q3'FY27 start of compressor manufacturing at Sri City. Results through the festive season will indicate LGEIL's progress toward management's mid-teen FY'27 revenue-growth target and early double-digit EBITDA-margin target, alongside the effects of commodity prices, currency movements and working-capital outflows.