










LGT Global Hospitality H1 Revenue Rises 35% to ₹89.68 Crore
Key highlights
- LGT reported H1 FY27 revenue of ₹89.68 crore, up 35.01% from ₹66.42 crore in H2 FY26.
- EBITDA rose 72.25% to ₹3.81 crore and the EBITDA margin improved by 92 basis points to 4.24%.
- LGT reported more than ₹50 crore in confirmed forward bookings for H2 FY27.
- The office network increased from 9 to nearly 14 locations, and LGT added 22 corporate clients.
powered by IRIS
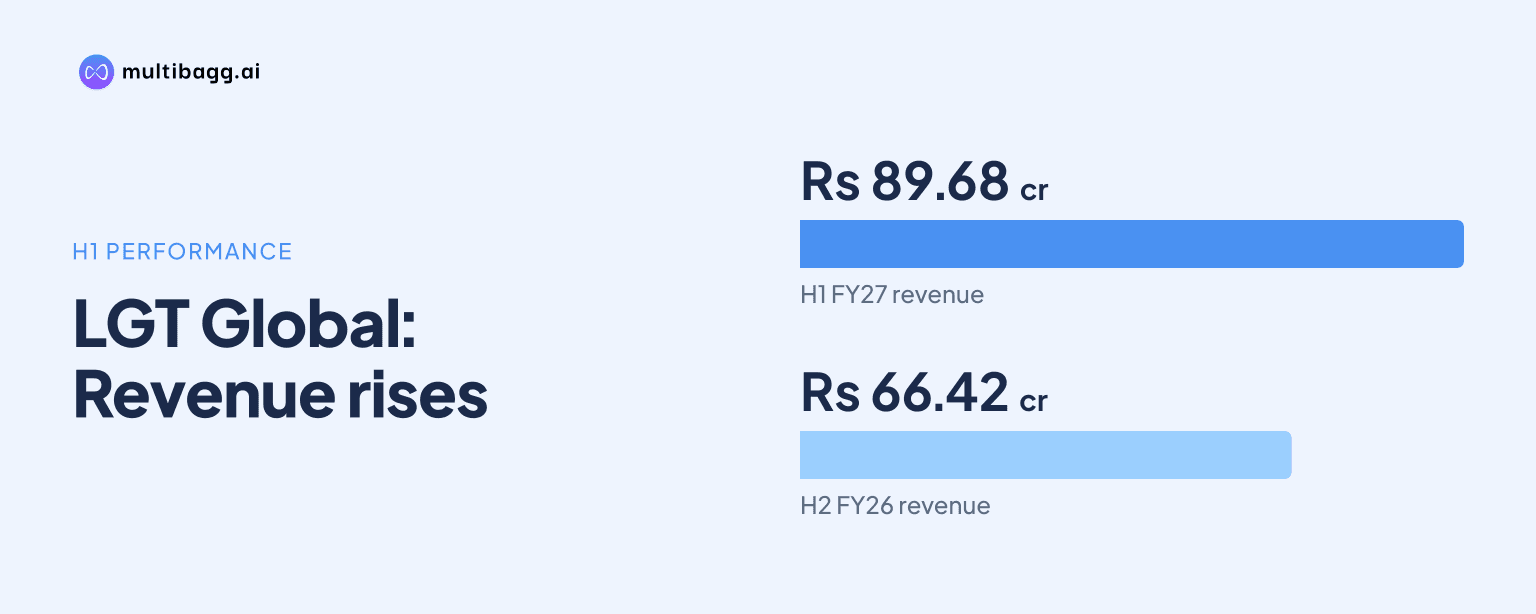
LGT Global Hospitality Limited reported H1 FY27 revenue from operations of ₹89.68 crore, a 35.01% increase from ₹66.42 crore in H2 FY26, while EBITDA rose 72.25% to ₹3.81 crore and forward bookings exceeded ₹50 crore. Management said H2 performance depends on geopolitical stability and a recovery in corporate travel demand.
Know LGT Global Hospitality inside out
Results, valuation, peers and who's buying, in one view.
What did LGT Global Hospitality report for H1 FY27?
LGT reported revenue from operations of ₹89.68 crore for H1 FY27. The company said this was 35.01% higher than ₹66.42 crore in H2 FY26 and 27% above the comparable year-ago period, when revenue was ₹70.57 crore.
Operating profit improved faster than revenue on a half-on-half basis. EBITDA increased 72.25% to ₹3.81 crore, and the EBITDA margin expanded by 92 basis points to 4.24% from 3.33% in H2 FY26. Attributable profit after tax rose 110.72% half-on-half to ₹1.93 crore. The company also reported consolidated PAT of ₹1.96 crore and earnings per share of ₹2.09 in its results material.
The results indicate improved operating leverage compared with the preceding half year, although margins remain modest for a travel and tourism services business. The supplied results commentary also noted that cost of services and employee expenses increased faster than sales in the broader comparison, while consolidated net margin was about 2.2%, compared with 3.4% earlier.
What happened at the H1 FY27 investor meeting?
LGT held its H1 FY27 earnings conference call with analysts and investors on November 18, 2026. The virtual Zoom meeting ran from 4:00 PM to 4:50 PM, after the company had revised the scheduled starting time from 3:00 PM.
The company confirmed that the discussion was based only on publicly available information. It also stated that no unpublished price sensitive information was shared during the call, consistent with the disclosure requirements governing analyst and investor interactions.
Management described the first-half improvement as a result of revenue growth, network expansion and continued investment in operating capacity. It said H2 FY27 should be better than H1 in volume, revenue and operating margin, but made that view conditional on geopolitical normalisation, lower operating costs and a recovery in demand.
No revenue, margin or acquisition-contribution targets were provided for the second half or the full year. Management referred to a five-times growth plan and a ₹500 crore ambition, but did not disclose a timetable, baseline or financial projection for that plan.
How is LGT expanding its travel-services network?
LGT expanded its office network from nine locations to nearly 14 during the period and added 22 corporate clients. The locations identified in the company material include Nagercoil, Coimbatore, Jaipur, Indore and Vadodara, reflecting a push to widen its domestic service footprint despite a weaker market environment.
The company said it continued spending on capacity and systems as part of its growth preparation. Its stated initiatives include scaling Wilfred Collections and Hotel Stays, developing an online travel platform, and upgrading customer relationship management, mid-office and finance systems.
Further expansion is under consideration. Management identified Ahmedabad as the next planned office location and said it was evaluating opportunities in western India. Dubai and Thailand were also mentioned as locations under consideration, without any announced launch date or committed investment amount.
For investors, the office additions need to be viewed alongside the cost base. The supplied financial commentary said borrowings rose to ₹12.0 crore and receivables increased to ₹23.0 crore. It also stated that ₹7.79 crore of IPO proceeds remained unutilised. These figures show that network growth and working-capital management remain relevant to the company’s financial position.
Got a follow-up? Ask IRIS
What does more than ₹50 crore in bookings mean for H2 FY27?
Confirmed forward bookings of more than ₹50 crore provide LGT with visible demand entering H2 FY27, but the company did not give a schedule for conversion into revenue or any associated profitability estimate. Bookings therefore indicate order visibility rather than a formal revenue forecast.
Management linked its positive H2 view to a normalisation in geopolitical conditions and the return of pent-up corporate demand. These factors are important in the travel sector because corporate movement, hotel reservations and related travel services can change quickly when customer budgets or regional conditions shift.
The company’s comments were cautious rather than numerical guidance. It did not set a target for revenue growth, EBITDA margin or profit, and it did not quantify the contribution expected from new offices, subsidiaries or digital initiatives. Investors will therefore need to assess future performance through reported bookings conversion, margin movement and working-capital trends.
The result also presents a mixed profitability context. Half-on-half EBITDA margin improved to 4.24%, but the available commentary says standalone PAT was down 48% year-on-year and consolidated net margin declined from 3.4% to about 2.2%. Higher sales alone will not determine earnings quality if service, employee and expansion costs continue to rise.
Why do LGT's H1 FY27 results matter to investors?
LGT's H1 FY27 numbers matter because revenue growth and EBITDA expansion were accompanied by a substantial increase in forward bookings, while management continued to build its office network. The combination suggests that the company is seeking scale in corporate travel and related hospitality services rather than limiting operations to short-term margin protection.
At the same time, the company operates in a sector exposed to corporate travel budgets, demand cycles and geopolitical conditions. Management itself made its H2 expectations conditional on demand recovery and stabilisation in external conditions. This makes execution on bookings, pricing and operating costs more significant than broad growth aspirations.
The company’s investor materials describe LGT as an India-based provider of integrated travel and tourism solutions for corporate and individual clients. It was formerly known as LGT Business Connextions Limited. The supplied record does not provide usable transcripts for the prior three periods, so a reliable assessment of changes in management commentary across earlier quarters is not available.
Conclusion
LGT delivered H1 FY27 revenue of ₹89.68 crore, up 35.01% from H2 FY26, with EBITDA of ₹3.81 crore and a 4.24% EBITDA margin. Its more than ₹50 crore of confirmed forward bookings and increased office footprint support management’s view that demand can improve in the second half, but current profitability remains sensitive to costs and travel-market conditions.
The next areas to watch are the conversion of H2 bookings into reported revenue, movement in EBITDA and net margins, receivables and borrowings, and progress on the Ahmedabad office and other proposed expansions. Management has not issued quantified FY27 guidance or a timetable for its five-times growth plan, leaving future disclosures and results as the main indicators of execution.