










Manraj Housing Finance faces adverse conclusion on accounts
Key highlights
- The auditor identified Rs 7.89 crore of unprovided loan interest and penal interest at September 30, 2026.
- ASREC is seeking Rs 11.88 crore from Manraj Housing Finance in Original Application No. 167/2026 before DRT-2.
- Manraj Housing Finance reported negative equity of Rs 85.57 lakh at September 30, 2026, versus negative Rs 74.96 lakh at March 31, 2026.
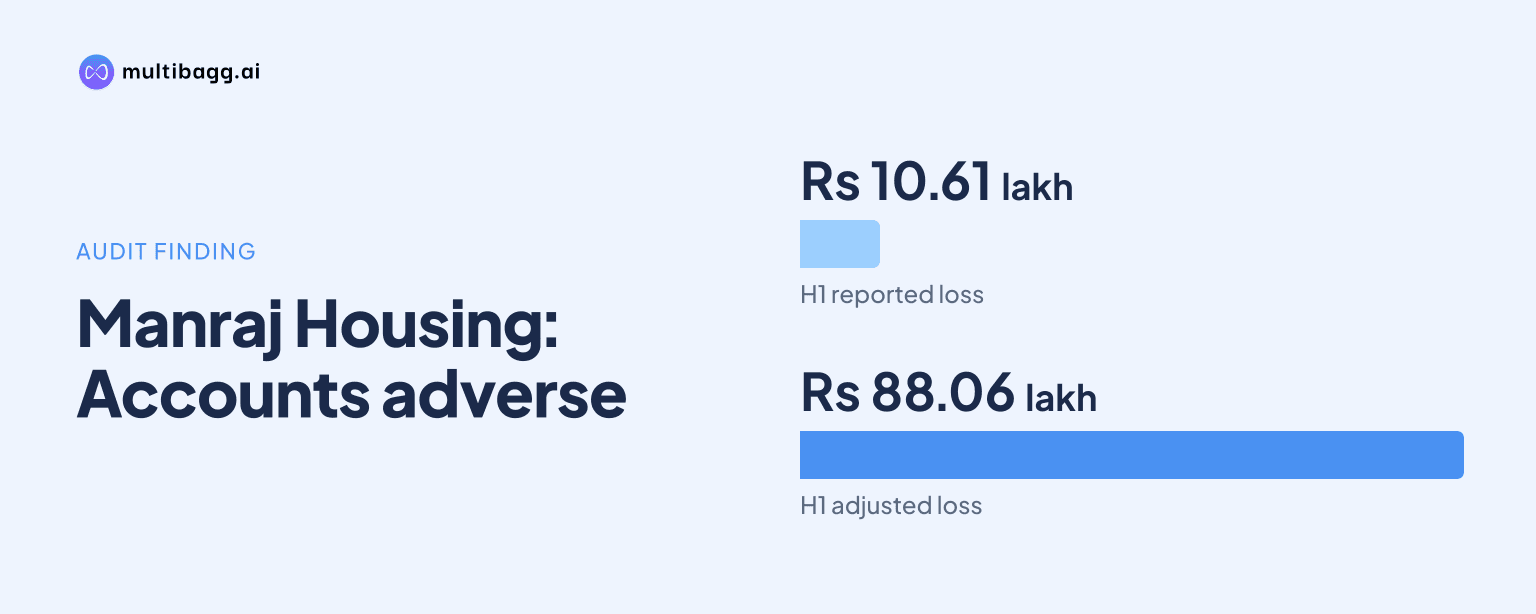
- The reported half-year loss was Rs 10.61 lakh, while the quantified adjustment would raise it to Rs 88.06 lakh.
powered by IRIS
Manraj Housing Finance Limited received an adverse review conclusion on its standalone results for the quarter and half year ended September 30, 2026, after the auditor said loan liabilities were understated by Rs 7.89 crore and the accounts did not give a true and fair view. The conclusion also cited attached related-party assets, recovery proceedings and going-concern uncertainty.
Know Manraj Housing Finance inside out
Results, valuation, peers and who's buying, in one view.
Why did Manraj Housing Finance receive an adverse review conclusion?
Manraj Housing Finance received the adverse conclusion because Ratan Chandak & Co LLP said the September 30, 2026 statement omitted required disclosures and did not give a true and fair view of its net loss and other financial information. The report, dated November 9, 2026, covered unaudited standalone results for the quarter and six months ended September 30, 2026.
The auditor identified five matters: related-party advances affected by Enforcement Directorate attachments, related-party liabilities, defaulted bank borrowings, undisclosed recovery proceedings and material uncertainty over going concern. The company’s statement on audit qualifications said the first, second, third and fifth matters had continued for the last three years, while the recovery-proceeding disclosure issue was reported as a first-time qualification.
The reported half-year loss before tax was Rs 10.61 lakh on total income of Rs 2.04 lakh, all of which was other income because revenue from operations was nil. The auditor said unrecognised interest on defaulted debt understated the half-year loss by Rs 77.45 lakh. Manraj Housing Finance’s impact statement showed the reported and adjusted figures below.
The quantified adjustment concerns the borrowing interest issue only. It does not address the separate audit concerns about recoverability and valuation of related-party balances, the completeness and accuracy of related-party liabilities, or disclosures of litigation and asset restraints. The Board approved the September 2026 results on November 9, 2026, the same date as the review report.
How are Enforcement Directorate attachments linked to Manraj Housing Finance assets?
The auditor said around 95% of Manraj Housing Finance assets comprised advances, deposits, receivables and other balances recoverable from related parties for acquisition of properties and rights. Those related parties were under investigation by the Enforcement Directorate under the Prevention of Money Laundering Act, and related assets representing around 99% of Manraj Housing Finance assets had been attached, according to the review report.
Manraj Housing Finance reported total assets of Rs 19.53 crore at September 30, 2026, compared with Rs 18.51 crore at March 31, 2026. Other non-current assets were Rs 18.55 crore, while current assets were Rs 93.35 lakh, including cash and cash equivalents of Rs 1.84 lakh. The auditor said the attachments created significant concerns about the recoverability and valuation of the related-party advances underlying the asset base.
Management said the Enforcement Directorate investigation involved companies under common management control and that Manraj Housing Finance had no link with them other than common management. It said those companies were cooperating with the Enforcement Directorate and submitting documents and records. The auditor nevertheless maintained the adverse conclusion based on the significance of the attachment and recoverability matters.
Got a follow-up? Ask IRIS
What is the defaulted borrowing and recovery claim against Manraj Housing Finance?
Manraj Housing Finance had Rs 6.87 crore outstanding to Jalgaon Peoples Co-Op. Bank Ltd as of February 2020, according to the auditor. The bank later assigned the loan accounts to ASREC (India) Ltd, an asset reconstruction company, and the company did not provide interest on the outstanding balance after that assignment.
ASREC’s statement showed uncharged interest of Rs 3.90 crore and penal interest of Rs 52.41 lakh for March 1, 2020 to March 31, 2024, totalling Rs 4.43 crore. The auditor identified a further Rs 3.46 crore of uncharged interest for April 1, 2024 to September 30, 2026. Together, these amounts produced the Rs 7.89 crore understatement of loan liabilities, as well as understatements of Rs 39.49 lakh in the quarter’s loss and Rs 77.45 lakh in the half-year loss.
ASREC filed Original Application No. 167/2026 before Debts Recovery Tribunal Mumbai-2, or DRT-2, seeking Rs 11.88 crore from Manraj Housing Finance and others. The tribunal restrained the company from dealing with or disposing of secured and specified assets pending disposal of the application. The auditor said the September statement did not disclose the proceedings, claim amount, restraint or management’s assessment of the effects, as required under Indian Accounting Standard 37 and Indian Accounting Standard 34.
Management said a previous one-time settlement with ASREC was revoked because its conditions were not fulfilled. It said ASREC had not communicated applicable interest and penal-interest charges through September 30, 2026, and cited uncertainty over their quantum and enforceability for not recording a provision. Management said it was contesting the DRT-2 claim, negotiating with ASREC and intended to pursue a renewed settlement when the legal situation stabilises.
Can Manraj Housing Finance continue as a going concern?
The auditor said a material uncertainty may cast significant doubt on Manraj Housing Finance’s ability to continue as a going concern. It cited the absence of significant operating activity for more than three years, defaulted borrowings, unprovided borrowing interest and accumulated losses that had eroded net worth at September 30, 2026.
Total equity was negative Rs 85.57 lakh at September 30, 2026, compared with negative Rs 74.96 lakh at March 31, 2026. Other equity was negative Rs 5.86 crore, versus negative Rs 5.75 crore six months earlier. The balance sheet showed bank borrowings of Rs 6.87 crore and related-party loans of Rs 13.29 crore, compared with related-party loans of Rs 13.18 crore at March 31, 2026.
Revenue from operations was nil in the September 2026 quarter, June 2026 quarter and September 2025 quarter. For the six months ended September 30, 2026, employee-benefit expense was Rs 5.66 lakh, up from Rs 2.34 lakh in the corresponding prior-year period, while other expenses were Rs 6.92 lakh. The reported half-year loss of Rs 10.61 lakh was lower than Rs 38.54 lakh a year earlier, before the auditor’s quantified interest adjustment.
The auditor also said approximately 65% of liabilities were unsecured loans from related parties that had beneficial interests in the properties for which advances were given. Management said these interest-free loans had supported operations and liquidity, but that funds were stuck because of tenant resistance to redevelopment and attachment of the concerned property. It said liability settlement had been delayed by those factors.
Conclusion
Manraj Housing Finance’s adverse conclusion means its September 2026 results must be considered alongside the auditor’s findings on unprovided borrowing costs, related-party balances and missing litigation disclosures. The reported Rs 19.53 crore asset base, negative Rs 85.57 lakh equity, Rs 7.89 crore unprovided loan liability and Rs 11.88 crore DRT-2 claim together explain the auditor’s stated material uncertainty.
The next developments to watch are progress in Original Application No. 167/2026, management’s stated negotiations with ASREC and its plan to liquidate real-estate assets after legal and procedural impediments are resolved. Management said asset realisation and operational revival are intended to absorb accumulated losses and restore positive net worth, but the filing did not provide a timetable or settlement target.