










Matrimony.com Limited resets Wedding Services to commission model
Key highlights
- Matrimony.com reduced a near Rs 1 crore monthly Wedding Services vendor-subscription run rate to virtually zero.
- Matrimony.com now plans to earn Wedding Services revenue from member fees and provider commissions.
- Wedding Services is mainly operating in Tamil Nadu pending undisclosed scale and success metrics.
- Matrimony.com reported Q2 paid-volume growth of 26.6% in its core matchmaking business.
powered by IRIS
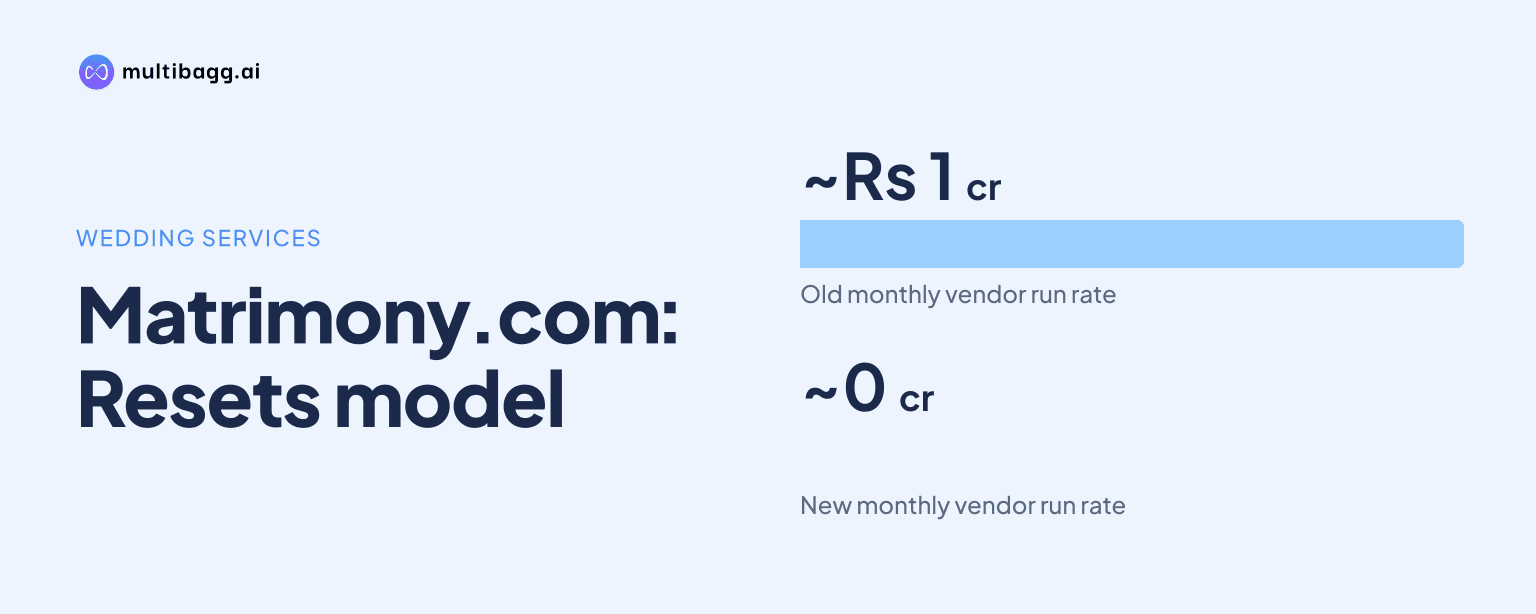
Matrimony.com Limited reset Wedding Services after cutting a vendor-subscription operation that had neared a Rs 1 crore monthly run rate to virtually zero, replacing it with commissions from providers and fees from members. Management said the rebuilt model has been its focus for the last couple of quarters and is largely limited to Tamil Nadu.
Know Matrimony.com inside out
Results, valuation, peers and who's buying, in one view.
Why did Matrimony.com change the Wedding Services model?
Matrimony.com changed the model because management concluded that vendor subscriptions would not scale beyond a certain point. The earlier operation had approached a Rs 1 crore monthly run rate, but Matrimony.com substantially reduced it to build a model based on facilitating customer transactions rather than collecting recurring vendor payments.
This is a business-model reset rather than an extension of the previous revenue stream. Management said the earlier effort still left useful assets, including vendor relationships, leads and brand awareness, but it no longer views subscriptions as the model to pursue. It described Wedding Services as effectively starting from scratch despite having operated in the category for several years.
The change fits Matrimony.com’s plan to derive more revenue from customers acquired through matchmaking. Management said it has millions of users and intends to integrate Wedding Services more closely with its core matchmaking journey. Its stated mechanism is to make members aware of the service and its value proposition, rather than incur substantial new marketing spending to acquire wedding-services customers.
How does Matrimony.com earn revenue from Wedding Services now?
Matrimony.com now earns revenue through member service fees and service-provider commissions. Its WedAssist service helps members identify providers for wedding venues, photography, makeup and parties, with the company charging members who use the assistance and receiving a commission from the provider.
The commercial arrangement differs from the old directory-style subscription approach. Under the new structure, revenue is intended to arise when Matrimony.com facilitates a service selection, while the former model depended on vendors paying subscriptions regardless of completed transactions. Management said it believes this transaction-linked approach can scale more effectively than the subscription model.
Wedding Services includes more than WedAssist. Management identified Mandap.com, venue tie-ups, contracts with service providers, technology and product development as components of the wider operation. These elements support the commission model, but they also require operating expenditure before transaction volumes reach a level that can absorb those costs.
Matrimony.com did not disclose commission rates, member-fee levels, order volume, provider count or Wedding Services revenue. Management said it is seeing early traction and quarter-on-quarter growth after focusing on the model for the last couple of quarters. That provides a directional update, but not a disclosed measure of the revenue base or the path to break-even.
Why is Matrimony.com Wedding Services still loss-making?
Wedding Services remains loss-making because it carries costs for people, processes, leadership, technology, product work and provider arrangements. An analyst on the call described the operation as making an annual EBITDA loss of Rs 15 crore, where EBITDA means earnings before interest, tax, depreciation and amortisation; management did not confirm that amount but said the business has these cost requirements.
Management said losses should decline as the number of transaction units rises, but it gave no volume threshold, profitability target or date for break-even. It also rejected the prospect of closing the operation, saying it remains confident in the opportunity and is focused on making it successful. The stated plan is therefore to establish scale, not to limit the initiative to its current loss level.
The contrast with the matchmaking segment is notable. Matrimony.com said it had almost 5.7 lakh paid users in the first two quarters, compared with almost 5 lakh in the prior comparison cited on the call, an increase of about 70,000. Management said Q2 paid volume rose 26.6%, partly after it introduced shorter-duration packages for selected customer cohorts.
Those core-business metrics do not yet have an equivalent for Wedding Services. Management said shorter-duration matchmaking packages reduced average revenue per user while increasing paid-user volume, whereas Wedding Services has no disclosed transaction or conversion data. Investors therefore cannot use the 5.7 lakh paid-user figure to infer how many matchmaking members use WedAssist or Mandap.com.
Got a follow-up? Ask IRIS
Where is Matrimony.com rolling out the commission model?
Matrimony.com is rolling out the rebuilt Wedding Services model mainly in Tamil Nadu. Management said the operation is “pretty much” limited to one market, although it still sells some subscriptions elsewhere. It characterised that remaining subscription revenue as very small and insignificant.
The Tamil Nadu focus is deliberate because management wants to reach a certain scale and satisfy success metrics before expanding into other markets. It did not define those metrics, provide a target revenue level or name the next state for rollout. The near-term test is therefore execution in Tamil Nadu rather than a disclosed national expansion schedule.
Matrimony.com’s established matchmaking footprint is broader than the Wedding Services rollout. Management said it remains a strong player in South, West and East markets, while describing North as a market where it is one of the players rather than the number-one player. The company expects Wedding Services to draw initially on existing matchmaking customer relationships, but it has not quantified cross-sell conversion by region.
Management said extra marketing investment could eventually be needed, particularly as it learns how to grow adjacent offerings. However, it argued that the existing matchmaking customer base reduces the need for launch-stage customer-acquisition spending. This is management’s stated operating rationale, not a disclosed cost target or a guarantee that Tamil Nadu results can be replicated elsewhere.
What should investors watch in upcoming quarters?
Investors should watch for disclosed Wedding Services transaction, revenue and loss measures as the commission model develops. Management said it expects month-on-month and quarter-on-quarter growth, but it has not provided bookings, commission income, active-provider numbers, repeat-customer data or contribution margins for WedAssist and Mandap.com.
A second measure is whether additional transaction units reduce the cost burden of the leadership team, product, technology and provider network. Management linked lower losses to greater scale but did not disclose the number of transactions required. Any future update on profitability would need to distinguish the new commission base from the former Rs 1 crore monthly subscription run rate that was intentionally scaled down.
The core matchmaking business remains relevant to the cross-sell opportunity. Management said it expects about 3 lakh paid transactions per quarter to be sustainable following the shorter-duration package introduction, and it reported 26.6% Q2 paid-volume growth. More paying matchmaking customers could expand the addressable pool for Wedding Services, although Matrimony.com has not disclosed the conversion rate from matchmaking to wedding-service use.
Management also said it expects Q3 revenue to grow at a double-digit rate while billing faces seasonal effects from Shradh and Navratri. That outlook applies to the wider business rather than Wedding Services specifically. It nevertheless provides the context in which the company intends to fund and integrate adjacent offerings using its existing customer base.
Conclusion
Matrimony.com has replaced a vendor-subscription approach that neared a Rs 1 crore monthly run rate with a model based on provider commissions and member fees. The reset retains prior vendor relationships, leads and brand assets, but leaves the business rebuilding revenue from a virtually zero base while continuing to support WedAssist, Mandap.com, technology and provider-network costs.
The next issue is whether the Tamil Nadu rollout reaches the undisclosed scale and success metrics management requires before expansion into other markets. Management has said it is seeing early quarter-on-quarter growth and expects losses to reduce as transaction units rise, making future disclosures on revenue, transactions, provider participation and profitability the key measures to watch.