










McLeod Russel India Limited auditors find results not fairly prepared
Key highlights
- Lodha & Co LLP issued an adverse conclusion on McLeod Russel’s standalone results for the quarter and six months ended September 30, 2026.
- Rs 414.21 crore of doubtful inter-corporate deposits remained unprovided at September 30, 2026.
- McLeod Russel reported September-quarter revenue of Rs 391.93 crore and profit of Rs 34.38 crore.
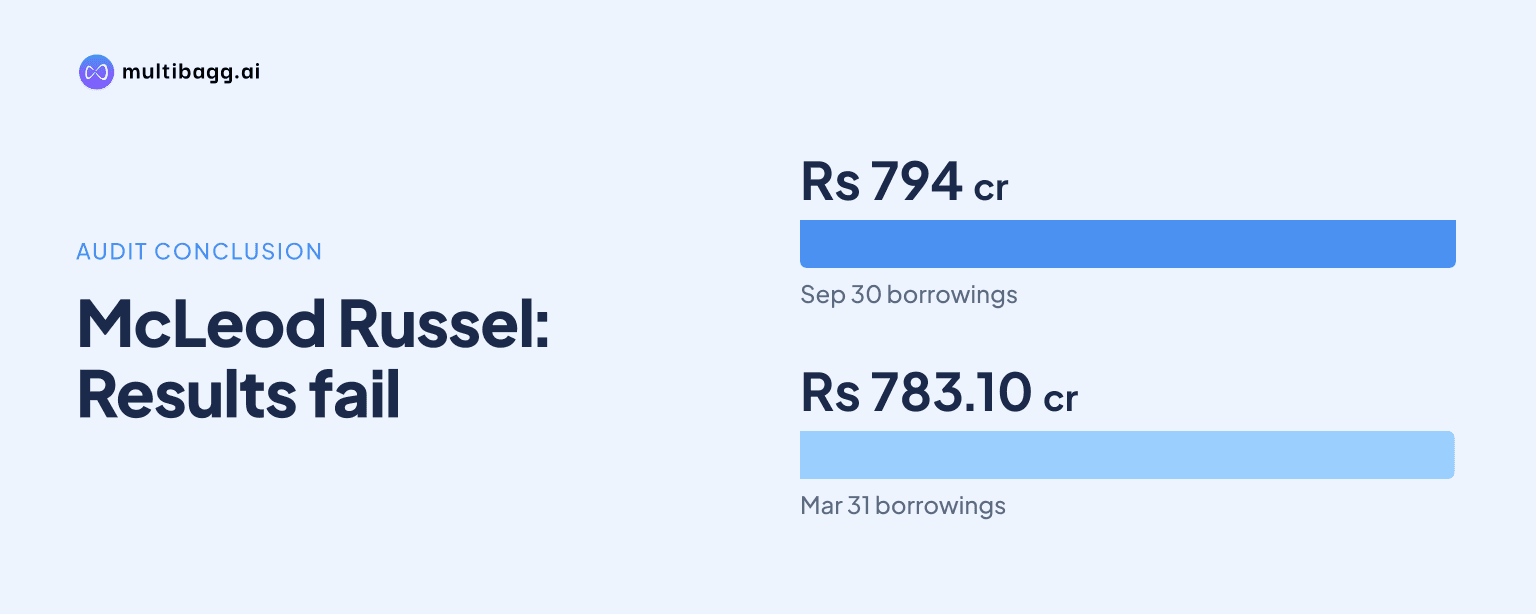
- Current borrowings were Rs 794 crore at September 30, 2026, compared with Rs 783.10 crore at March 31, 2026.
powered by IRIS
On November 14, 2026, McLeod Russel India Limited’s statutory auditor concluded that its standalone results for the quarter and six months ended September 30, 2026 were not prepared fairly in all material respects, with Rs 414.21 crore of doubtful inter-corporate deposits remaining unprovided among the material matters cited.
Know Mcleod Russel India inside out
Results, valuation, peers and who's buying, in one view.
Why did McLeod Russel receive an adverse conclusion?
McLeod Russel received an adverse conclusion because Lodha & Co LLP said several unresolved accounting matters were expected to have a material combined effect on the standalone results for the period ended September 30, 2026. The reviewer concluded that the statement, read with its notes, was not prepared fairly in all material respects under Indian Accounting Standards and did not fairly disclose information required by the Securities and Exchange Board of India’s Listing Obligations and Disclosure Requirements Regulations, 2015.
The November 14, 2026 conclusion followed a limited review under Standard on Review Engagement 2410, which relies primarily on inquiries and analytical procedures and provides moderate assurance rather than an audit opinion. The matters cited include the recoverability of inter-corporate deposits, restructuring of borrowings, unrecognised interest, asset valuation and impairment, lease rent, statutory liabilities, deferred-tax assets and unreconciled debit and credit balances. The filing says the financial effect of several of those matters had not been ascertained.
What is the biggest quantified issue in McLeod Russel’s review?
The biggest quantified issue is the Rs 414.21 crore balance of inter-corporate deposits that remained unprovided at September 30, 2026. These deposits, including interest accrued up to March 31, 2019, aggregated to Rs 2,860.50 crore and had been provided for by Rs 2,446.29 crore in earlier years. Lodha & Co LLP described the remaining balance as doubtful of recovery and said its recoverability was prejudicial to McLeod Russel’s interests.
The reviewer said that without determining any shortfall and recording a provision against the remaining Rs 414.21 crore, the profit for the September 2026 period was overstated to that extent. Management had not ascertained or recognised that impact in the standalone results. The report also said the predecessor auditor’s concerns from the year ended March 31, 2019 continued, including questions over whether certain promoter companies could in substance be related parties and whether certain deposits were book entries.
The filing also refers to an advance of Rs 14 crore to a body corporate that was subsequently fully provided for, while saying appropriate audit evidence was not available during the earlier audit. It states that the status of the deposits and the related uncertainty over their utilisation and recoverability had remained unchanged after March 31, 2019. The matter was under examination before regulatory and judicial authorities as of November 14, 2026.
How do debt and unrecorded interest affect McLeod Russel’s numbers?
Debt-related adjustments remain uncertain because the restructuring arrangements disclosed in the September 2026 results are subject to conditions precedent and confirmations. McLeod Russel gave effect to adjustments under a master restructuring agreement with National Asset Reconstruction Company Limited and a one-time settlement with J.C. Flowers Asset Reconstruction Co. Pvt. Ltd. The reviewer said implementation depends on fulfilment of the conditions attached to the resolution and settlement arrangements.
McLeod Russel had also not recognised interest on loans, inter-corporate deposits and other amounts it had taken, which the reviewer said overstated profit for the period by the amount described in Note 9(a). The company had not determined the amount that may be converted to equity share capital, related interest or resulting adjustments because relevant terms and conditions for loans, advances and liabilities were unavailable. Penal or compound interest and other adjustments relating to a bank and inter-corporate deposits were also unrecognised pending confirmation and reconciliation.
Reported borrowings increased between March 31, 2026 and September 30, 2026, although those balances do not settle the reviewer’s concerns about the final payable amounts. Current borrowings were Rs 794 crore at September 30, compared with Rs 783.10 crore at March 31, while non-current borrowings rose to Rs 575.34 crore from Rs 551.57 crore. The filing says the amount payable to the lender bank and other parties remains subject to confirmation and the resulting impacts cannot yet be commented upon.
Got a follow-up? Ask IRIS
What did McLeod Russel report for the September quarter?
McLeod Russel reported standalone revenue from operations of Rs 391.93 crore for the quarter ended September 30, 2026, up from Rs 324.17 crore a year earlier, and reported profit for the period of Rs 34.38 crore, compared with Rs 29.19 crore. Total income rose to Rs 392.71 crore from Rs 324.38 crore. Those reported figures sit alongside the reviewer’s conclusion that the results were not fairly prepared in all material respects.
For the six months ended September 30, 2026, revenue from operations increased to Rs 596.36 crore from Rs 492.20 crore in the corresponding six months of 2025. McLeod Russel reported a Rs 19 crore profit for that half year, compared with a Rs 10.94 crore loss a year earlier. Finance costs fell to Rs 54.02 crore from Rs 83.20 crore, but the reviewer specifically identified unrecognised interest and said the total impact on profit had not been determined.
The September quarter also improved from the June 2026 quarter on the reported basis. Revenue increased from Rs 204.45 crore in June to Rs 391.93 crore in September, while the result changed from a Rs 14.78 crore loss to a Rs 34.38 crore profit. Employee-benefit expense rose to Rs 233.84 crore from Rs 203.73 crore, while inventory changes reduced expenses by Rs 40.29 crore in September compared with a Rs 130.98 crore reduction in June.
Can McLeod Russel continue as a going concern?
McLeod Russel prepared its September 2026 standalone results on a going-concern basis, but the reviewer said this depends on implementing restructuring conditions and obtaining approval for a debt-settlement proposal pending with a lender bank. The filing says current liabilities exceeded current assets and operational losses in earlier periods significantly affected net worth. It also says loans to promoter-group and other entities had mostly been used to financially support a promoter-group company whose resolution plan was approved by the National Company Law Tribunal, Kolkata.
Management’s stated basis is that sustainable debt will be repaid over the stipulated period and conditions under the restructuring agreement and settlement will be met. Debt assigned to asset reconstruction companies is expected to be repaid through promoter contribution, asset monetisation and operating cash flows under company projections. The filing adds that the lender bank had agreed in principle to McLeod Russel’s proposal and that employee, statutory and other liabilities, including amounts demanded by ATEPF authorities, had been restructured for payment over time.
The reviewer said the going-concern assumption presupposes sufficient asset-monetisation proceeds and future operating cash flow to meet obligations. If those expectations prove infeasible, it could affect the validity of the assumption and the carrying value of tangible and intangible assets, though the reviewer could not quantify that effect. Separate September 2026 issues include the undetermined fair value and possible impairment of property, plant and equipment, capital work in progress, intangible assets under development and investment in a subsidiary.
Conclusion
The November 14, 2026 filing shows that McLeod Russel reported higher September-quarter revenue and a reported profit, but Lodha & Co LLP concluded its standalone results were not prepared fairly in all material respects. The Rs 414.21 crore unprovided balance of doubtful inter-corporate deposits is the largest quantified matter, alongside unmeasured effects from interest, liabilities, asset valuation, taxes and reconciliations.
What to watch next is whether McLeod Russel fulfils conditions under its National Asset Reconstruction Company Limited restructuring and J.C. Flowers Asset Reconstruction Co. Pvt. Ltd. settlement, and whether its lender-bank debt proposal receives approval. The filing also says adjustments relating to the sale of specified tea-estate assets will be recorded when that transaction concludes in a subsequent period.