










McLeod Russel carries Rs 414.21 crore of unprovided ICDs
Key highlights
- McLeod Russel reported gross ICDs of Rs 2,761.09 crore at September 30, 2026.
- McLeod Russel carried Rs 414.21 crore of ICDs after stating provisions of Rs 2,446.29 crore.
- McLeod Russel recognised Rs 1,435.90 crore of ICD provisions during the year ended March 31, 2026.
- McLeod Russel reported six-month revenue of Rs 596.36 crore, compared with Rs 492.20 crore a year earlier.
powered by IRIS
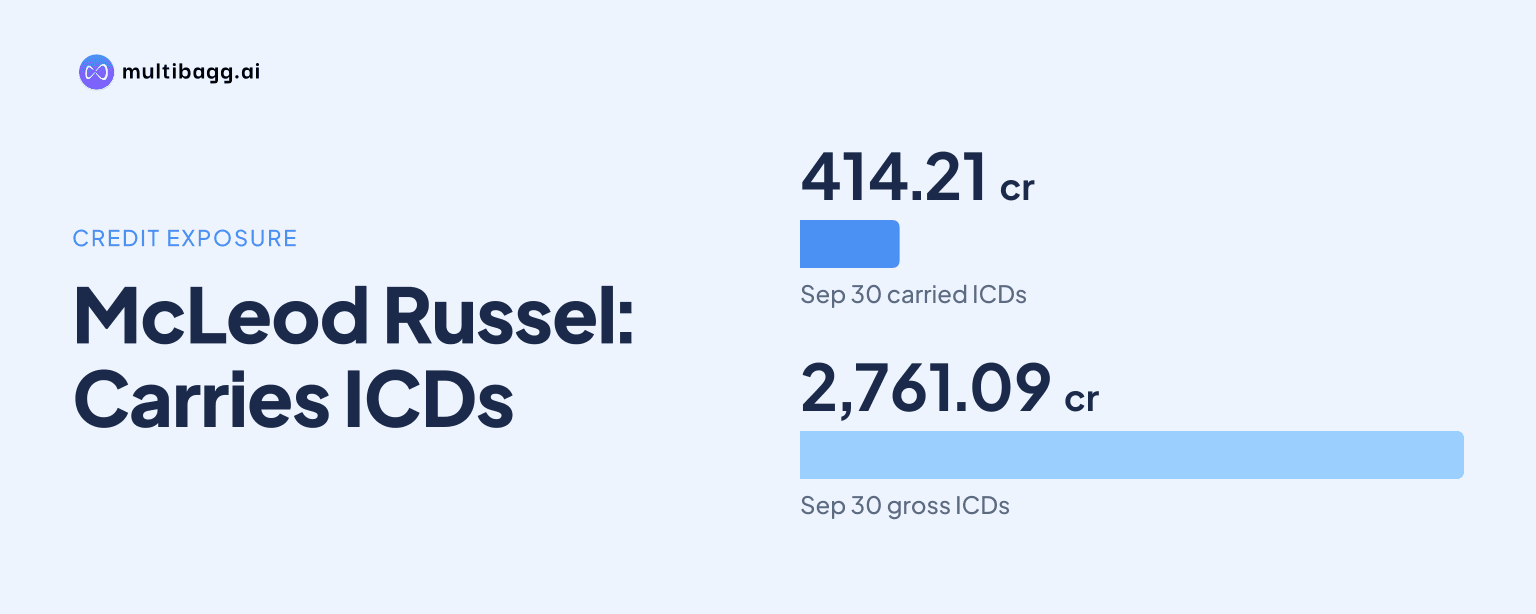
McLeod Russel India Limited carried Rs 414.21 crore of inter-corporate deposits, or ICDs, without provision at September 30, 2026, after reporting Rs 2,446.29 crore of provisions against Rs 2,761.09 crore in outstanding deposits. McLeod Russel said the final recoverable amount cannot currently be determined while legal recovery steps continue.
Know Mcleod Russel India inside out
Results, valuation, peers and who's buying, in one view.
What ICD balance remains on McLeod Russel's books?
McLeod Russel reported gross ICDs of Rs 2,761.09 crore at September 30, 2026 and carried forward Rs 414.21 crore after recognising provisions in earlier years. The deposits were made to promoter-group and certain other entities, described in the filing as borrowing companies. The company also disclosed Rs 99.41 crore of interest accrued on these deposits up to March 31, 2019.
McLeod Russel has not accrued further interest on the ICDs since April 1, 2013. It cited waiver requests from borrowing companies in earlier years, uncertainty over recovery and uncertainty in determining the interest amount. The Rs 99.41 crore accrued interest is separately disclosed from the Rs 2,761.09 crore deposit principal.
McLeod Russel’s notes contain a second provision figure that differs from the ICD note. A later note says Rs 2,346.75 crore had been provided against the Rs 2,761.09 crore loans at September 30, 2026, compared with Rs 2,446.29 crore in the ICD note. The filing does not explain the Rs 99.54 crore difference or reconcile that figure with the stated Rs 414.21 crore balance.
How did McLeod Russel's ICDs become difficult to recover?
McLeod Russel said the borrowing companies had onward advanced the deposited amounts to promoter-group and other entities, mainly to provide financial support to another promoter-group company. Corporate Insolvency Resolution Process, or CIRP, proceedings were subsequently initiated against that recipient company under the Insolvency and Bankruptcy Code, 2016.
McLeod Russel said the borrowing companies’ advances to the CIRP company became irrecoverable under a resolution plan approved by the National Company Law Tribunal, Kolkata. Because the borrowing companies had used the ICD funds for those advances, their inability to recover the onward loans affected recovery of McLeod Russel’s deposits.
The company recognised Rs 1,435.90 crore of the Rs 2,446.29 crore provision during the year ended March 31, 2026. That means the cited provision charge was concentrated in the year ended March 2026 rather than in the six months ended September 30, 2026. McLeod Russel retained the Rs 414.21 crore balance pending the outcome of its recovery efforts.
What recovery action is McLeod Russel taking on the deposits?
McLeod Russel said it is taking legal and other steps to recover the ICDs and has filed a legal suit before the Calcutta High Court against certain promoter-group entities. The September 30, 2026 filing does not quantify any recovery obtained through the suit or specify a timetable for a court outcome.
The company said any eventual recovery remains uncertain and that consequential accounting adjustments will be made when recoverability is determined on a case-by-case basis. Its disclosure preserves its legal right to pursue recovery but does not state that the remaining Rs 414.21 crore will be collected.
McLeod Russel also disclosed that predecessor auditors issued an adverse opinion on its financial statements for the year ended March 31, 2019. Those auditors reported that certain ICD amounts were in the nature of book entries and could not ascertain the applicability of Sections 185 and 186 of the Companies Act, 2013, or potential non-compliances for specified group-company loans.
Issues including the use of the loan amounts have been examined by relevant authorities, McLeod Russel said, and certain cases remained sub judice at September 30, 2026. The company said it had supplied requested replies, information and details, while final outcomes or directions were still awaited. These proceedings add to the unresolved factors affecting the ICD assessment.
Got a follow-up? Ask IRIS
How does the ICD exposure compare with McLeod Russel's recent results?
McLeod Russel’s Rs 414.21 crore unprovided ICD balance was substantially larger than its Rs 34.38 crore profit for the quarter ended September 30, 2026. Revenue from operations rose to Rs 391.93 crore in that quarter from Rs 324.17 crore a year earlier, while profit for the period increased from Rs 29.19 crore.
For the six months ended September 30, 2026, McLeod Russel reported revenue from operations of Rs 596.36 crore, compared with Rs 492.20 crore in the corresponding 2025 period. Profit for the six-month period was Rs 19 crore, compared with a loss of Rs 10.94 crore a year earlier. The company has one operating segment, cultivation, manufacture and sale of tea.
McLeod Russel cautioned that tea cultivation, manufacture and sales are seasonal, and said the September 2026 quarter and six-month figures should not be construed as indicative of results for the year ending March 31, 2027. The operating improvement therefore does not establish the final value recoverable from the ICD balance.
How does debt restructuring affect McLeod Russel's position?
McLeod Russel said National Asset Restructuring Company Limited, or NARCL, approved its resolution plan on April 2, 2026, and the Master Restructuring Agreement was executed on September 29, 2026. The NARCL arrangement covers sustainable debt of Rs 1,050 crore, after repayment of Rs 27.42 crore by March 31, 2026, payable over three years through promoter contributions, asset monetisation, operational accruals and other sources.
McLeod Russel also reached a one-time settlement with J C Flower Asset Restructuring, or JCAF, for sustainable debt of Rs 150 crore, after repayment of Rs 0.62 crore by March 31, 2026. The JCAF sustainable debt is payable over 15 months, including through monetisation of assets. Both arrangements are separate from recovery of the ICDs.
The Master Restructuring Agreement and the JCAF settlement remain subject to conditions precedent, including specified compliance and approvals. McLeod Russel said a default in payments or fulfilment of conditions could revoke the agreed restructuring and restore amounts payable under original terms. Management said it expects the stipulated conditions to be fulfilled within the required periods.
Conclusion
McLeod Russel has provided for most of its Rs 2,761.09 crore ICD exposure after the borrowing companies’ onward advances to another promoter-group company became irrecoverable in CIRP. Yet Rs 414.21 crore remains carried without provision, while the eventual recovery value, court proceedings and authority examinations remain unresolved. The filing also presents two unreconciled provision figures, Rs 2,446.29 crore and Rs 2,346.75 crore.
The next disclosures to watch are progress on the Calcutta High Court recovery suit and any determination of the final recoverable ICD amount. McLeod Russel also needs to meet conditions precedent under the NARCL restructuring and JCAF settlement, including asset monetisation, promoter contributions and other approvals, because the company says non-compliance could revoke the restructuring arrangements.