










Metal Formed Products Division FCF fell to zero in Q2
Key highlights
- Metal Formed Products Division FCF fell to zero in Q2 FY27 from Rs 47 crore in Q2 FY26.
- Metal Formed Products Division revenue rose to Rs 473 crore in Q2 FY27 from Rs 408 crore a year earlier.
- Metal Formed Products Division reported negative FCF of Rs 26 crore in YTD FY27, versus positive FCF of Rs 66 crore in YTD FY26.
- Metal Formed Products Division YTD FY27 ROCE declined to 37% from 43% in YTD FY26.
powered by IRIS
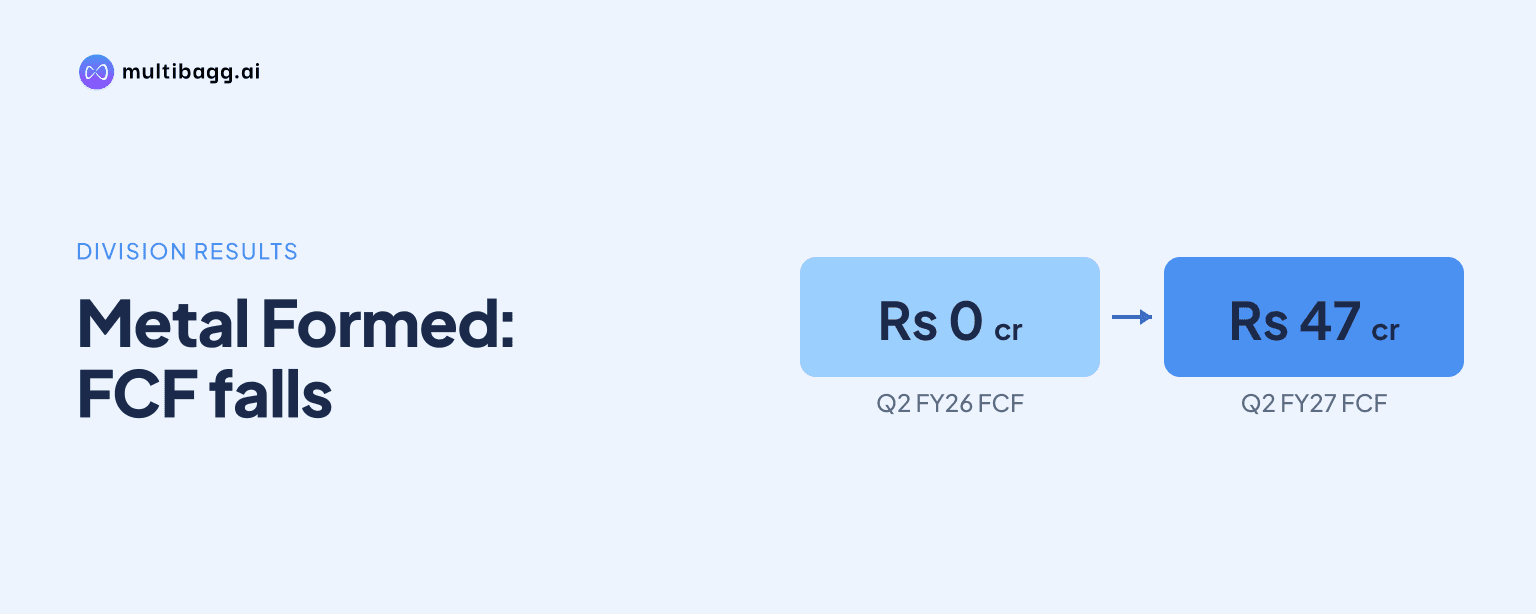
Tube Investments of India Limited’s Metal Formed Products Division reported zero free cash flow in Q2 FY27 despite revenue increasing to Rs 473 crore from Rs 408 crore a year earlier. Profit before interest and tax rose to Rs 49 crore, but PBIT margin fell to 10%, while first-half free cash flow was negative Rs 26 crore.
Know Tube Investments of India inside out
Results, valuation, peers and who's buying, in one view.
What happened to Metal Formed Products Division cash flow in Q2 FY27?
Metal Formed Products Division generated zero free cash flow, or FCF, in Q2 FY27, compared with Rs 47 crore in Q2 FY26. The presentation reports the result alongside quarterly revenue of Rs 473 crore and PBIT, or profit before interest and tax, of Rs 49 crore. It does not identify operating cash flow, working capital, capital expenditure or other factors behind the reduction in FCF.
The year-to-date result also moved lower. Metal Formed Products Division reported negative FCF of Rs 26 crore in YTD FY27, compared with positive FCF of Rs 66 crore in YTD FY26, a change of Rs 92 crore. The division recorded Rs 881 crore of revenue in YTD FY27, showing that the negative first-half FCF result coincided with higher cumulative sales.
Did Metal Formed Products Division revenue grow in Q2 FY27?
Yes. Metal Formed Products Division revenue increased by Rs 65 crore to Rs 473 crore in Q2 FY27 from Rs 408 crore in Q2 FY26. The quarterly revenue increase occurred while FCF moved from Rs 47 crore to zero. The presentation does not provide a split of the revenue change by product, customer, geography or manufacturing site.
For YTD FY27, revenue rose by Rs 107 crore to Rs 881 crore from Rs 774 crore in YTD FY26. Metal Formed Products Division lists auto kits under the Rombo and Diamond brands, auto chains, doorframes, fine-blanked products and railway coach parts among its products. Its manufacturing locations include Ambattur, Kakkalur, Tiruninravur and Hosur in Tamil Nadu, as well as Bawal, Laksar, Sanand, Medak and Pune.
The first-half profit comparison differed from the revenue trend. Q2 FY27 PBIT increased by Rs 5 crore to Rs 49 crore from Rs 44 crore, whereas YTD PBIT decreased by Rs 4 crore to Rs 77 crore from Rs 81 crore. Thus, the Rs 107 crore increase in YTD revenue was accompanied by lower cumulative PBIT in the figures reported by Metal Formed Products Division.
How did Metal Formed Products Division margins and returns change?
Metal Formed Products Division’s PBIT margin declined by 1 percentage point to 10% in Q2 FY27 from 11% in Q2 FY26. PBIT nevertheless increased to Rs 49 crore because quarterly revenue reached Rs 473 crore. The presentation does not explain the 1-percentage-point change in the reported quarterly margin.
The year-to-date PBIT margin also fell by 1 percentage point, to 9% in YTD FY27 from 10% in YTD FY26. This decline accompanied YTD PBIT of Rs 77 crore, below Rs 81 crore a year earlier, despite revenue rising to Rs 881 crore. The reported data therefore show margin reductions in both the Q2 and YTD comparisons.
Return on capital employed, or ROCE, also declined. Metal Formed Products Division reported ROCE of 45% in Q2 FY27 against 48% in Q2 FY26, while YTD ROCE was 37% against 43%. The 6-percentage-point YTD change was larger than the 1-percentage-point YTD PBIT-margin decline, although the presentation does not disclose the capital-employed balance or the calculation inputs.
Got a follow-up? Ask IRIS
What products and operations does Metal Formed Products Division have?
Metal Formed Products Division operates in drives and transmission, precision parts, roll form and large mechanical sections. Its listed products include cam chains, aftermarket brands, doorframes, side-impact beams, cowl cross beams, railway products and fine-blanked products. The division describes itself as India’s market leader for automatic chains and a preferred supplier of roll-formed car doorframes in India.
Metal Formed Products Division cites automotive drive-chain and cam-chain capabilities, just-in-time service and last-mile customer connectivity. It also lists high-speed presses and fine-blanking processes for close-tolerance components, as well as robotic automation and high-precision fabrication for railway applications. The presentation assigns no FY27 revenue, PBIT or FCF amount separately to automotive and railway products.
The presentation lists four recognitions across the division’s business units. Bajaj Auto Limited gave a quality award to the Chains business unit, Hyundai Motors India gave a partnership award to the Auto business unit, and Brose recognised the Fine Blanking unit’s contribution to gear-segment development. BorgWarner also recognised the Fine Blanking unit for its highest-ever supply of VCT parts, but the presentation gives no order value, supply volume or date.
How do the first-half results compare with the Q2 result?
Metal Formed Products Division’s Q2 FY27 PBIT was Rs 49 crore, Rs 5 crore above Q2 FY26, but YTD PBIT was Rs 77 crore, Rs 4 crore below YTD FY26. This contrast means the division’s first-half performance included a period before Q2 that reduced the cumulative PBIT outcome despite the higher Q2 figure. The source does not separately provide Q1 FY27 revenue, PBIT or FCF.
Cash flow showed a similar difference between current-quarter and cumulative figures. Q2 FY27 FCF was zero, while YTD FY27 FCF was negative Rs 26 crore; the equivalent FY26 figures were Rs 47 crore and Rs 66 crore respectively. The negative YTD figure indicates that the first-half total included a cash outflow even though the presentation does not provide a quarter-by-quarter bridge.
The ROCE comparison also widened on a cumulative basis. Q2 ROCE fell by 3 percentage points to 45%, while YTD ROCE fell by 6 percentage points to 37%. Metal Formed Products Division reports these returns together with a 1-percentage-point decline in both Q2 and YTD PBIT margin, without disclosing the underlying capital or cash-flow movements.
Conclusion
Metal Formed Products Division’s Q2 FY27 figures show higher revenue and PBIT alongside lower cash generation and margins. Revenue increased by Rs 65 crore to Rs 473 crore and PBIT rose by Rs 5 crore to Rs 49 crore, but FCF fell by Rs 47 crore to zero. For YTD FY27, revenue reached Rs 881 crore while PBIT fell to Rs 77 crore, FCF turned negative Rs 26 crore and ROCE declined to 37%.
What to watch next is the unresolved reason for the cash-flow movement. The presentation does not disclose a working-capital, capital-expenditure or operating-cash-flow bridge for the change from Rs 66 crore of YTD FY26 FCF to negative Rs 26 crore in YTD FY27, nor does it disclose a target or plan for FCF, PBIT margin or ROCE.