










Motherson margins hold as mature division revenue growth slows
Key highlights
- Modules and Polymer Products lifted H1FY27 EBITDA margin to 7.6% from 6.9% as revenue grew 7% to Rs 32,651 crore.
- Vision Systems held a 9.2% EBITDA margin in H1FY27 while revenue increased 8% to Rs 11,072 crore.
- Integrated Assemblies raised H1FY27 EBITDA margin to 12.5% from 11.8% despite revenue growth of 4%.
- Modules and Polymer Products’ Q2FY27 margin rose to 8.3% from 7.4%, supported by approximately 90 basis points of year-on-year improvement.
powered by IRIS
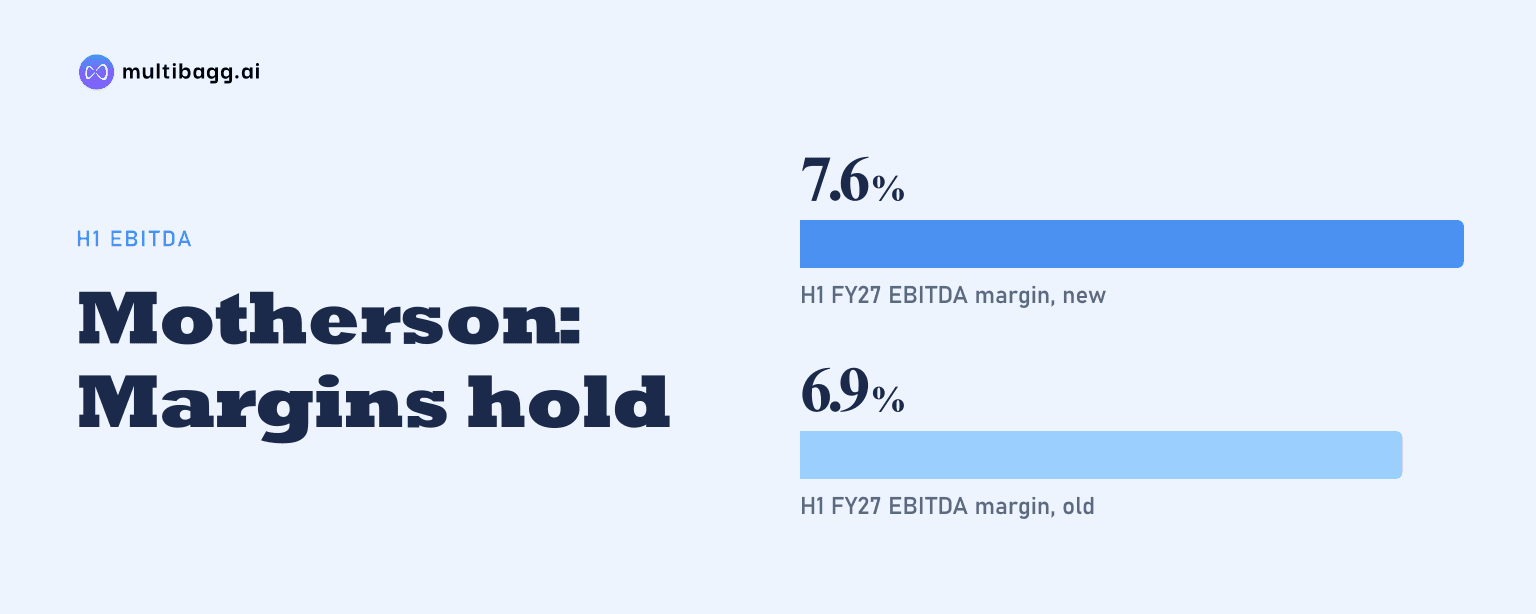
Motherson’s Modules and Polymer Products, Vision Systems and Integrated Assemblies held or increased profitability in H1FY27 despite revenue growth of 4% to 8%, with Integrated Assemblies lifting EBITDA margin to 12.5% from 11.8% and Modules and Polymer Products reaching 7.6% from 6.9%.
Know Samvardhana Motherson International inside out
Results, valuation, peers and who's buying, in one view.
How did Motherson’s mature divisions perform in H1FY27?
Motherson’s three mature divisions reported EBITDA growth that equalled or exceeded sales growth in H1FY27. Earnings before interest, tax, depreciation and amortisation, or EBITDA, at Modules and Polymer Products increased 18% to Rs 2,468 crore as revenue grew 7% to Rs 32,651 crore. Vision Systems revenue and EBITDA each rose 8%, to Rs 11,072 crore and Rs 1,019 crore respectively, while Integrated Assemblies EBITDA rose 10% to Rs 697 crore on 4% revenue growth to Rs 5,599 crore.
The margin outcome differed from Motherson’s faster-growing Wiring Harness and Emerging Businesses divisions. Wiring Harness revenue grew 49% in H1FY27 to Rs 25,662 crore, but its EBITDA margin declined to 10.5% from 10.9%. Emerging Businesses revenue increased 46% to Rs 11,248 crore while its margin fell to 8.4% from 8.9%, whereas the three mature divisions maintained or improved their margins.
The divisional figures include 100% of joint ventures and associates accounted for under the equity method, which Motherson calls economic revenue. On that basis, group revenue was Rs 83,547 crore in H1FY27 and EBITDA was Rs 7,844 crore, with a 9.4% margin. Reported revenue, after the joint-venture adjustment, was Rs 73,524 crore and reported EBITDA margin was 8.8%, compared with 8.6% in H1FY26.
Why did Modules and Polymer Products improve its margin despite muted demand?
Modules and Polymer Products increased its Q2FY27 EBITDA margin to 8.3% from 7.4% in Q2FY26 while revenue rose 4% to Rs 15,956 crore. Motherson said ongoing transformation and cost-efficiency initiatives in Europe supported an approximately 90-basis-point year-on-year margin improvement. A basis point is one-hundredth of a percentage point. The company also cited cost optimisation aimed at mitigating input-cost pressures.
The second-quarter result improved on the Q1FY27 margin of 6.9%, even though quarterly revenue fell from Rs 16,695 crore in Q1FY27 to Rs 15,956 crore in Q2FY27. EBITDA rose from Rs 1,144 crore to Rs 1,324 crore over the same quarters. Motherson said continued weakness in key markets weighed on performance, while expansion into whitespace geographies, a broader product range and a larger customer base were its stated growth actions.
Europe represented 54% of Modules and Polymer Products revenue in H1FY27, followed by North America at 20%, India at 10%, the rest of the world at 10% and China at 6%. That regional mix makes the disclosed European transformation programme particularly relevant to the division’s Rs 32,651 crore half-year revenue base.
Got a follow-up? Ask IRIS
How did Vision Systems maintain its EBITDA margin?
Vision Systems maintained a 9.2% EBITDA margin in Q2FY27 and H1FY27, matching the corresponding prior-year periods despite seasonal softness in key markets. Q2FY27 revenue rose 7% year-on-year to Rs 5,418 crore, while EBITDA increased 6% to Rs 499 crore. Revenue was lower than Rs 5,654 crore in Q1FY27, and EBITDA was lower than Rs 520 crore, while the margin remained unchanged at 9.2%.
For H1FY27, Vision Systems revenue rose to Rs 11,072 crore from Rs 10,221 crore and EBITDA increased to Rs 1,019 crore from Rs 942 crore. Motherson said the division outpaced industry growth in a challenging environment and was pursuing operational efficiencies to sustain margin amid subdued conditions. Its growth plans include increasing content per vehicle, expanding its premium-product order book, onboarding customers and broadening its geographical presence.
Europe contributed 41% of Vision Systems revenue in H1FY27, ahead of North America at 19%, China at 18%, the rest of the world at 16% and India at 6%. The division therefore generated 94% of half-year revenue outside India while holding its 9.2% margin.
What protected Integrated Assemblies profitability during programme transitions?
Integrated Assemblies lifted its H1FY27 EBITDA margin by 70 basis points to 12.5% as EBITDA grew 10% to Rs 697 crore and revenue rose 4% to Rs 5,599 crore. Motherson said cost optimisation and automation initiatives were directed at operational execution and margin sustainability. The division’s 12.5% half-year margin was the highest among the three mature divisions covered.
Q2FY27 revenue was Rs 2,650 crore, up 3% from Rs 2,580 crore in Q2FY26 but below Rs 2,950 crore in Q1FY27. Motherson attributed the quarterly sales performance to demand softness in key markets and the transition from outgoing to new programmes. EBITDA rose 3% year-on-year to Rs 325 crore, while margin edged up to 12.3% from 12.2% and remained below Q1FY27’s 12.6%.
Europe accounted for 61% of Integrated Assemblies revenue in H1FY27 and North America contributed 27%, with China at 8% and the rest of the world at 4%. Motherson said a pipeline of upcoming programmes, along with customer-base and geographic expansion, was expected to support growth momentum after the programme transitions.
Conclusion
Motherson’s H1FY27 results show that margin movement was not determined solely by revenue growth. Modules and Polymer Products increased its margin by 70 basis points on 7% sales growth, Vision Systems held its 9.2% margin on 8% growth, and Integrated Assemblies increased margin by 70 basis points on 4% growth. The disclosed mechanisms were European transformation, operational efficiency, cost optimisation and automation.
The next points to watch are execution of Modules and Polymer Products’ expansion into new geographies and products, Vision Systems’ premium-product and customer initiatives, and the Integrated Assemblies pipeline of upcoming programmes. Motherson disclosed these plans but provided no revenue or margin target for the three divisions, leaving the conversion of those actions into growth unresolved.