










Mukka H1 FY27 revenue reaches Rs 998.5 crore as margin holds 9.9%
Key highlights
- Mukka reported H1 FY27 revenue from operations of Rs 998.5 crore, compared with Rs 415.4 crore in H1 FY26.
- Mukka's H1 FY27 EBITDA was Rs 98.7 crore and EBITDA margin was 9.9%, versus Rs 42.9 crore and 10.3% a year earlier.
- Mukka reported Q2 FY27 revenue of Rs 508.9 crore, EBITDA of Rs 50.1 crore and PAT of Rs 17.7 crore.
- Mukka's FY26 revenue from operations was Rs 1,403.60 crore, compared with Rs 980.00 crore in FY25.
powered by IRIS
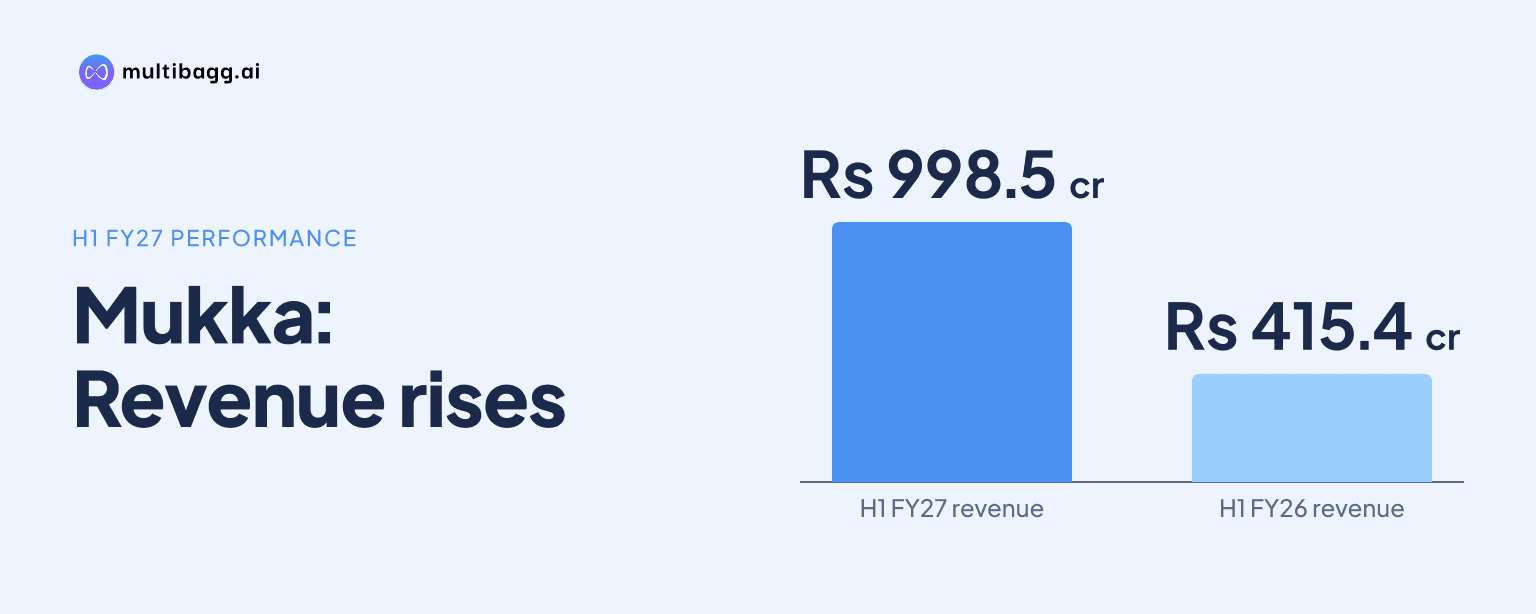
Mukka Proteins Limited reported consolidated H1 FY27 revenue from operations of Rs 998.5 crore, up from Rs 415.4 crore in H1 FY26, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin was 9.9%. Mukka attributed the increase to domestic and export demand, favourable fishmeal pricing and improved product realisations.
Know Mukka Proteins inside out
Results, valuation, peers and who's buying, in one view.
How did Mukka perform in H1 FY27?
Mukka reported H1 FY27 revenue from operations of Rs 998.5 crore and EBITDA of Rs 98.7 crore, compared with Rs 415.4 crore and Rs 42.9 crore, respectively, in H1 FY26. Revenue therefore increased by Rs 583.1 crore and EBITDA increased by Rs 55.8 crore over the prior-year half. Management said demand across domestic and export markets, favourable fishmeal pricing and improved product realisations supported the reported growth.
Mukka's EBITDA margin was 9.9% in H1 FY27, versus 10.3% in H1 FY26, a decrease of 0.4 percentage points despite the increase in absolute EBITDA. The H1 FY27 profit after tax (PAT) margin was 3.6%, compared with 2.0% in H1 FY26, when PAT was Rs 8.5 crore. Mukka did not disclose an absolute H1 FY27 PAT figure in the half-year financial summary.
The comparison shows that operating profit rose alongside sales, although the EBITDA margin was lower than in the preceding first half. EBITDA is a measure of earnings before interest, tax, depreciation and amortisation, while the 9.9% margin measures EBITDA as a share of revenue. Mukka's stated fishmeal pricing and product-realisation factors therefore coincided with higher sales and EBITDA in H1 FY27.
How did Mukka perform in Q2 FY27?
Mukka reported Q2 FY27 revenue of Rs 508.9 crore, EBITDA of Rs 50.1 crore and PAT of Rs 17.7 crore. Revenue was Rs 489.7 crore in Q1 FY27 and Rs 244.6 crore in Q2 FY26, meaning Q2 FY27 revenue was Rs 19.2 crore above the immediately preceding quarter and Rs 264.3 crore above the prior-year quarter. The H1 FY27 revenue total of Rs 998.5 crore equals the reported Q1 and Q2 revenue figures combined.
Mukka's Q2 FY27 EBITDA margin was 9.9%, unchanged from Q1 FY27, while Q2 FY26 margin was 10.7%. EBITDA increased from Rs 48.6 crore in Q1 FY27 to Rs 50.1 crore in Q2 FY27, and from Rs 26.3 crore in Q2 FY26. The sequential increase in EBITDA was Rs 1.5 crore, while the year-on-year increase was Rs 23.8 crore.
PAT was Rs 17.7 crore in Q2 FY27, compared with Rs 18.6 crore in Q1 FY27 and Rs 6.9 crore in Q2 FY26. PAT margin was 3.5% in Q2 FY27, below 3.8% in Q1 FY27 but above 2.8% in Q2 FY26. This means quarterly revenue and EBITDA increased sequentially, whereas PAT declined by Rs 0.9 crore from Q1 FY27.
Got a follow-up? Ask IRIS
What operational developments did Mukka disclose in Q2 FY27?
Mukka said its new Al Juba unit in Oman commenced commercial production of fishmeal, fish oil and soluble paste in Q2 FY27. The company said the unit expands production capability and strengthens its Middle East presence. Mukka did not disclose the facility's capacity, commissioning date, utilisation level or revenue contribution.
Mukka also disclosed United States Food and Drug Administration facility registration, which it said supports engagement with customers and markets requiring such registration. Separately, Eco Sphere Organic Fertilizer received a United States Department of Agriculture National Organic Program inputs attestation for organic-farming markets, including the United States. The company did not quantify sales arising from either the registration or the attestation.
The organic-inputs opportunity is separate from Mukka's fish-protein products. Mukka cited a U.S. organic-fertiliser market projected to reach US$2.30 billion by 2031 at an 11.5% compound annual growth rate. Its core fish-protein platform comprises fishmeal, fish oil and fish soluble paste, and Mukka estimated that it holds around 25% to 30% of Indian fish-protein exports.
Mukka described aquaculture as accounting for more than 90% of fish-protein end use, with fishmeal containing 60% to 65% protein. The Oman unit's production of three fish-protein products therefore relates to the same core product platform, while Eco Sphere Organic Fertilizer addresses a farming-input market. These developments are commercial access and production measures, not separately reported revenue segments.
How does H1 FY27 compare with Mukka's annual financial record?
Mukka reported FY26 revenue from operations of Rs 1,403.60 crore, compared with Rs 980.00 crore in FY25 and Rs 1,342.10 crore in FY24. Revenue fell by Rs 362.10 crore between FY24 and FY25, before increasing by Rs 423.60 crore in FY26. H1 FY27 revenue of Rs 998.5 crore was recorded against that FY26 full-year base, but Mukka did not disclose an FY27 revenue target.
Profit for the year was Rs 57.10 crore in FY26, compared with Rs 48.10 crore in FY25 and Rs 74.30 crore in FY24. Profit before tax followed a similar sequence, falling from Rs 84.40 crore in FY24 to Rs 59.20 crore in FY25, then increasing to Rs 73.10 crore in FY26. Finance costs rose from Rs 25.10 crore in FY24 to Rs 37.30 crore in FY25 and Rs 53.60 crore in FY26.
Mukka's FY26 total income was Rs 1,478.20 crore, comprising Rs 1,449.50 crore of total revenues from operations and Rs 28.70 crore of other income. The H1 FY27 result establishes a first-half revenue and EBITDA run rate, but it does not determine the full-year outcome because Mukka gave no FY27 guidance. The annual record also shows that revenue recovery in FY26 did not restore profit for the year to the FY24 level.
Conclusion
Mukka's H1 FY27 result combines revenue growth of Rs 583.1 crore year on year with EBITDA growth of Rs 55.8 crore, bringing reported revenue to Rs 998.5 crore and EBITDA to Rs 98.7 crore. The EBITDA margin was 9.9%, compared with 10.3% in H1 FY26, while PAT margin increased from 2.0% to 3.6%. Q2 FY27 maintained the same 9.9% EBITDA margin as Q1 FY27.
The next disclosed developments to watch are the commercial contribution of the Al Juba unit, which began production in Q2 FY27 without a stated capacity or revenue figure, and whether U.S. registration and organic-input attestation lead to customer engagement or sales. Mukka also reported Rs 495 crore of bank facilities rated CARE BBB-; Stable / CARE A3, with the outlook revised from Negative.