










Navin Fluorine Q2 sales rise 57% as EBITDA reaches Rs 407.5 crore
Key highlights
- Navin Fluorine reported Q2 FY27 sales of Rs 1,190.7 crore, up 57% year on year.
- Q2 FY27 operating EBITDA was Rs 407.5 crore, up 66% year on year, with a 34.2% margin.
- CDMO revenue increased 78% year on year to Rs 239 crore in Q2 FY27, the highest disclosed segment growth.
- Quarterly revenue rose from Rs 606 crore in Q3 FY25 to Rs 1,191 crore in Q2 FY27.
powered by IRIS
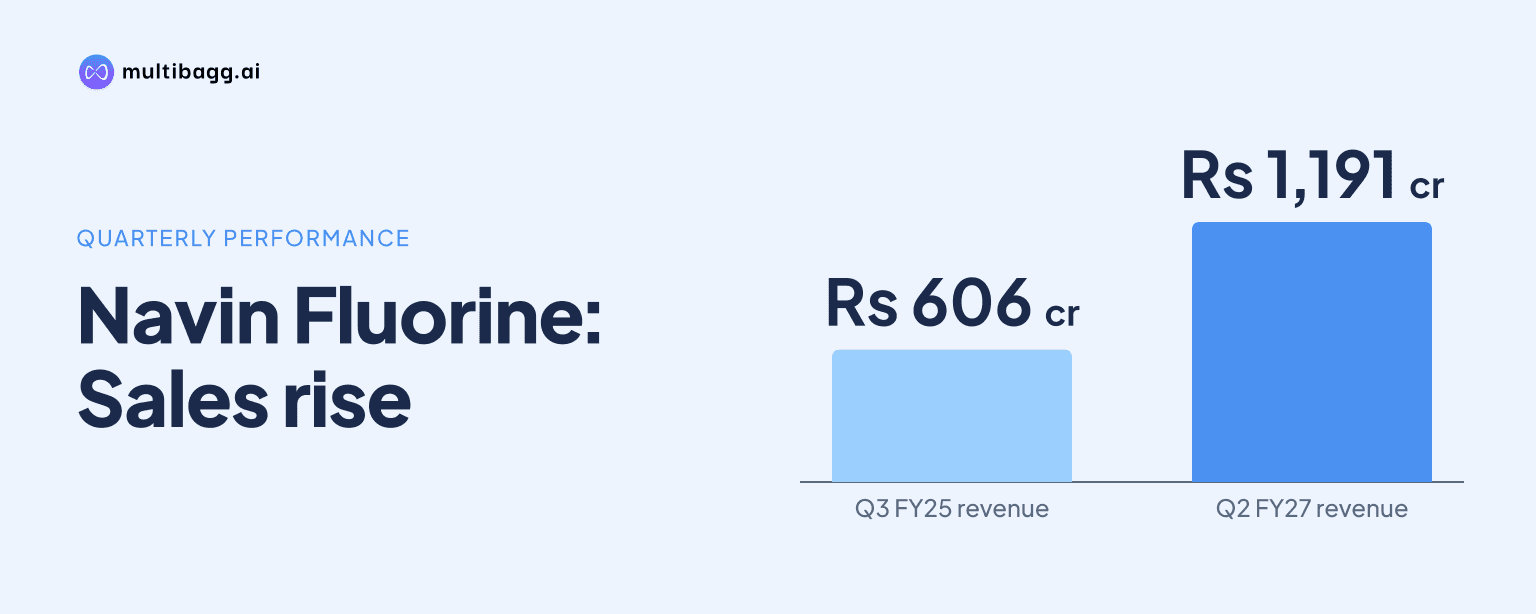
In Q2 FY27, Navin Fluorine International Limited reported consolidated sales of Rs 1,190.7 crore, up 57% year on year, and operating EBITDA of Rs 407.5 crore, up 66%. The reported operating EBITDA margin was 34.2%, while the company’s eight-quarter series shows revenue rising from Rs 606 crore in Q3 FY25 to Rs 1,191 crore.
Know Navin Fluorine International inside out
Results, valuation, peers and who's buying, in one view.
What did Navin Fluorine report in Q2 FY27?
Navin Fluorine reported Q2 FY27 sales of Rs 1,190.7 crore, operating EBITDA of Rs 407.5 crore and operating profit before tax (PBT) of Rs 336.0 crore. Sales increased 57% year on year and 14% quarter on quarter, while operating PBT rose 87% year on year and 19% quarter on quarter.
The operating EBITDA margin was 34.2%, up 176 basis points year on year and 5 basis points quarter on quarter. A basis point is one-hundredth of a percentage point. The quarterly series reported profit after tax (PAT) of Rs 269 crore, compared with Rs 148 crore in Q2 FY26 and Rs 243 crore in Q1 FY27.
The Q2 FY27 highlights use more precise figures of Rs 1,190.7 crore for sales and Rs 407.5 crore for operating EBITDA, while the eight-quarter series rounds them to Rs 1,191 crore and Rs 407 crore. The highlights also state 141% quarter-on-quarter operating EBITDA growth, although the rounded series shows Rs 357 crore in Q1 FY27 and Rs 407 crore in Q2 FY27.
How did Navin Fluorine perform in the first half of FY27?
Navin Fluorine recorded H1 FY27 sales of Rs 2,235.8 crore, up 51% year on year, and operating EBITDA of Rs 764.5 crore, up 69%. Operating PBT reached Rs 619.2 crore, up 93%, while the operating EBITDA margin was 34.2%, an increase of 367 basis points year on year.
All three disclosed verticals reported higher H1 FY27 revenue. High Performance Products, or HPP, generated Rs 1,144 crore and grew 41%; Specialty generated Rs 673 crore and grew 53%; and contract development and manufacturing organisation, or CDMO, revenue was Rs 419 crore and grew 80%.
CDMO had the highest reported H1 growth rate at 80%, while HPP was the largest revenue vertical at Rs 1,144 crore. Q2 FY27 sales of Rs 1,190.7 crore were above the Rs 1,117.9 crore implied midpoint of reported H1 FY27 sales, following Q1 FY27 sales of Rs 1,045 crore in the company’s rounded quarterly series.
Which Navin Fluorine segments drove Q2 FY27 revenue?
Navin Fluorine’s HPP vertical was the largest Q2 FY27 contributor, reporting Rs 604 crore of revenue, up 49% from Rs 404 crore in Q2 FY26. Management attributed HPP growth to higher volumes and improved realisations, and said the hydrofluorocarbon, or HFC, pricing environment remained firm with a quarter-on-quarter rise in realisation.
Specialty revenue was Rs 348 crore, up 58% from Rs 220 crore a year earlier. Management said the vertical had order visibility for the second half of FY27 and beyond, and that de-bottlenecking of multipurpose plant capacity at Dahej was commissioned in September 2026.
CDMO revenue rose 78% to Rs 239 crore from Rs 134 crore, the fastest growth among the three reported Q2 verticals. Management cited demand for an existing molecule, wider supply-chain participation and a qualification purchase order from a European CDMO major.
The three segment figures total Rs 1,191 crore on the presentation’s rounded basis, matching the rounded consolidated revenue series. HPP contributed Rs 604 crore, ahead of Specialty at Rs 348 crore and CDMO at Rs 239 crore, indicating that each reported vertical participated in the year-on-year increase.
Got a follow-up? Ask IRIS
Does Navin Fluorine’s eight-quarter series show sustained growth?
Navin Fluorine’s reported quarterly revenue increased in every one of the eight displayed periods, from Rs 606 crore in Q3 FY25 to Rs 1,191 crore in Q2 FY27. The intervening figures were Rs 701 crore, Rs 725 crore, Rs 758 crore, Rs 892 crore, Rs 938 crore and Rs 1,045 crore, respectively, from Q4 FY25 through Q1 FY27.
Operating EBITDA also rose in each displayed quarter, from Rs 147 crore in Q3 FY25 to Rs 407 crore in Q2 FY27. The series moved through Rs 179 crore, Rs 207 crore, Rs 246 crore, Rs 308 crore, Rs 321 crore and Rs 357 crore over the six intervening quarters.
Operating PBT increased from Rs 98 crore in Q3 FY25 to Rs 336 crore in Q2 FY27, while PAT increased from Rs 84 crore to Rs 269 crore. In the immediate comparison, revenue rose from Rs 1,045 crore in Q1 FY27 to Rs 1,191 crore in Q2 FY27, and PAT rose from Rs 243 crore to Rs 269 crore.
What milestones has Navin Fluorine disclosed for FY27?
Navin Fluorine said additional HFC capacity equivalent to up to 15,000 metric tonnes per annum of R32 was on track to be commissioned shortly. It also said its HFO supply contract with Solstice Advanced Materials US, Inc. was extended by four years beyond its original seven-year term, taking the contract period to 11 years.
In Specialty, management targeted completion of the Chemours project by the end of Q3 FY27 and said purchase orders were in place for delivery during Q4 FY27. In CDMO, phase II of the CGMP4 project, involving capital expenditure of Rs 125 crore, was on track to be operational by the end of Q4 FY27.
Navin Fluorine disclosed on November 13, 2026 that company officials would meet analysts and investors at the JM Financial Annual India Conference - India Xchange 2026 on November 18, 2026. The company said discussions would be based on publicly available information and that the schedule could change due to host or company exigencies.
Conclusion
Navin Fluorine’s Q2 FY27 figures show higher sales, operating EBITDA, operating PBT and PAT versus both Q2 FY26 and Q1 FY27 in the rounded series. Revenue growth came from HPP, Specialty and CDMO, while the eight displayed quarters show a sequential rise in each of the four financial measures tracked by the presentation.
The next disclosed items to watch are the commissioning of up to 15,000 metric tonnes per annum of R32 capacity, the targeted end-Q3 FY27 completion of the Chemours project and the targeted end-Q4 FY27 operationalisation of CDMO phase II CGMP4. Management’s stated order visibility, purchase orders and project delivery schedules provide the identified milestones for subsequent updates.