










NDL Ventures Limited sets 25-for-10 HLFL share swap terms
Key highlights
- NDL will issue 25 fully paid Rs 10 shares for every 10 HLFL shares under the scheme.
- NDL shareholders approved the scheme by 99.99% in value on 30 July 2026.
- HLFL shareholders approved the merger by 100% in value and number among participants.
- NDL’s three unsecured creditors with Rs 8.77159 lakh outstanding as of 31 March 2026 were paid and issued no-dues certificates.
powered by IRIS
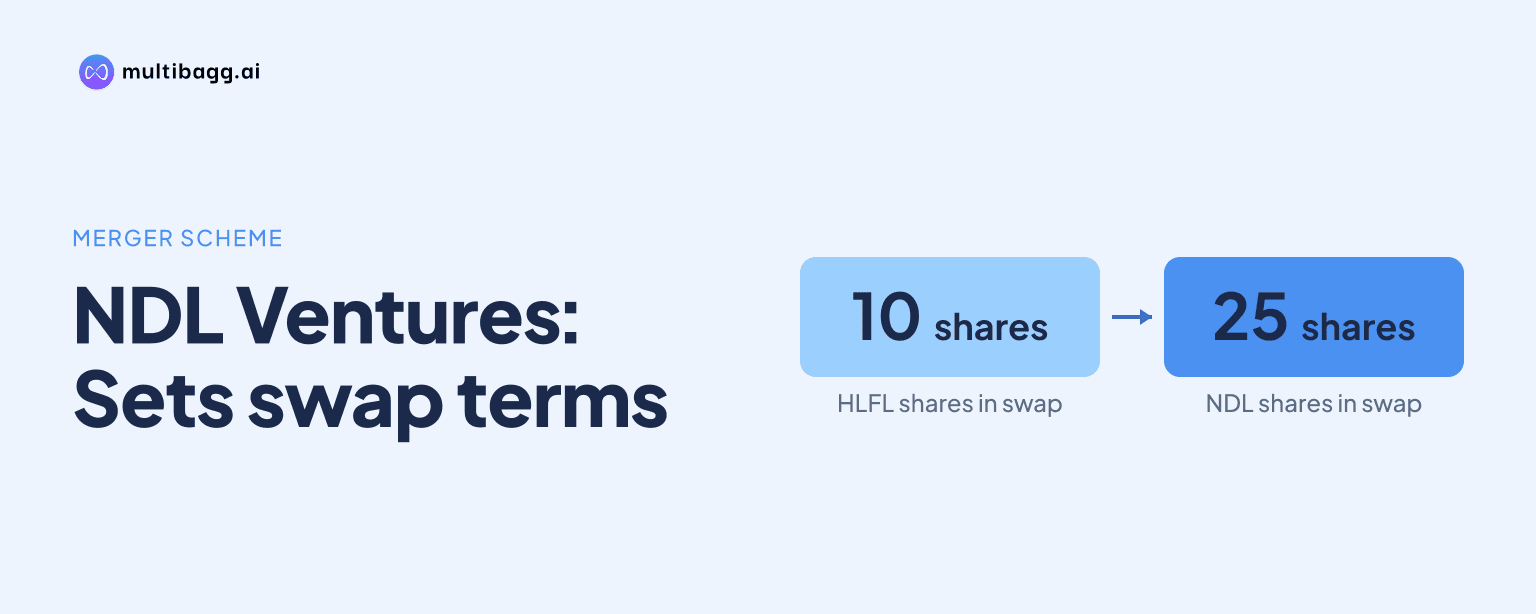
NDL Ventures Limited will issue 25 fully paid equity shares for every 10 shares of Hinduja Leyland Finance Limited under the tribunal-sanctioned merger, with NDL shareholders representing 99.99% of value approving the scheme on 30 July 2026. The scheme’s appointed date is 1 April 2026, while the record date has not been disclosed.
Know NDL Ventures inside out
Results, valuation, peers and who's buying, in one view.
What will HLFL shareholders receive in the NDL merger?
HLFL shareholders recorded in the register of members on the record date will receive 25 NDL equity shares for every 10 fully paid HLFL equity shares. Each new NDL share will have a face value of Rs 10 and be fully paid, matching the Rs 10 face value of each HLFL share covered by the exchange ratio.
The stated consideration is a 25-for-10 share exchange, which equates to 2.5 NDL shares for each HLFL share. The scheme says NDL will allot the shares once it comes into effect, without further application, act or deed by eligible shareholders, including successors, heirs, executors or administrators recognised by NDL’s board.
The scheme calls the shares allotted by NDL “New Equity Shares” and provides share consideration rather than cash for the merger by absorption. The tribunal order does not state the record date, total number of New Equity Shares, post-merger ownership percentages or an implied value for an HLFL share.
How did NDL and HLFL stakeholders vote on the scheme?
Shareholders and creditors approved the scheme by margins ranging from 97.87% to 100% at meetings held on 30 July 2026. The National Company Law Tribunal, Mumbai Bench-I had directed the companies to convene the meetings in its 17 June 2026 order.
NDL equity shareholders approved the scheme with 99.99% support by value and 97.87% by number among those present and voting. HLFL equity shareholders approved it with 100% support both by value and number among those present and voting, meaning the transferor company’s participating shareholders gave unanimous support while NDL’s vote was not unanimous.
HLFL’s unsecured creditors approved the arrangement by 99.99% of participating creditors through remote e-voting and e-voting. NDL’s unsecured-creditor meeting was dispensed with after its three unsecured creditors, with aggregate outstanding dues of Rs 8.77159 lakh as of 31 March 2026, were paid in the ordinary course of business and issued no-dues certificates.
What does the tribunal sanction change for NDL and HLFL?
The tribunal made the merger petition absolute, making the scheme binding on NDL, HLFL, their shareholders, creditors, employees and other stakeholders. HLFL, identified as the transferor company, will be dissolved without winding up, while liabilities accruing in HLFL will transfer to NDL.
Both boards approved the scheme on 25 November 2025, and the appointed date is 1 April 2026. The transaction is structured as an absorption of HLFL into NDL, the transferee company, rather than a transaction in which both companies continue as separate entities after implementation.
The tribunal found that the scheme appeared fair and reasonable on the material before it, did not violate law and was not contrary to public policy. It also recorded that no other statutory or regulatory authority, creditor, member or stakeholder had objected, after the Regional Director’s authorised representative said on 1 October 2026 that there was no objection to consideration of the scheme.
Got a follow-up? Ask IRIS
What regulatory and accounting matters remain relevant after sanction?
Tax authorities retain the right to examine tax payable from the scheme and to take action if tax avoidance is found under income-tax law. In a joint affidavit dated 3 September 2026, NDL and HLFL said the merger was proposed for bona fide commercial reasons and that tax consequences would be governed by applicable provisions of the Income-tax Act.
The Regional Director, Western Region, Mumbai, made observations in a 29 September 2026 report, and NDL and HLFL responded on the same date with compliance undertakings. These include complying with Section 232(3)(i) of the Companies Act, 2013, applicable income-tax and goods and services tax requirements, and relevant accounting standards, including Accounting Standard 14 or Indian Accounting Standard 103 where applicable.
The Official Liquidator’s report dated 17 September 2026 raised observations regarding HLFL’s overdue loan portfolio, substantial near-term repayment obligations and valuations of certain loan assets classified as fair value through other comprehensive income. HLFL responded that expected credit loss provisions as of 31 March 2026 were adequate, the net loan assets fairly reflected realisable value, and an independent valuer had been engaged for identified loan assets.
Why are NDL and HLFL combining their businesses?
NDL and HLFL said the merger is intended to position NDL in the non-banking financial company, or NBFC, sector and provide HLFL with broader avenues to raise growth capital. NDL said it had amended its memorandum of association to reflect its intention to engage in NBFC business.
Management and the boards cited reduced duplication of administrative work, fewer legal and regulatory compliance processes, and integrated use of resources and costs among the intended benefits. They also said the merger could increase NDL’s net worth and enable more focused management control and governance required of a listed entity, but the order includes no financial forecasts or capital-raising target.
The filing states that neither company had pending proceedings or investigations under Sections 210 to 217 and Sections 219, 220, 223, 224, 225, 226 and 227 of the Companies Act, 2013. It also states there were no pending Insolvency and Bankruptcy Code proceedings or litigation with a material impact on the scheme as of the tribunal’s consideration.
Conclusion
The merger establishes a specific ownership exchange: HLFL shareholders are to receive 25 NDL shares for every 10 HLFL shares, while approval levels reached 100% among participating HLFL shareholders and 99.99% by value among participating NDL shareholders. The legal result is the transfer of HLFL’s business and liabilities to NDL and HLFL’s dissolution without winding up.
The next disclosed items to watch are the record date and confirmation that the scheme has taken effect, neither of which appears in the order. Implementation also remains subject to the companies’ undertakings on tax, accounting, creditor and sectoral-regulatory compliance, including the matters addressed in affidavits dated 3 September, 17 September and 29 September 2026.