










New India Assurance combined ratio rises to 156.2% as claims surge
Key highlights
- New India Assurance’s combined ratio rose to 156.20% in the September 2026 quarter from 139.77% a year earlier.
- Incurred claims increased by Rs 2,667.07 crore year on year to Rs 12,879.50 crore, exceeding premium earned of Rs 9,632.18 crore.
- The company’s underwriting loss widened to Rs 5,237.35 crore from Rs 3,554.36 crore in the prior-year quarter.
- New India Assurance’s solvency ratio declined to 1.61 as at September 30, 2026, from 1.79 a year earlier and 1.84 at March 31, 2026.
powered by IRIS
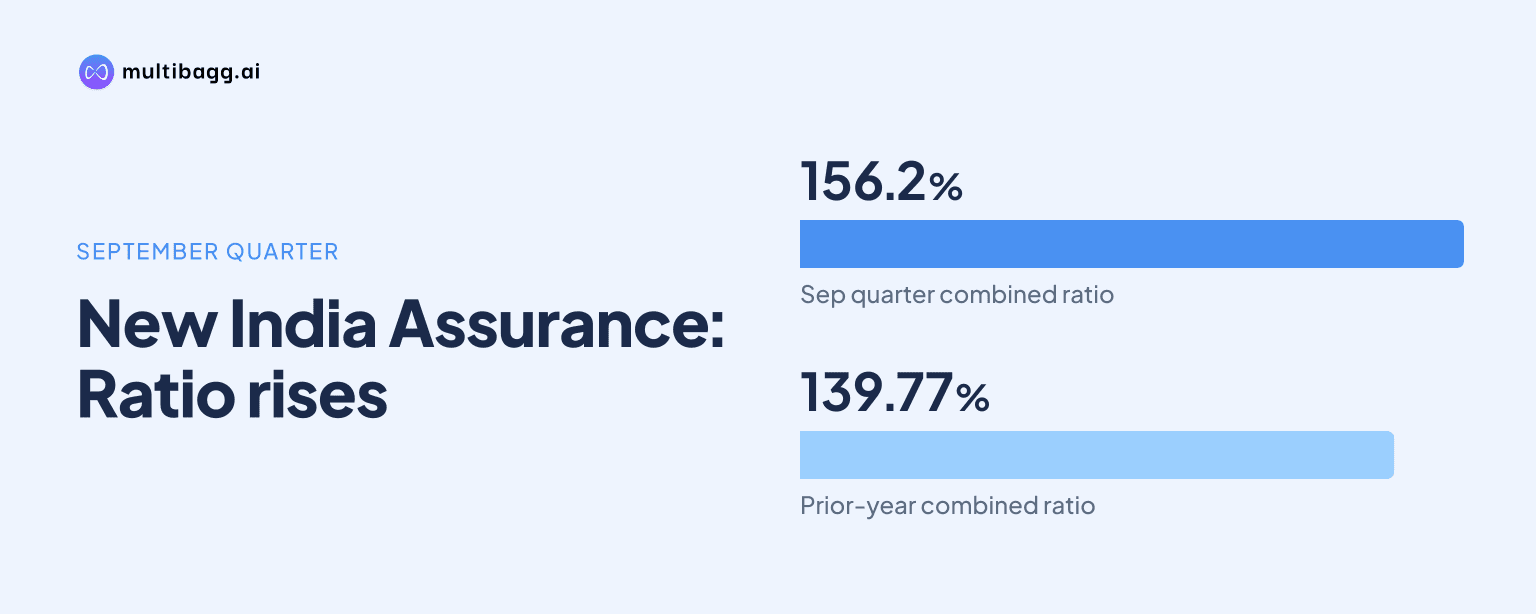
The New India Assurance Company Limited reported a 156.20% combined ratio for the quarter ended September 30, 2026, versus 139.77% a year earlier. New India Assurance’s incurred-claim ratio rose to 133.71% from 108.66% as incurred claims increased to Rs 12,879.50 crore, exceeding Rs 9,632.18 crore of premium earned.
Know New India Assurance Company inside out
Results, valuation, peers and who's buying, in one view.
Why did New India Assurance’s combined ratio rise to 156.2%?
New India Assurance’s combined ratio increased by 16.43 percentage points year on year because the rise in its incurred-claim ratio outweighed a lower expense-of-management ratio. The incurred-claim ratio reached 133.71% in the September 2026 quarter, up 25.05 percentage points from 108.66% a year earlier. The expense-of-management ratio declined to 19.95% from 27.89% over the same comparison.
The September result also exceeded the 121.44% combined ratio reported for the quarter ended June 30, 2026. New India Assurance recorded Rs 12,879.50 crore of incurred claims in the September quarter, up from Rs 10,212.43 crore a year earlier, while premium earned rose by a smaller Rs 233.27 crore to Rs 9,632.18 crore.
New India Assurance’s underwriting loss widened to Rs 5,237.35 crore in the September 2026 quarter from Rs 3,554.36 crore in the prior-year quarter. Total expenses, including commission, operating expenses and incurred claims, rose to Rs 14,869.53 crore from Rs 12,953.27 crore, while premium earned increased to Rs 9,632.18 crore from Rs 9,398.91 crore.
What caused New India Assurance’s incurred claims to increase?
New India Assurance’s incurred claims rose because both claims paid and the movement in outstanding-claims reserves increased in the September 2026 quarter. Claims paid were Rs 9,478.83 crore, compared with Rs 8,750.32 crore a year earlier. The change in outstanding claims, including Incurred But Not Reported (IBNR) and Incurred But Not Enough Reported (IBNER) claims, increased to Rs 3,400.67 crore from Rs 1,462.11 crore.
The increase in outstanding claims accounted for Rs 1,938.56 crore of the Rs 2,667.07 crore year-on-year rise in incurred claims. New India Assurance said its appointed actuary determined IBNR and IBNER provisions as at September 30, 2026 in accordance with accepted actuarial practice and Insurance Regulatory and Development Authority of India regulations.
A disclosed Motor Third Party reserve was included in the September-quarter estimate. Following the Supreme Court’s June 11, 2026 judgment concerning the economic value of unpaid domestic work by homemakers for compensation under the Motor Vehicles Act, New India Assurance recognised an initial Rs 715.41 crore claim reserve for its Motor Third Party portfolio. The insurer included the amount in IBNR and IBNER.
The General Insurance Council filed a review petition on July 10, 2026 regarding that judgment, according to New India Assurance’s filing. New India Assurance said it would continue to monitor developments, leaving the ultimate effect of the legal matter on the Motor Third Party reserve unresolved.
Got a follow-up? Ask IRIS
Which New India Assurance segments reported the largest underwriting losses?
New India Assurance’s motor segment reported the largest underwriting loss at Rs 1,953.38 crore for the September 2026 quarter. Health, including personal accident, posted a Rs 1,752.92 crore underwriting loss, followed by fire at Rs 1,612.93 crore. These three lines together reported Rs 5,319.23 crore of underwriting losses, against the company-wide underwriting loss of Rs 5,237.35 crore.
Motor’s underwriting loss widened from Rs 1,068.81 crore in the September 2025 quarter even as net premium increased to Rs 2,855.49 crore from Rs 2,545.86 crore. Health’s loss widened from Rs 1,382.18 crore while net premium was broadly stable at Rs 4,758.72 crore, compared with Rs 4,776.00 crore a year earlier. Fire moved from an underwriting loss of Rs 905.85 crore to Rs 1,612.93 crore as net premium declined to Rs 481.16 crore from Rs 788.14 crore.
Motor also carried the largest technical liabilities among reported segments, at Rs 36,983.16 crore as at September 30, 2026, versus Rs 33,185.01 crore a year earlier. Health technical liabilities stood at Rs 11,593.72 crore, compared with Rs 11,055.21 crore on September 30, 2025. The filing presents technical liabilities separately from segment underwriting results.
How did New India Assurance perform in the first half of 2026-27?
New India Assurance’s combined ratio was 138.52% for the half year ended September 30, 2026, compared with 127.21% in the comparable prior-year half. Its incurred-claim ratio increased to 118.51% from 104.22%, while the expense-of-management ratio declined to 18.22% from 20.78%.
Premium earned increased to Rs 19,315.05 crore for the first half from Rs 18,768.33 crore a year earlier. Incurred claims rose more rapidly to Rs 22,889.56 crore from Rs 19,559.44 crore, resulting in an underwriting loss of Rs 7,593.10 crore, compared with Rs 5,309.96 crore in the prior-year period.
New India Assurance reported a loss after tax of Rs 1,523.81 crore for the half year ended September 30, 2026, against profit after tax of Rs 454.26 crore a year earlier. Operating loss widened to Rs 3,132.81 crore from Rs 739.61 crore. Investment income in the policyholders’ account was Rs 4,460.29 crore for the first half, compared with Rs 4,570.35 crore in the prior-year period.
New India Assurance’s solvency ratio was 1.61 as at September 30, 2026, compared with 1.79 a year earlier and 1.84 at March 31, 2026. Its net retention ratio was 79.85% in the September quarter, down from 83.56% a year earlier. The filing defines the expense-of-management ratio as expense of management plus direct commission divided by gross direct premium, multiplied by 100.
Conclusion
New India Assurance’s September-quarter results show a marked deterioration in underwriting metrics as incurred claims rose faster than premium earned. The 156.20% combined ratio, 133.71% incurred-claim ratio and Rs 5,237.35 crore underwriting loss reflected higher paid claims and a substantially larger movement in outstanding-claims reserves. Motor, health and fire were the largest reported sources of segment underwriting losses.
The next matter to watch is the development of the Rs 715.41 crore Motor Third Party reserve recorded after the June 11, 2026 Supreme Court judgment. New India Assurance said the General Insurance Council’s July 10, 2026 review petition remains under monitoring, while the insurer continues to assess the judgment’s effect on its Motor Third Party portfolio.