










New India Assurance posts ₹1,267 crore September-quarter loss
Key highlights
- New India Assurance reported a ₹1,267.04 crore loss after tax for the quarter ended September 30, 2026, compared with a ₹63.25 crore profit a year earlier.
- Incurred claims rose to ₹12,879.50 crore, exceeding premium earned of ₹9,632.18 crore in the September 2026 quarter.
- The incurred claim ratio increased to 133.71% from 108.66% a year earlier, while the combined ratio reached 156.20%.
- The company’s solvency ratio declined to 1.61 at September 30, 2026, from 1.79 a year earlier and 1.80 in June 2026.
powered by IRIS
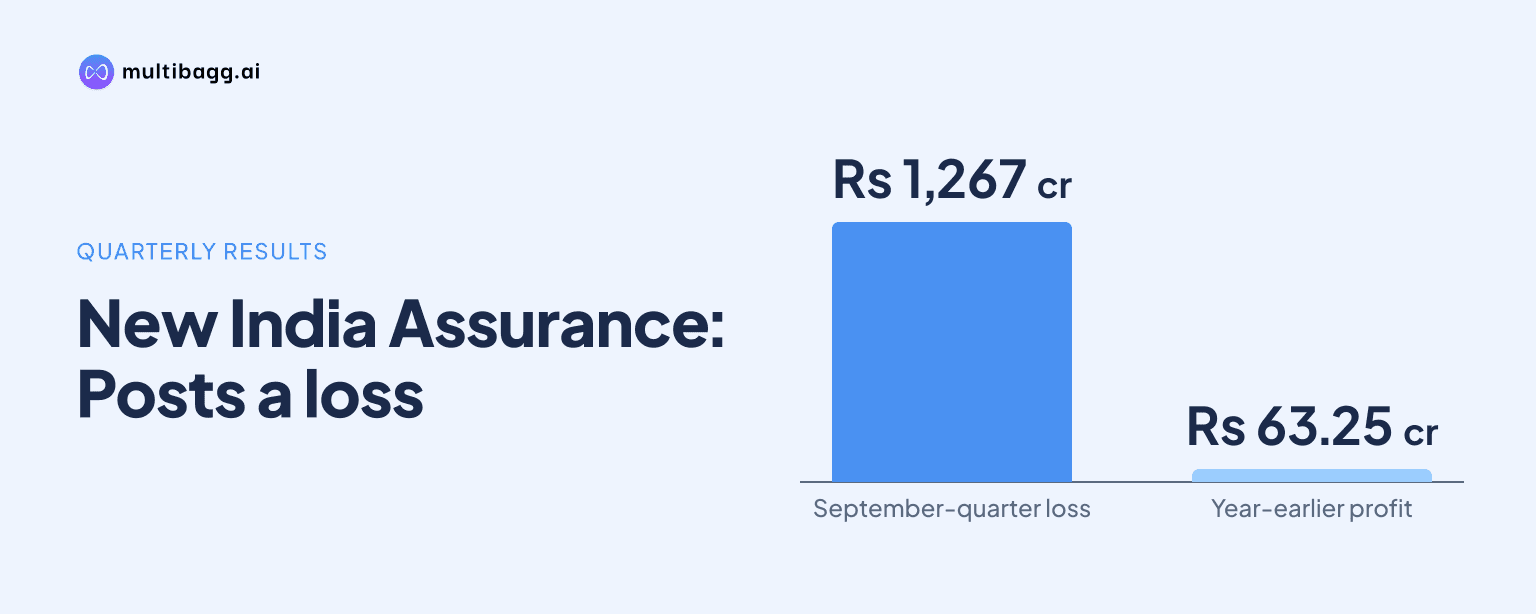
The New India Assurance Company Limited reported a ₹1,267.04 crore loss after tax for the quarter ended September 30, 2026, reversing a ₹63.25 crore profit a year earlier. New India Assurance recorded incurred claims of ₹12,879.50 crore, while its incurred claim ratio rose to 133.71% from 108.66% in the corresponding quarter.
Know New India Assurance Company inside out
Results, valuation, peers and who's buying, in one view.
What was New India Assurance’s September-quarter result?
New India Assurance posted a ₹1,267.04 crore loss after tax for the quarter ended September 30, 2026, compared with a ₹63.25 crore profit for the quarter ended September 30, 2025. The loss also widened from ₹256.77 crore in the quarter ended June 30, 2026. Loss before tax was ₹1,279.77 crore, against a ₹68.91 crore profit a year earlier, while the tax provision was ₹47.87 crore.
The insurance account produced an operating loss of ₹2,330.14 crore, compared with an operating loss of ₹640.28 crore a year earlier and ₹802.67 crore in the preceding quarter. Basic and diluted earnings per share were negative ₹7.69 for the September 2026 quarter, compared with positive ₹0.38 in the September 2025 quarter. The company’s underwriting loss widened to ₹5,237.35 crore from ₹3,554.36 crore.
Why did New India Assurance’s underwriting loss widen?
New India Assurance’s underwriting loss widened by ₹1,682.99 crore year on year because incurred claims increased by ₹2,667.07 crore to ₹12,879.50 crore. Premium earned rose by ₹233.27 crore to ₹9,632.18 crore, but remained below incurred claims. The movement in outstanding claims, including incurred but not reported and incurred but not enough reported claims, was ₹3,400.67 crore, compared with ₹1,462.11 crore a year earlier.
The incurred claim ratio was 133.71% in the September 2026 quarter, 25.05 percentage points above 108.66% a year earlier and 30.33 percentage points above 103.38% in June 2026. The combined ratio was 156.20%, compared with 139.77% in September 2025 and 121.44% in June 2026. The expense of management ratio was 19.95%, down from 27.89% a year earlier but above 16.80% in the preceding quarter.
The financial-results filing does not separately identify a ₹715 crore motor third-party reserve or link a specific reserve to a Supreme Court ruling on homemakers’ economic value. It does report total motor technical liabilities of ₹36,983.16 crore at September 30, 2026, compared with ₹33,185.01 crore a year earlier. The filing therefore supports an increase in motor liabilities but does not provide the stated reserve’s amount or mechanism.
How did New India Assurance’s premium and investment income change?
New India Assurance reported gross premiums written of ₹11,083.43 crore for the September 2026 quarter, up from ₹10,541.17 crore a year earlier and ₹7,372.05 crore in June 2026. Net premium written was ₹8,850.42 crore, slightly above ₹8,807.97 crore in September 2025 but below ₹11,229.27 crore in the June quarter. Net retention was 79.85%, compared with 83.56% a year earlier.
Premium earned rose to ₹9,632.18 crore from ₹9,398.91 crore, while net income from investments was ₹2,907.21 crore, marginally below ₹2,914.08 crore a year earlier. Total income increased to ₹12,539.39 crore from ₹12,312.99 crore. Total expenses increased by ₹1,917.26 crore to ₹14,869.53 crore, producing the operating loss of ₹2,330.14 crore.
For the half year ended September 30, 2026, gross premiums written were ₹24,803.90 crore, compared with ₹23,874.75 crore in the corresponding prior-year half year. However, the half-year loss after tax was ₹1,523.81 crore, against a ₹454.26 crore profit a year earlier. Incurred claims for the six months rose to ₹22,889.56 crore from ₹19,559.44 crore.
Got a follow-up? Ask IRIS
Which New India Assurance segments reported the largest losses?
New India Assurance’s motor segment reported the largest underwriting loss at ₹1,953.38 crore for the September 2026 quarter, widening from ₹1,068.81 crore in the prior-year quarter. Health, including personal accident, reported a ₹1,752.92 crore underwriting loss, compared with ₹1,382.18 crore a year earlier. Fire recorded a ₹1,612.93 crore underwriting loss, versus ₹905.85 crore in September 2025.
Health generated the highest net premium among the listed segments at ₹4,758.72 crore, close to ₹4,776.00 crore a year earlier. Motor net premium increased to ₹2,855.49 crore from ₹2,545.86 crore, while fire net premium declined to ₹481.16 crore from ₹788.14 crore. The segment reporting groups health retail, health group and health government schemes together.
Motor operating loss was ₹195.42 crore, compared with a ₹703.47 crore operating profit a year earlier, whereas health’s operating loss was ₹631.87 crore against a ₹881.52 crore loss. Fire’s operating loss was ₹1,232.64 crore, compared with ₹522.19 crore a year earlier. These operating figures include investment income allocated to the respective segments.
What do New India Assurance’s review and balance-sheet disclosures show?
New India Assurance reported a solvency ratio of 1.61 at September 30, 2026, compared with 1.79 a year earlier and 1.80 at June 30, 2026. Policyholders’ investments increased to ₹61,729.62 crore from ₹58,978.96 crore, while shareholders’ investments rose to ₹24,123.27 crore from ₹23,716.29 crore. Reserves and surplus stood at ₹21,159.76 crore, compared with ₹21,359.00 crore a year earlier.
The limited-review auditors issued a qualified conclusion because reconciliation, compilation and confirmation of certain balances remained at different stages. They said required adjustments had yet to be carried out and that the overall effect could not be ascertained. The auditors reviewed the standalone results for the quarter and half year ended September 30, 2026, and dated their reports October 30, 2026.
The filing lists ₹10,614.72 crore of contingent liabilities for income tax, goods and services tax, and service tax demands that remain before appellate authorities or the Bombay High Court, despite favourable judgments received by New India Assurance. It also records a ₹61.29 crore deferred-tax expense after the company irrevocably opted for the new tax regime under Section 200 of the Income Tax Act, 2025. A reporting-period change for the Bangkok and Fiji branches increased revenue by ₹119.95 crore and increased net loss by ₹2.26 crore.
Conclusion
New India Assurance’s September-quarter loss was driven by claims that rose faster than premium earned, widening the underwriting deficit to ₹5,237.35 crore. The deterioration was evident in the 133.71% incurred claim ratio and in underwriting losses across motor, health and fire, while investment income remained close to the prior-year level at ₹2,907.21 crore.
Next, readers should watch whether the movement in outstanding claims, which reached ₹3,400.67 crore in the September quarter, moderates in later results. The filing also leaves unresolved the reconciliation and confirmation of certain balances identified by the auditors, as well as tax demands reported as ₹10,614.72 crore of contingent liabilities.