










Olectra mobility margins rise as insulator margins contract
Key highlights
- Olectra’s mobility EBITDA margin increased 3.0 percentage points to 14.4% in Q2 FY27.
- Olectra’s insulator EBITDA margin declined 9.7 percentage points to 25.6% in Q2 FY27.
- Olectra sold 759 vehicles in H1 FY27, compared with 536 vehicles in H1 FY26.
- Olectra’s consolidated H1 FY27 revenue increased 25.8% to Rs 1,262.518 crore.
powered by IRIS
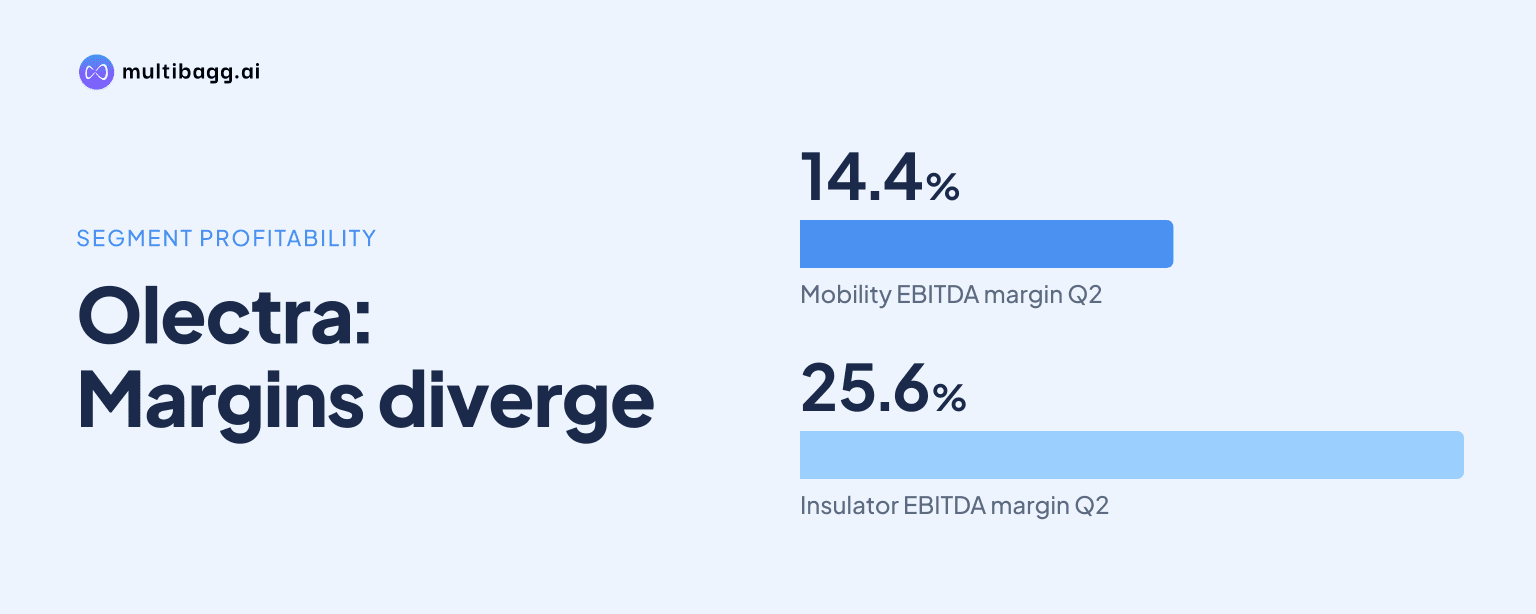
Olectra’s mobility EBITDA margin rose to 14.4% in Q2 FY27 from 11.4%, while its insulator division’s margin declined to 25.6% from 35.3% in the quarter ended 30 September 2026. Mobility EBITDA increased 27.6% despite 1.3% revenue growth, whereas insulator revenue rose 30.1% but EBITDA fell 5.4%.
Know Olectra Greentech inside out
Results, valuation, peers and who's buying, in one view.
Why did Olectra’s segment margins diverge in Q2 FY27?
Olectra’s mobility division expanded its margin because EBITDA grew faster than revenue, while the insulator division recorded lower EBITDA despite higher revenue. Mobility revenue increased 1.3% year on year to Rs 588.971 crore in Q2 FY27 from Rs 581.255 crore, while earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 27.6% to Rs 84.753 crore from Rs 66.431 crore.
The resulting mobility EBITDA margin rose by 3.0 percentage points to 14.4% in Q2 FY27. Profit before interest and tax, or PBIT, also increased 24.7% to Rs 71.273 crore, and the PBIT margin rose to 12.1% from 9.8% in Q2 FY26.
The insulator division moved in the opposite direction during Q2 FY27. Its revenue increased 30.1% to Rs 98.041 crore from Rs 75.369 crore, but EBITDA declined 5.4% to Rs 25.135 crore from Rs 26.575 crore. That reduced its EBITDA margin by 9.7 percentage points to 25.6%, although it remained above mobility’s 14.4% margin.
How did Olectra’s first-half segment margins compare?
Olectra’s mobility division also increased revenue, EBITDA and margin in H1 FY27, while the insulator division’s margin contraction widened over the six-month period ended 30 September 2026. Mobility revenue grew 24.1% to Rs 1,083.597 crore from Rs 873.496 crore, and EBITDA rose 33.7% to Rs 138.192 crore from Rs 103.372 crore.
Mobility’s H1 FY27 EBITDA margin consequently rose to 12.8% from 11.8%, a 1.0-percentage-point increase. Its PBIT increased 31.9% to Rs 111.705 crore from Rs 84.663 crore, with the PBIT margin increasing to 10.3% from 9.7%.
The insulator division delivered the faster H1 revenue growth rate of 37.3%, reaching Rs 178.921 crore from Rs 130.351 crore. However, EBITDA declined 2.2% to Rs 44.597 crore from Rs 45.607 crore, reducing the EBITDA margin by 10.1 percentage points to 24.9% from 35.0%.
Insulator PBIT fell 4.5% to Rs 41.362 crore in H1 FY27 from Rs 43.332 crore a year earlier. Its PBIT margin declined to 23.1% from 33.2%, showing that the fall in operating profitability extended beyond the EBITDA measure.
What changed in Olectra’s mobility sales and economics?
Olectra sold 759 vehicles in H1 FY27, compared with 536 vehicles in H1 FY26, an increase of 223 vehicles. Over the same six months, mobility revenue rose by Rs 210.101 crore and EBITDA increased by Rs 34.820 crore, alongside the 1.0-percentage-point improvement in EBITDA margin.
The Q2 FY27 mobility revenue trend was more modest than the first-half increase. Quarterly revenue was Rs 588.971 crore, only Rs 7.716 crore above Q2 FY26, while quarterly EBITDA increased by Rs 18.322 crore. The 14.4% Q2 margin was therefore above the 12.8% H1 margin.
Olectra’s presentation provides the vehicle count, segment revenue and operating-profit measures for H1 FY27, but does not disclose average selling prices, product mix, contract terms or cost changes. It therefore does not specify the mechanism behind the increase in mobility EBITDA margin from 11.8% to 12.8% during the six-month period.
Got a follow-up? Ask IRIS
What did Olectra’s consolidated results show?
Olectra’s consolidated revenue increased 4.6% to Rs 687.011 crore in Q2 FY27 from Rs 656.623 crore in Q2 FY26. Consolidated EBITDA grew 18% to Rs 109.890 crore from Rs 93.010 crore, while profit before tax, or PBT, increased 6% to Rs 72.740 crore from Rs 68.460 crore.
For H1 FY27, consolidated revenue rose 25.8% to Rs 1,262.518 crore from Rs 1,003.847 crore. EBITDA increased 23% to Rs 182.790 crore from Rs 148.980 crore, while PBT grew 5% to Rs 107.429 crore from Rs 102.256 crore.
The gap between H1 EBITDA growth of 23% and PBT growth of 5% coincided with higher depreciation and amortisation and finance costs. Depreciation and amortisation expense was Rs 29.722 crore in the six months ended 30 September 2026, compared with Rs 20.899 crore a year earlier, while finance costs rose to Rs 45.638 crore from Rs 25.823 crore.
Olectra’s longer-term snapshot shows revenue from operations increasing from Rs 593.26 crore in FY22 to Rs 2,312.168 crore in FY26. Adjusted EBITDA, defined by Olectra as PBT plus depreciation and amortisation plus finance costs, increased from Rs 90.90 crore to Rs 352.28 crore, while adjusted EBITDA margin was 15.2% in FY26 compared with 15.3% in FY25.
What is Olectra planning after September 2026?
Olectra says it has established a greenfield electric-vehicle manufacturing facility across 150 acres in Telangana and has commenced partial operations. The presentation states 2,500 units per shift and annual capacity of 5,000 electric vehicles, but does not disclose a date for full operations, capital expenditure or a utilisation target.
Olectra also reports participation in Convergence Energy Services Limited, or CESL, tenders for large-scale electric-bus procurement programmes. Its stated product actions include introducing Blade Battery technology for safety and efficiency and strengthening products through new platforms, without quantified guidance on tender awards or revenue contribution.
Conclusion
Olectra’s Q2 FY27 segment data shows contrasting profitability trends. Mobility increased its EBITDA margin by 3.0 percentage points to 14.4% as EBITDA grew 27.6%, while the insulator division’s margin fell 9.7 percentage points to 25.6% even as its revenue increased 30.1%. The pattern continued in H1 FY27, with mobility EBITDA rising 33.7% and insulator EBITDA declining 2.2%.
The disclosed items to watch are the ramp-up of the Telangana facility, which has stated annual capacity of 5,000 electric vehicles, and Olectra’s participation in CESL tenders. Subsequent results will also indicate whether mobility can maintain its 12.8% H1 FY27 EBITDA margin and whether the insulator division’s 24.9% margin stabilises.