










ONGC Q2 FY27 Preview Signals ₹15,550-16,423 Crore PAT
Key highlights
- ONGC will report Q2 FY27 results and consider a first interim dividend on 5 November 2026.
- Brokerage estimates place ONGC's standalone Q2 FY27 PAT between ₹15,550 crore and ₹16,423 crore.
- Standalone Q2 FY27 revenue estimates range from ₹43,200 crore to ₹44,340 crore.
- ONGC has set 12 November 2026 as the dividend record date, subject to board approval.
powered by IRIS
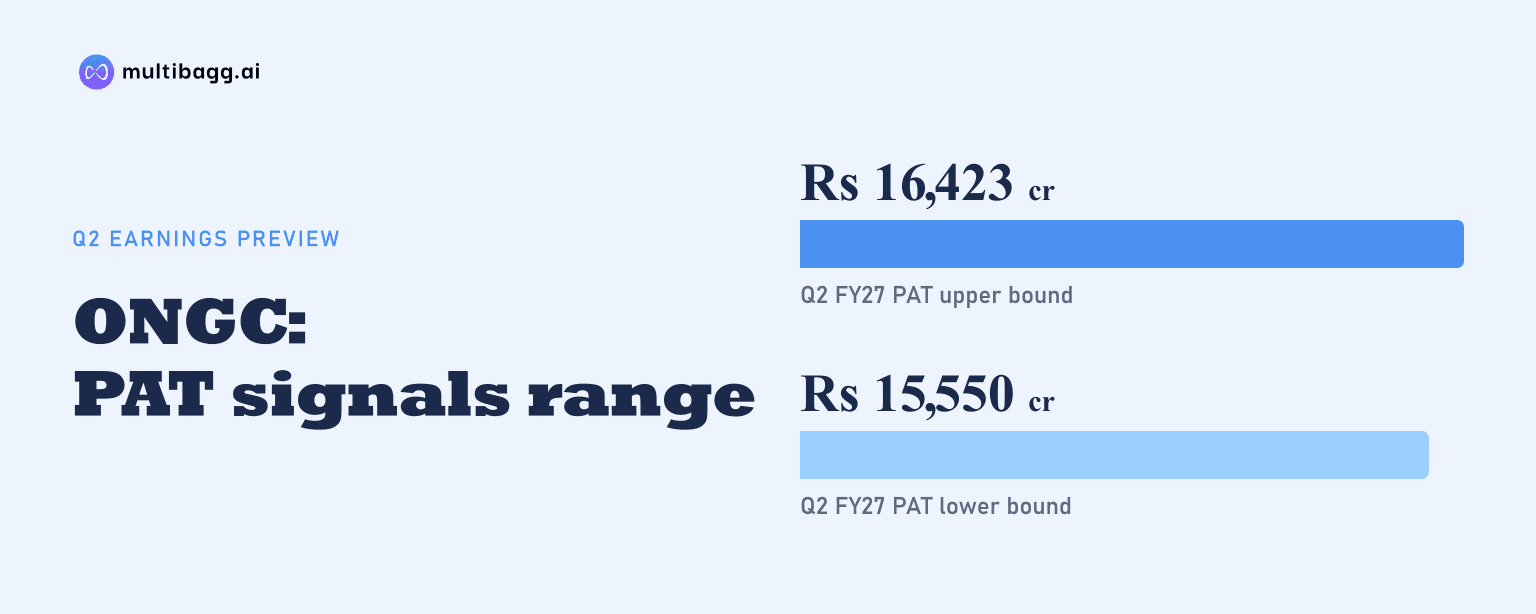
Oil and Natural Gas Corporation Limited is scheduled to report Q2 FY27 results on 5 November 2026, with brokerage estimates placing standalone profit after tax between ₹15,550 crore and ₹16,423 crore. The projected profit range represents year-on-year growth of 58% to 66.8%, supported by elevated crude oil prices, though sequential estimates point to lower revenue and operating profit.
Know Oil & Natural Gas Corpn inside out
Results, valuation, peers and who's buying, in one view.
When will ONGC announce its Q2 FY27 results?
ONGC will announce its unaudited standalone and consolidated financial results for the quarter and half year ended 30 September 2026 on Thursday, 5 November 2026. The board meeting will also consider the first interim dividend for FY27.
The company has fixed 12 November 2026 as the record date for the dividend, if it is declared by the board. Investors holding ONGC shares on the record date, subject to applicable settlement rules, would be eligible for the proposed payout.
ONGC has also scheduled an earnings conference call for 6 November 2026 at 3:30 pm IST. Director (Finance) Anupam Agarwal, Chief Corporate Finance Yogish Nayak and Chief Treasury and Investor Relations Dr. Ravinder Singh Negi are expected to discuss the quarterly performance and outlook with analysts and investors.
What are the brokerage estimates for ONGC's Q2 FY27 earnings?
Brokerages expect ONGC's standalone Q2 FY27 revenue to be in the ₹43,200 crore to ₹44,340 crore range and standalone net profit to be between ₹15,550 crore and ₹16,423 crore. Elara Capital estimates revenue of ₹43,232 crore and net profit of ₹16,423 crore, while JM Financial estimates profit of ₹15,551 crore on revenue of ₹43,311 crore.
HDFC Securities projects revenue of ₹44,340 crore and net profit of ₹16,100 crore. The estimates imply year-on-year revenue growth of 31% to 34.2% where growth rates were provided, with net-profit growth ranging from 58% to 66.8%.
A separate Zee Business estimate indicates a sequentially softer quarter. It projects standalone revenue of ₹44,040 crore, down 5.2% from ₹46,460 crore in Q1 FY27, and adjusted PAT of ₹14,559 crore, down 14.5% from ₹17,034 crore. Differences between forecasts can arise from assumptions on crude realisations, production, costs and accounting adjustments.
Why could ONGC's sequential earnings decline?
The sequential pressure in estimates is linked principally to lower expected crude oil and gas price realisations. Zee Business estimates a 7.6% decline in both net crude oil price realisation and gas price realisation during the September quarter.
Its estimate places adjusted EBITDA at ₹26,113 crore, 11.3% below ₹29,453 crore in the June quarter. The adjusted EBITDA margin is projected at 59.3%, compared with 63.4% in Q1 FY27. These calculations adjust EBITDA for survey and exploratory well costs, using a base of ₹1,099 crore.
Price realisations are particularly important for ONGC because upstream earnings are directly linked to the value received for oil and gas output. In Q1 FY27, standalone net profit rose 112% year-on-year to ₹17,034 crore as net realisation on nominated crude increased to $99.45 a barrel from $66.13 a barrel a year earlier.
Got a follow-up? Ask IRIS
Can production growth support ONGC's Q2 performance?
Modest volume growth may partly offset the expected decline in realisations, with total crude oil sales volume estimated to rise 1.5% and natural-gas sales volume projected to increase 1% in Q2 FY27. Higher contribution from new-well gas may also support gas realisations.
New-well gas earned $13.31 per mmBtu in Q1 FY27, compared with $7.00 per mmBtu for nomination gas. It generated ₹3,998 crore, equivalent to about 38% of revenue from nomination gas, according to the available Q1 disclosures. This makes the mix of new-well output and nomination gas relevant to quarterly earnings.
Production was a pressure point in the June quarter. Standalone oil and gas output declined 3.4% year-on-year to 9.444 million tonnes of oil equivalent, with ONGC citing reservoir behaviour at KG-98/2, sea swell in the Western Offshore and wells shut for project commissioning. The company expects this decline to be arrested and reversed.
What should investors track in ONGC's results and dividend decision?
Investors will track the reported crude and gas realisations, production volumes, operating margin and the board's interim-dividend decision. The timing of peak oil production from the KG Basin remains a stated downside risk, making management's comments on project commissioning and output recovery important.
For FY27, ONGC has outlined a standalone hydrocarbon production plan of about 42.5 million tonnes of oil equivalent, comprising 21 million tonnes of crude oil and 21.5 billion cubic metres of natural gas. The target is higher than 38.87 million tonnes of oil equivalent reported for FY26 and depends on the planned ramp-up of deepwater and KG Basin fields.
The distinction between standalone and consolidated results is also material. In Q1 FY27, standalone revenue was ₹46,460 crore, while group revenue was reported at ₹2,04,987 crore. Consolidated profit attributable to ONGC shareholders rose 21.4% year-on-year to ₹11,899 crore, while HPCL's consolidated net loss of ₹12,265 crore affected group profitability.
Conclusion
ONGC enters its Q2 FY27 announcement with brokerage forecasts indicating strong year-on-year standalone profit growth, but with the possibility of a sequential decline as crude and gas realisations soften from Q1 levels. Production volumes, new-well gas contribution and cost adjustments will determine how reported results compare with these varying estimates.
The immediate next events are the 5 November results and dividend decision, followed by the 6 November management call. Investors will watch for the interim-dividend declaration, the progress of KG Basin output and management's assessment of the 42.5 million tonnes of oil equivalent FY27 production plan.