










Patel Retail has Rs 8.28 crore IPO proceeds unutilised
Key highlights
- Patel Retail used Rs 180.9175 crore of Rs 189.1938 crore in IPO net proceeds by September 30, 2026.
- Patel Retail fully used Rs 109.0002 crore for working capital and Rs 59 crore for borrowing repayment.
- Rs 8.2763 crore of IPO proceeds remained allocated to general corporate purposes.
- IPO issue expenses were Rs 27.9132 crore, Rs 1.2849 crore above the prospectus estimate.
powered by IRIS
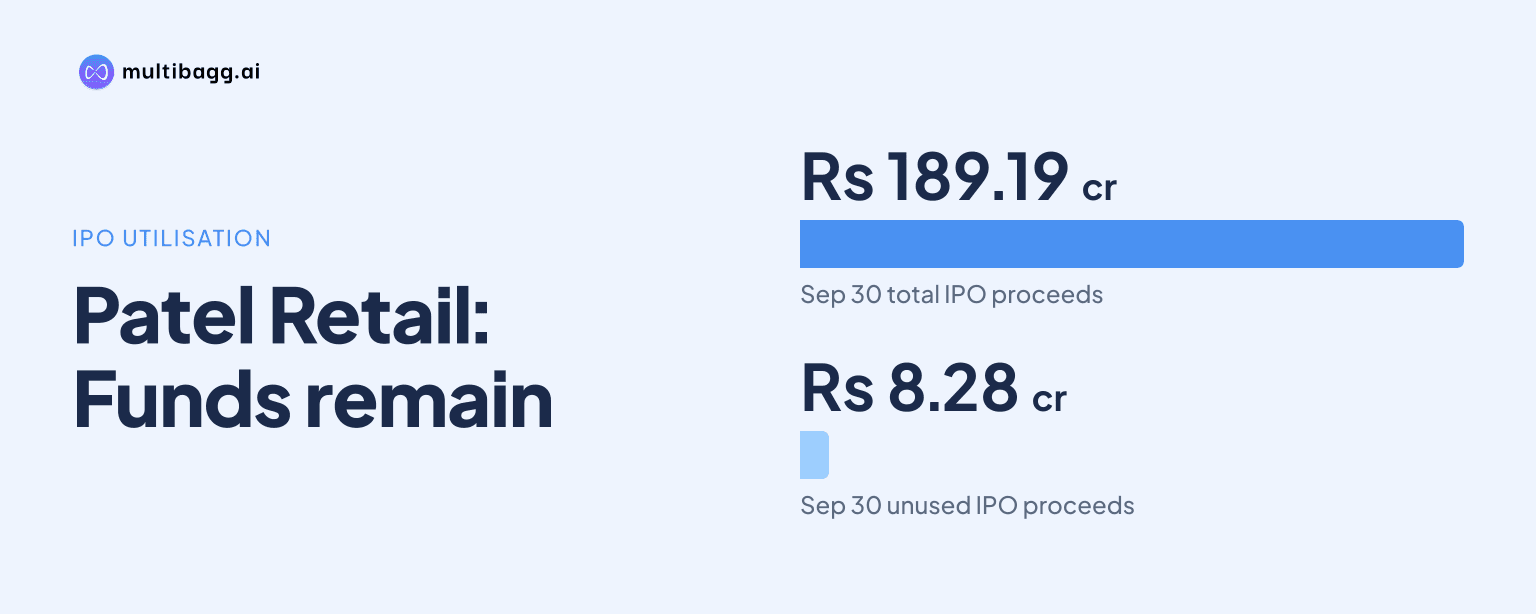
Patel Retail Limited had used Rs 180.9175 crore of its Rs 189.1938 crore initial public offering, or IPO, net proceeds by September 30, 2026, leaving Rs 8.2763 crore for general corporate purposes. Patel Retail reported that its working-capital and borrowing-repayment allocations were fully utilised and disclosed no deviation or variation in the use of raised funds.
Know Patel Retail inside out
Results, valuation, peers and who's buying, in one view.
How did Patel Retail allocate its IPO proceeds?
Patel Retail allocated Rs 189.1938 crore of IPO net proceeds among working capital, repayment or prepayment of borrowings, and general corporate purposes. The September 30, 2026 disclosure shows Rs 109.0002 crore earmarked for working capital, Rs 59 crore for borrowings and Rs 21.1936 crore for general corporate purposes.
The company also raised Rs 15 crore through a pre-IPO placement, based on the November 27, 2024 allotment date disclosed in the filing. Of this amount, Rs 6 crore was allocated to working capital and Rs 9.0002 crore to general corporate purposes, while no pre-IPO proceeds were assigned to debt repayment.
Which IPO objects had Patel Retail completed by September 2026?
Patel Retail had completed the Rs 109.0002 crore IPO allocation for working capital and the Rs 59 crore allocation for repayment or prepayment of certain borrowings by September 30, 2026. Together, those two completed IPO objects accounted for Rs 168.0002 crore, leaving general corporate purposes as the only category with an unused IPO balance.
Including the pre-IPO placement, Patel Retail had allocated Rs 115.0002 crore to working capital and used the full amount. General corporate purposes had a combined allocation of Rs 30.1938 crore, of which Rs 21.9175 crore had been used, comprising Rs 9.0002 crore of pre-IPO funds and Rs 12.9173 crore of IPO funds.
The company reported aggregate IPO and pre-IPO net proceeds of Rs 204.1938 crore and aggregate utilisation of Rs 195.9175 crore as of September 30, 2026. The remaining Rs 8.2763 crore in the combined disclosure was entirely the unutilised IPO allocation for general corporate purposes.
Why does Patel Retail still have Rs 8.28 crore available?
Patel Retail retained Rs 8.2763 crore because this balance remained allocated to general corporate purposes as of September 30, 2026. Its fund-utilisation statement recorded no unutilised balance for either the working-capital object or the borrowing-repayment object.
The company said actual IPO issue expenses through September 30, 2026 were Rs 27.9132 crore, compared with Rs 26.6283 crore estimated in the prospectus. The Rs 1.2849 crore excess was adjusted against the general-corporate-purpose allocation, reducing the amount available for that object from its original planned use.
Patel Retail reported Rs 9.2631 crore in its escrow and monitoring account, including fixed deposits and excluding interest income, at the reporting date. That amount included Rs 96.60 lakh payable to promoters in connection with the offer for sale, or OFS, so it was not the same as the Rs 8.2763 crore unutilised IPO balance.
Got a follow-up? Ask IRIS
Did Patel Retail report any deviation in IPO fund use?
Patel Retail reported no deviation or variation in the utilisation of funds raised in its statement for the quarter ended September 30, 2026. The disclosure also showed no modified allocation for the Rs 59 crore borrowing object, Rs 115 crore working-capital object or Rs 30.19 crore general-corporate-purpose object, with the latter figures rounded in the deviation table.
ICRA Limited was named as the monitoring agency for the fund raise, while the filing stated that there were no auditor comments. The IPO allotment date was August 22, 2025, and the deviation statement was filed alongside financial results approved by the board on November 4, 2026.
The disclosure defines deviation or variation to include a change in the objects of the fund raise, a change in amounts used against the originally disclosed objects, or a change in terms of the prospectus or other fund-raising document. Patel Retail marked the shareholder-approval and explanation fields as not applicable because it reported no such deviation.
What other balance-sheet changes did Patel Retail disclose?
Patel Retail’s current borrowings were Rs 89.3492 crore at September 30, 2026, down from Rs 109.0324 crore at March 31, 2026, while non-current borrowings declined to Rs 12.9134 crore from Rs 14.2156 crore. These balance-sheet movements were disclosed separately and do not assign every change in borrowings to the Rs 59 crore IPO debt-repayment allocation.
Inventories rose to Rs 282.1882 crore at September 30, 2026 from Rs 259.5989 crore at March 31, 2026, whereas trade receivables fell to Rs 133.2084 crore from Rs 161.949 crore. Total assets decreased to Rs 611.5412 crore from Rs 620.0985 crore over the same period, while total equity increased to Rs 383.1875 crore from Rs 363.8924 crore.
Comparisons with the prior-year period have an accounting limitation because Patel Retail changed the depreciation method for property, plant and equipment from written-down value, or WDV, to the straight-line method, or SLM, during the quarter ended June 30, 2026. Management said the change reduced depreciation and amortisation in that quarter to Rs 1.3288 crore from about Rs 3.0382 crore under WDV, increasing profit before tax by about Rs 1.7094 crore.
Patel Retail also recognised right-of-use assets and lease liabilities after modifying store lease and amenities agreements to include fixed lock-in periods. For the period ended September 30, 2026, this resulted in Rs 6.1367 crore of depreciation, Rs 1.3493 crore of finance cost and Rs 6.6344 crore of reversals of rent and service charges; the company said the September 2025 comparative period is not comparable to that extent.
Conclusion
Patel Retail had deployed nearly all of its IPO net proceeds by September 30, 2026, with the full Rs 109.0002 crore working-capital allocation and Rs 59 crore borrowing-repayment allocation used. The Rs 8.2763 crore balance remained within the original general-corporate-purpose object, and the company reported no fund-use deviation.
The next disclosure to watch is utilisation of the Rs 8.2763 crore still designated for general corporate purposes, because the filing gives no specific deployment timetable or sub-category for that balance. Future utilisation statements can show whether Patel Retail has deployed the amount while continuing to report no deviation from the stated IPO objects.