










Pidilite Industries Reports 21.7% Q2 Revenue Growth in FY27
Key highlights
- Pidilite Industries reported Q2 FY27 standalone revenue of ₹3,982 crore, up 21.7% year-on-year.
- Q2 FY27 underlying volume growth was 10.7%, including 11.1% in Consumer and Bazaar.
- Q2 FY27 EBITDA margin was 20.4% after VAM consumption cost rose to $1,630.
- H1 FY27 standalone revenue increased 22.0% to ₹8,219 crore and EBITDA margin was 23.5%.
powered by IRIS
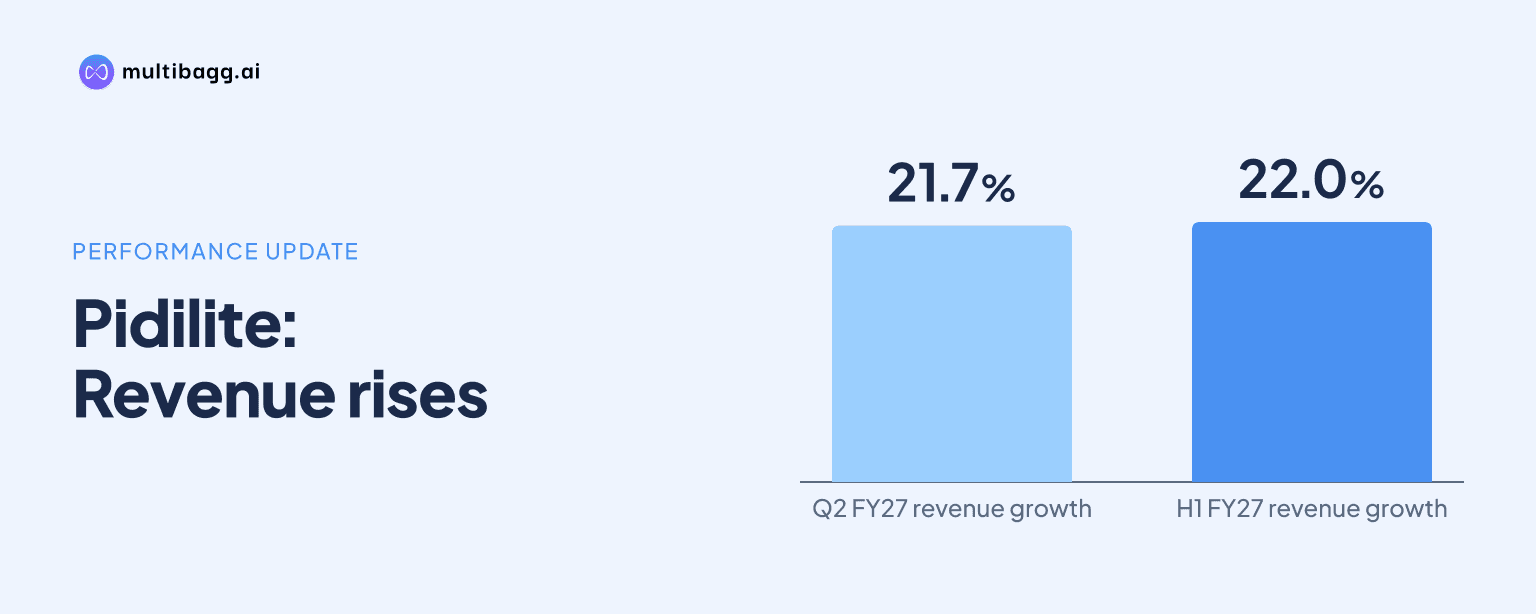
Pidilite Industries Limited reported 21.7% standalone revenue growth in Q2 FY27, with revenue of ₹3,982 crore. The maker of adhesives and construction chemicals recorded 10.7% underlying volume growth, but elevated vinyl acetate monomer costs lowered its quarterly EBITDA margin to 20.4%.
Know Pidilite Industries inside out
Results, valuation, peers and who's buying, in one view.
What drove Pidilite Industries' Q2 FY27 revenue growth?
Pidilite Industries' Q2 FY27 growth was driven by broad-based volume expansion across its consumer, bazaar and business-to-business operations. Consumer and Bazaar underlying volume growth was 11.1%, while B2B volume growth was 9.2%. This supported 21.7% nominal growth in standalone revenue to ₹3,982 crore during the quarter.
The company also reported growth from its subsidiary businesses. International subsidiaries grew 21.8%, while domestic subsidiaries recorded revenue growth of 22.2%. Management said the domestic subsidiary performance was broad-based, with ICA wood finishes, construction chemical businesses and newer joint-venture products contributing to growth.
For the first half of FY27, Pidilite's standalone revenue rose 22.0% to ₹8,219 crore, with underlying volume growth of 11.0%. Standalone profit after tax increased 19.5% to ₹1,477 crore in H1 FY27. Q2 standalone profit after tax rose 10.4% to ₹647 crore, according to the earnings summary.
How did higher VAM costs affect Pidilite Industries' margins?
Higher vinyl acetate monomer, or VAM, costs put material pressure on Pidilite Industries' gross margin during the quarter. The company's VAM consumption rate was $1,630 in Q2 FY27, compared with $1,370 in the preceding quarter and nearly twice the level in the comparable period a year earlier.
Standalone gross margin declined by 720 basis points year-on-year and sequentially, reflecting the full impact of cost inflation in the quarter. EBITDA margin fell by 430 basis points to 20.4%, which management described as the lower end of its stated margin range. Strong revenue growth and resulting operating leverage partly offset the gross-margin decline.
The cost movement is important for Pidilite because VAM is a key input for several adhesive and polymer-based products. Management said it has assessed domestic VAM production economics with international partners but does not see a pricing advantage for local production, given the lack of a natural domestic cost advantage in ethylene or acetic acid.
Got a follow-up? Ask IRIS
What is Pidilite Industries doing to protect profitability?
Pidilite Industries has used calibrated price increases to recover higher input costs while seeking to retain demand momentum. The company took price increases of 12% to 15% in the first quarter and initiated another 3% to 5% increase from October 1 on selected brands, including Fevicol and Dr. Fixit.
Management said the full cost increase had been passed on in absolute terms and more, but recovering prior gross-margin percentages requires pricing that is materially higher than the cost increase. It said such a recovery cannot be implemented immediately in the market. A possible further pricing action later in the quarter was also indicated.
For H2 FY27, the company has guided for EBITDA margins within its 20% to 24% corridor and expressed an aim to operate near the higher end of that range. The guidance places attention on the trajectory of raw-material costs, the pace of price realisation and the degree to which volume growth continues to provide operating leverage.
Which businesses supported Pidilite Industries' demand momentum?
Construction chemicals, wood finishes and core adhesive brands supported Pidilite Industries' demand momentum in Q2 FY27. Management cited robust growth in waterproofing, tile adhesives, Roff products, the projects business, TMX stone-care products and emerging floor-coating categories.
The company described demand as broad-based, with an improvement in urban growth alongside continued rural strength. It linked volume expansion to investments in brand building, field marketing, richer product portfolios and product innovation. Management also said Fevicol delivered 50 to 100 basis points better growth than in the past.
Pidilite is testing UnoFin, a plaster product intended to replace traditional layered applications. Initial responses were reported from Delhi, Jaipur and Chandigarh. The company also noted that its MENA business faced monsoon-related challenges, while other domestic subsidiaries grew by more than 20%.
For investors, the quarter shows that Pidilite's sales growth remained resilient despite higher prices and input-cost volatility. The central operating issue remains the balance between protecting margins and sustaining volumes in consumer and construction-linked categories. Consolidated revenue from operations was ₹4,297.59 crore in Q2 FY27, while profit attributable to shareholders was ₹614.53 crore.
Conclusion
Pidilite Industries delivered strong Q2 FY27 revenue and volume growth, supported by its consumer, bazaar, B2B and subsidiary businesses. However, the sharp rise in VAM costs reduced gross margin and brought quarterly EBITDA margin to 20.4%, despite support from operating leverage.
Investors will watch the effect of the October price increase, any subsequent pricing actions and the movement in VAM costs through H2 FY27. Management has retained its EBITDA margin corridor of 20% to 24% for the second half, while continuing investments in brands, field execution and construction-chemical products.