










PIGL's PECL turnover rose 126% to Rs 57.3 crore in FY26
Key highlights
- PECL turnover rose 126% from Rs 25.4 crore in FY23 to Rs 57.3 crore in FY26.
- PIGL increased its PECL holding to 60.00% in March 2026.
- PECL reported an order book of more than Rs 12 crore as of September 30, 2026.
- PIGL's consolidated H1FY27 EBITDA margin was 11.50%, compared with 10.33% in H1FY26.
powered by IRIS
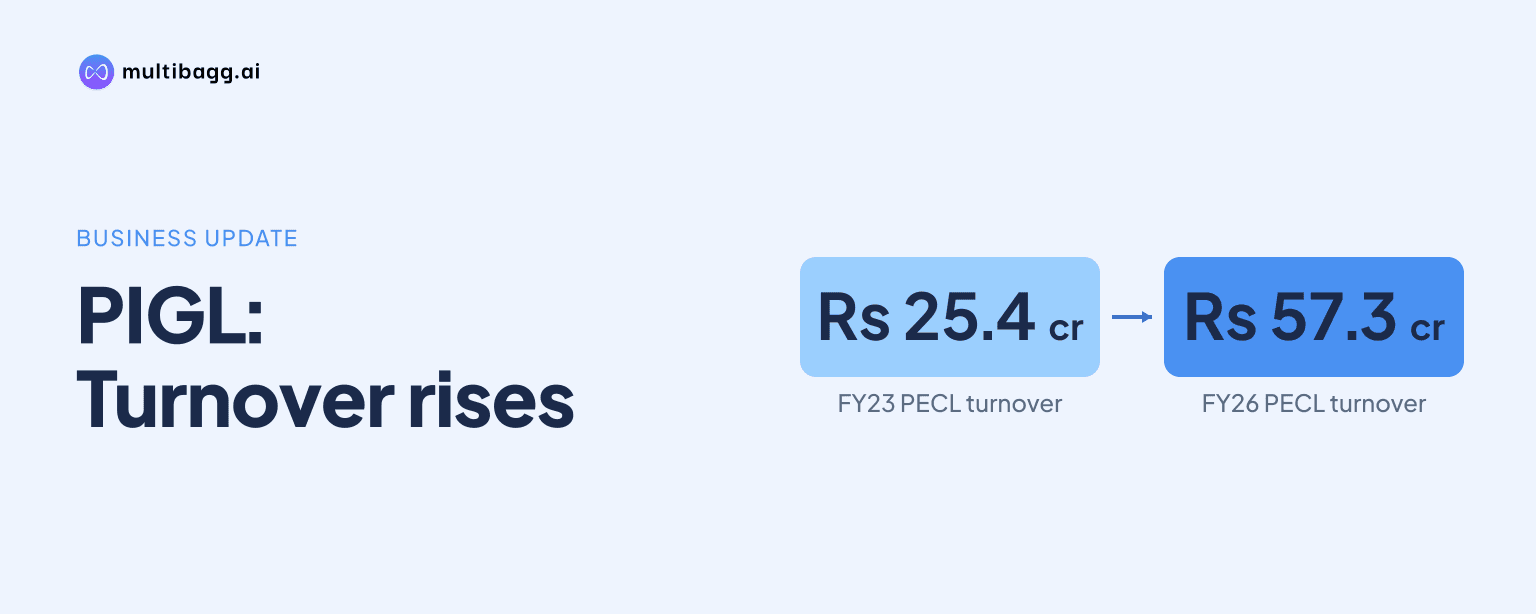
Power & Instrumentation (Gujarat) Ltd's 60%-owned subsidiary, Peaton Electrical (PECL), increased turnover by 126% from Rs 25.4 crore in FY23 to Rs 57.3 crore in FY26. PIGL raised its PECL holding to 60% in March 2026, linking the electrical-products operation with its engineering, procurement and construction, or EPC, business.
Know Power & Instrumentation (Gujarat) inside out
Results, valuation, peers and who's buying, in one view.
How quickly did PIGL's PECL turnover grow?
PECL turnover rose by Rs 31.9 crore between FY23 and FY26, although the growth path included a decline in FY24. Turnover fell from Rs 25.4 crore in FY23 to Rs 23.6 crore in FY24, then increased to Rs 36.0 crore in FY25 and Rs 57.3 crore in FY26. The FY26 figure was Rs 21.3 crore above FY25, a 59% year-on-year increase.
The disclosed sequence shows that PECL's expansion accelerated after FY24: turnover rose by Rs 12.4 crore in FY25 and by Rs 21.3 crore in FY26. PIGL does not provide PECL's profit, margin, external-customer sales or sales to PIGL projects in these pages, so the turnover data does not establish the subsidiary's separate earnings contribution.
PECL reported an order book of more than Rs 12 crore as of September 30, 2026. That is distinct from PIGL's order book of more than Rs 320 crore, comprising eight projects to be completed over 12 to 15 months. The presentation does not identify how much of PECL's order book relates to supplies for PIGL versus external customers.
What products does PIGL's PECL offer?
PECL's portfolio includes medium-voltage and low-voltage panels, compact substations, unitized substations, busduct systems, automatic power factor correction panels, auto-sync panels and distribution boards. PIGL states that the strategic purpose is in-house supply of panels, busducts and compact substations for its project-execution business.
The operation is at GIDC Talod, Gujarat, in a 1.26 lakh square-foot facility with an in-house research and development centre. PIGL says PECL can develop products and establish a products-led revenue stream from external customers, but the presentation does not disclose the plant's output capacity, utilisation, capital expenditure or product-wise turnover.
PECL is licensed by Siemens to manufacture SIEPAN 8PU low-voltage switchboards. It is also eligible to assemble, test and sell Schneider Electric-compliant PrismaSeT I switchboards, while the Central Power Research Institute has approved its 11 kilovolt, 3,000 ampere busduct system. These credentials apply to specified offerings and do not quantify sales from those products.
How did PECL become a 60%-owned PIGL subsidiary?
PIGL increased its PECL interest from an initial 15.23% to 51.06% in 2025, when PECL became a subsidiary, and to 60.00% in March 2026. The March 2026 holding means PECL is included in PIGL's consolidated financial statements, while ownership outside PIGL remains 40%.
PIGL's Q2FY27 and H1FY27 consolidated figures include PECL. Consolidated revenue was Rs 77.14 crore in Q2FY27, compared with standalone revenue of Rs 69.60 crore, while H1FY27 consolidated revenue was Rs 126.04 crore against Rs 110.27 crore on a standalone basis. Those differences show the effect of consolidation across the group, but the presentation does not provide a PECL-specific revenue bridge.
Consolidated earnings before interest, tax, depreciation and amortisation, or EBITDA, were Rs 9.52 crore in Q2FY27, compared with standalone EBITDA of Rs 8.45 crore. Consolidated EBITDA margin was 12.34%, versus standalone EBITDA margin of 12.14%, but PIGL does not quantify PECL's direct effect on either margin.
Got a follow-up? Ask IRIS
How does PECL support PIGL's EPC business?
PIGL links PECL to EPC execution through in-house supply of panels, busducts and compact substations, which management says supports supply reliability and margins. PIGL's EPC services cover substations, distribution panels, lighting, generators and uninterruptible power supply systems across transmission and distribution projects.
In H1FY27, PIGL's consolidated revenue increased 12.96% year on year to Rs 126.04 crore from Rs 111.57 crore. Consolidated EBITDA rose 36.58% to Rs 14.53 crore and the EBITDA margin increased to 11.50% from 10.33%. Management attributed margin expansion to backward integration and operational efficiency, without assigning a rupee or percentage-point contribution to PECL.
Standalone revenue rose 1.01% year on year to Rs 110.27 crore in H1FY27, while standalone EBITDA margin reached 11.58% from 9.41% in H1FY26. The consolidated and standalone comparison coincides with PECL's consolidation after the March 2026 stake increase, but it does not prove that PECL caused the difference because PIGL also cited execution and diversification across segments.
What is management expecting from backward integration in FY27?
Management expects PIGL to deliver 30% revenue growth in FY27, with margin expansion driven by backward integration. This is management's outlook, not a reported result, and the presentation does not provide a separate FY27 turnover or margin target for PECL.
As of September 30, 2026, PIGL had an order book of more than Rs 320 crore and active bids of more than Rs 500 crore. Management said the order book was executable over 12 to 15 months, while PECL had an order book of more than Rs 12 crore. The presentation does not state the proportion of future group projects expected to use PECL equipment.
PIGL has also entered the 400 kilovolt extra-high-voltage segment, which management says opens larger-ticket transmission opportunities. Its reported execution base includes more than 310 projects, more than 35 airport projects and more than 20,000 kilometres of high-tension and low-tension lines, providing the project backdrop for PECL's products.
Conclusion
PECL's rise from Rs 25.4 crore of turnover in FY23 to Rs 57.3 crore in FY26 is the clearest disclosed measure of PIGL's backward-integration build-out. The 60% holding, 1.26 lakh square-foot Talod facility, product range and identified Siemens, Schneider Electric and Central Power Research Institute credentials show the addition of electrical-products capability alongside EPC execution.
The next markers are management's FY27 target of 30% revenue growth with margin expansion, execution of the more than Rs 320 crore order book over 12 to 15 months, and progress on more than Rs 500 crore of active bids. Future disclosures would be needed to determine PECL's separate revenue, margins, external sales and contribution to PIGL project supplies.