










Popular Vehicles earns 62% of EBITDA from after-sales in FY26
Key highlights
- Services, repairs and spare-parts distribution generated 62% of Popular Vehicles’ FY26 EBITDA from 19% of revenue.
- New vehicles contributed 75% of FY26 revenue but 37% of EBITDA.
- Total service revenue rose 7% to Rs 967.9 crore in FY26, while service volumes declined 6% to 9,82,100.
- Adjusted EBITDA increased 27% to Rs 200.9 crore in FY26 from Rs 157.7 crore in FY25.
powered by IRIS
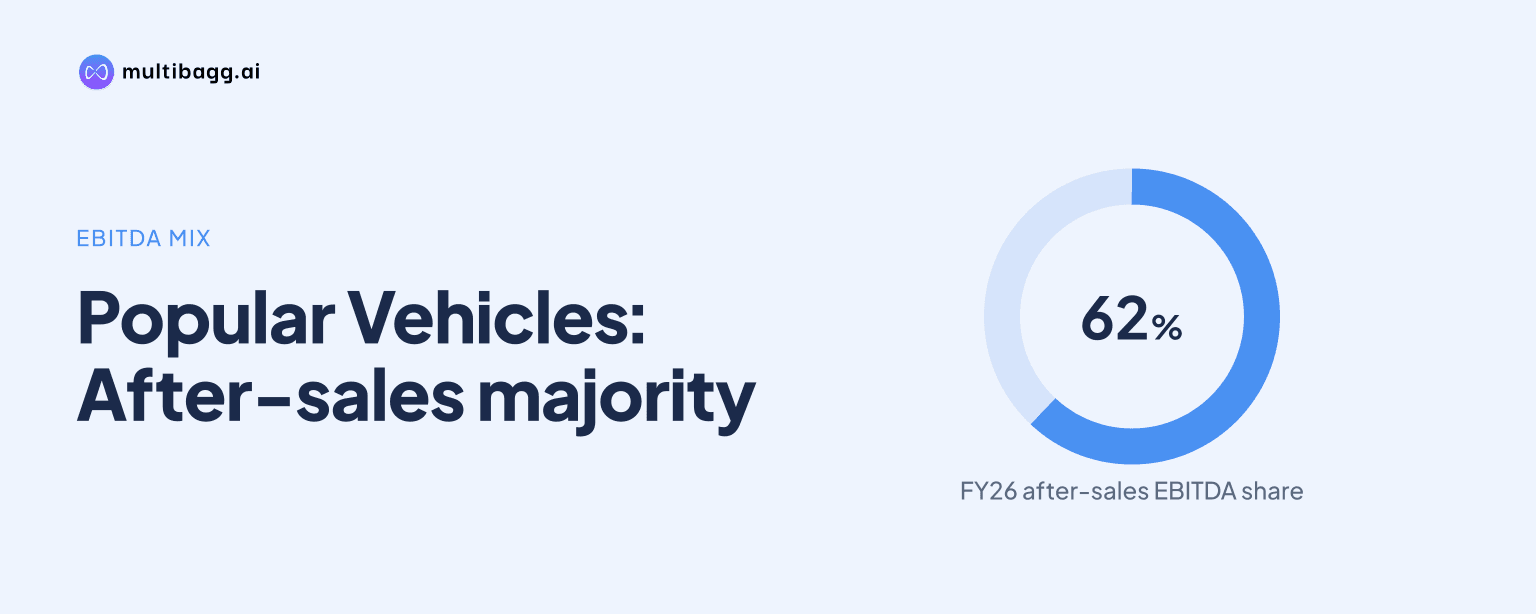
Popular Vehicles & Services derived 62% of FY26 consolidated earnings before interest, tax, depreciation and amortisation (EBITDA) from services, repairs and spare-parts distribution, despite those activities contributing 19% of revenue. New-vehicle sales supplied 75% of revenue but 37% of EBITDA, according to the company’s FY26 presentation.
Know Popular Vehicles & Services inside out
Results, valuation, peers and who's buying, in one view.
Why did Popular Vehicles’ after-sales activities account for 62% of EBITDA?
Popular Vehicles classifies services, repairs and spare-parts distribution as high-volume, high-margin activities, while it describes new-vehicle sales as high volume and low margin. The FY26 result reflects that stated model: services, repairs and parts distribution produced nearly two-thirds of consolidated EBITDA from less than one-fifth of revenue. The company says a larger contribution from this business should result in higher margins and return ratios.
The services offering spans warranty work, customer-paid out-of-warranty work, running repairs and collision repairs. It also includes periodic maintenance, auto-body repair, air-conditioning or electrical work, tyres, batteries and vehicle detailing. In the passenger-vehicle, or PV, service presentation, Popular Vehicles reported Rs 607 crore of service and repair income and Rs 98 crore of EBITDA in FY26. Collision and repair represented 38% of that income and 43% of its EBITDA, while other service and repair work accounted for 62% of income and 57% of EBITDA.
How does Popular Vehicles’ EBITDA mix compare with its revenue mix?
Popular Vehicles’ FY26 consolidated mix shows the difference between the scale of vehicle sales and the earnings contribution of after-sales operations. The figures include other income and group services, repairs and spare-parts distribution in one line item.
The after-sales and parts line had a 43-percentage-point higher share of EBITDA than revenue, whereas new vehicles had a 38-percentage-point lower EBITDA share than revenue. This is a comparison of business mix, not a disclosed margin percentage for each vertical. Pre-owned vehicles contributed 6% of revenue but 1% of EBITDA, and Popular Vehicles describes that segment as a high-volume, opportunistic business that supports aftermarket-sales presence.
The presentation also provides a separate PV-only service view as of March 31, 2026. In that view, services and repairs accounted for 11% of total income and 49% of EBITDA, while other activities accounted for 89% of income and 51% of EBITDA. Total PV-segment income was Rs 3,505 crore and total EBITDA was Rs 113 crore. The company defines the other activities in this PV chart as new vehicles, pre-owned vehicles and spare parts, so its scope differs from the consolidated business-vertical table.
Got a follow-up? Ask IRIS
What changed in Popular Vehicles’ service revenue and volumes in FY26?
Popular Vehicles’ total service revenue rose 7% to Rs 967.9 crore in FY26 from Rs 903.2 crore in FY25, even as total service volumes declined 6% to 9,82,100 from 10,42,298. On the company’s adjusted or organic basis, service revenue increased 8% to Rs 868.2 crore from Rs 805.6 crore, while volumes declined 4% to 8,99,778 from 9,35,045. The adjusted figures remove the effects identified by the company from divestments and acquisitions.
The FY26 service figures remove Rs 37.2 crore of revenue and 44,842 service volumes linked to the Honda and Piaggio businesses, compared with Rs 97.7 crore and 1,07,253 in FY25. They also remove Rs 62.5 crore of revenue and 37,480 volumes from acquisitions in FY26. Those acquisitions were Globe CV, RKS Motors and Olympus Motors. By comparison, total new-vehicle revenue rose 19% to Rs 4,813.3 crore in FY26, while adjusted new-vehicle revenue rose 16% to Rs 4,493.1 crore; adjusted vehicle volumes grew 19% to 50,343.
At the group level, reported EBITDA increased 16% to Rs 203.4 crore in FY26 from Rs 175.4 crore in FY25. Management’s adjusted EBITDA measure, which removes divested-business EBITDA, acquisition-related EBITDA and a one-off cess provision, increased 27% to Rs 200.9 crore from Rs 157.7 crore. The presentation places the service-revenue increase alongside a larger increase in adjusted group EBITDA, but does not disclose a separate year-on-year EBITDA figure for the consolidated services-and-parts vertical.
How does Popular Vehicles plan to expand after-sales and spare parts?
Popular Vehicles plans to increase authorised service centres, customer retention, preventive-maintenance awareness and sales of vehicle service contracts. Its listed mechanisms also include parts-inventory management, a service call centre, salesperson training and customer databases built through insurance and financial-product sales. The company ranked first nationally by FY25 service volume for Maruti Suzuki and Tata Motors commercial vehicles, and second for JLR, or Jaguar Land Rover.
For spare parts, Popular Vehicles plans to scale Yanik, its ZPAREX digital platform, as an e-commerce business for parts and accessories. It also intends to expand its distribution portfolio through BKT’s two-wheeler and passenger-car radial tyre segments, sell to independent workshops and fleet operators, and cross-sell accessories. These plans seek to increase non-vehicle-sales revenue, although the presentation does not provide a revenue target or timetable for Yanik, BKT distribution or the workshop initiative.
Acquisitions form the second element of the growth plan. Globe CV, a BharatBenz dealership in Punjab, was acquired in August 2025 for approximately Rs 12 crore excluding inventory and contributed approximately Rs 150 crore of FY26 revenue over eight months. RKS Motors, a Maruti Suzuki dealership in Telangana, was acquired in October 2025 for no more than Rs 93 crore excluding inventory and contributed approximately Rs 151 crore over six months. Olympus Motors, an Audi dealership across Telangana and Andhra Pradesh, was acquired in December 2025 for Rs 9.75 crore and contributed Rs 20 crore over three months.
Conclusion
Popular Vehicles’ FY26 mix indicates that the group’s earnings are more dependent on service, repair and parts activity than its revenue mix alone suggests. The separate PV analysis shows services and repairs generated Rs 98 crore of EBITDA from Rs 607 crore of income, with collision and repairs contributing 43% of service EBITDA and other service work contributing 57%.
The next updates should show whether additional authorised service centres, the Yanik platform and expanded parts distribution alter the recurring after-sales contribution. Integration of the three FY26 acquisitions also remains relevant, alongside geographic diversification: Keralam represented 53.4% of FY26 revenue, while Popular Vehicles said it achieved its target of reducing that contribution below 50% in H1FY27.