










Popular Vehicles’ Q2 revenue growth was 26% organic
Key highlights
- Popular Vehicles reported approximately 40% Q2FY27 revenue growth, including 26% organic growth.
- Three acquired businesses contributed Rs 200 crore of revenue in Q2FY27.
- Non-luxury PV recorded 31% organic revenue growth in Q2FY27.
- Q2FY27 EBITDA rose 56.8% to Rs 77.7 crore, with a 3.7% margin.
powered by IRIS
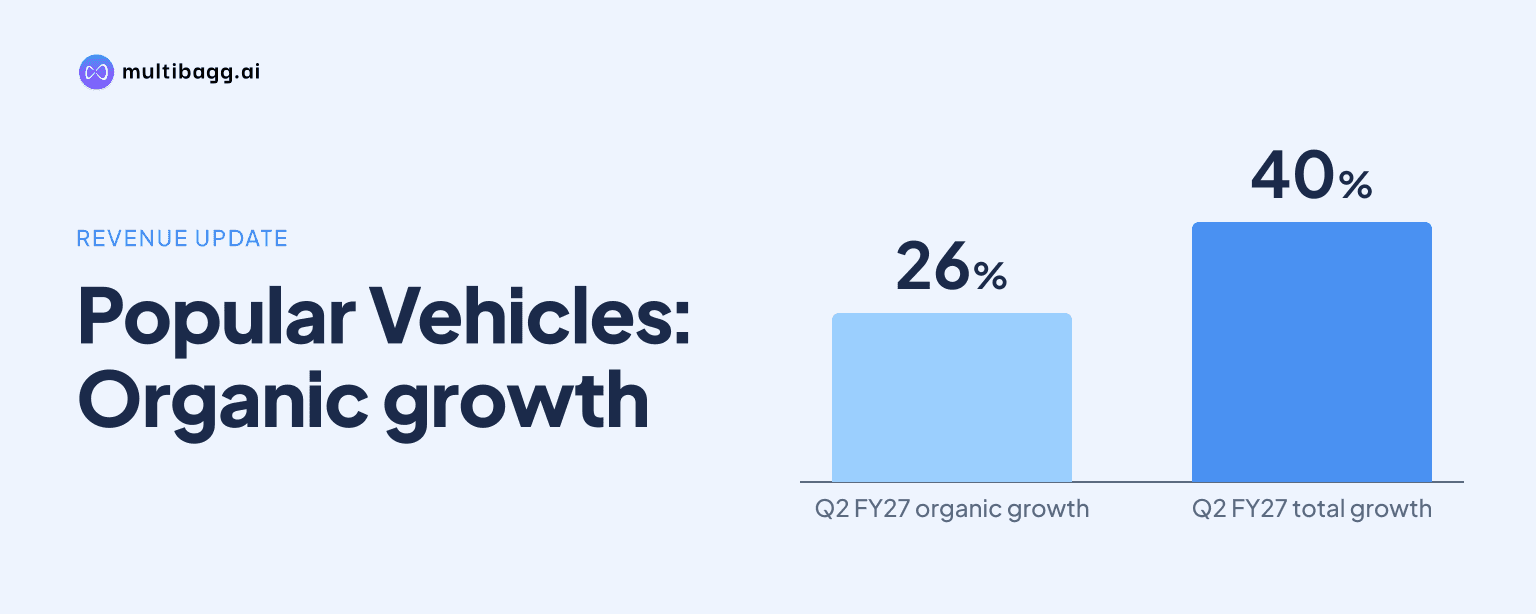
Popular Vehicles & Services reported approximately 40% year-on-year revenue growth in Q2FY27, of which 26% was organic after excluding acquisitions and network expansion, according to its business-highlight calculation. The distinction shows that existing operations contributed to growth alongside Rs 200 crore of revenue from three acquired businesses during the quarter.
Know Popular Vehicles & Services inside out
Results, valuation, peers and who's buying, in one view.
What drove Popular Vehicles’ Q2FY27 revenue growth?
Popular Vehicles’ approximate 40% Q2FY27 revenue growth combined 26% organic expansion with contributions from acquisitions and network additions. The 14-percentage-point difference between the two rates represents the stated effect of acquired businesses and network expansion within this business-highlight measure. The company excluded Honda and Piaggio volumes and revenue, which were accounted for only until August 2025, from these growth calculations.
Three acquired operations generated Rs 200 crore of Q2FY27 revenue: R.K.S Motors Private Limited, a Maruti Suzuki India Limited business, contributed Rs 115 crore; Globe CV Private Limited, a BharatBenz business, added Rs 52 crore; and Olympus Motors Private Limited, an Audi business, added Rs 33 crore. Management said the Punjab and Telangana acquisitions, completed nearly a year earlier, had been integrated and were scaling operations.
The business-highlight rate differs from the consolidated financial statement, where revenue from operations increased 36.0% to Rs 2,088.9 crore in Q2FY27 from Rs 1,535.7 crore in Q2FY26. Total income, which included Rs 4.8 crore of other income, rose 36.0% to Rs 2,093.8 crore. The company describes the business-highlight comparison as approximate and applies its stated exclusions.
How did Popular Vehicles’ new-vehicle sales change?
Popular Vehicles’ total new-vehicle volume grew 51% year on year in Q2FY27 on the business-highlight basis, while organic volume growth was 28%. Passenger vehicle, or PV, volume increased 39% to 11,818 units from 8,498 units in Q2FY26. PV total income rose 48% to Rs 987 crore from Rs 667 crore, as management said premium and luxury vehicles grew faster than entry-level vehicles.
Commercial vehicle, or CV, volume rose 27% to 3,549 units, and CV total income increased 29% to Rs 581 crore. In the business highlights, CV volume grew 28%, including 26% organic growth, leaving a two-percentage-point difference. Management said CV growth was supported by organic and inorganic drivers despite macroeconomic challenges.
Electric vehicle, or EV, volume rose 115% to 3,685 units and EV total income increased 124% to Rs 63 crore. The business-highlight comparison showed 120% EV volume growth and 35% organic growth. Management attributed EV demand to Ather’s wider dealership presence, expanded product portfolio and recent launches.
Got a follow-up? Ask IRIS
Which Popular Vehicles revenue segments grew organically?
Popular Vehicles’ non-luxury PV business recorded the highest disclosed organic revenue growth, at 31% in Q2FY27, against total growth of 47%. Luxury PV revenue grew 53% overall but 19% organically. This means luxury PV had the highest reported segment growth, while non-luxury PV had the highest growth from the existing business under the company’s calculation.
CV revenue grew 28% overall and 23% organically, a five-percentage-point difference. EV and spare-parts distribution revenue grew 42% overall and 15% organically, a 27-percentage-point difference. These comparisons show that the disclosed organic contribution was closest to total growth in CV and furthest from total growth in luxury PV, where the gap was 34 percentage points.
Network expansion included Yanik, the business-to-business e-commerce marketplace for automotive spare parts operated by step-down subsidiary ZPAREX Disolutions Private Limited. Yanik began full-scale commercial operations with more than 13,000 verified parts for spare-parts dealers and independent garages. Popular Vehicles also opened one Maruti Suzuki India Limited service centre at Karukachal, Kerala, and one Tata Motors CV service centre at Kayamkulam, Kerala.
Did Popular Vehicles’ service income rise with workshop volume?
Popular Vehicles’ total service volume grew 17% year on year in Q2FY27, while organic service-volume growth was 5%. PV service volume increased 5% to 196,652 units, but PV service income grew 22% to Rs 181 crore from Rs 148 crore. Management attributed the faster income increase to a higher mix of high-value service jobs.
CV service volume increased 9% to 54,906 units and service income rose 15% to Rs 100 crore. Management said increasing vehicle complexity and service intensity supported higher realisations. EV service volume grew 59% to 15,792 units, while EV service income increased 64% to Rs 4 crore, with management citing Ather’s growing vehicle parc and service network.
The business-highlight service comparison showed 5% organic volume growth in both non-luxury PV and CV, compared with 12% in luxury PV and 18% in EV. Luxury PV service volume grew 86% overall, leaving a 74-percentage-point gap to its organic rate. EV service volume grew 75% overall, compared with 18% organic growth.
What did Popular Vehicles report on earnings and inventory?
Popular Vehicles reported earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 77.7 crore in Q2FY27, up 56.8% from Rs 49.5 crore in Q2FY26. EBITDA margin increased to 3.7% from 3.2%, although gross profit margin declined to 12.8% from 13.7%. Profit before tax and exceptional items was Rs 4.3 crore, compared with a Rs 3.6 crore loss a year earlier.
Inventory was Rs 920.3 crore at September 2026, compared with Rs 617.4 crore at March 2026. Management said it built vehicle inventory for festive-season availability and expects levels to normalise over the coming months. H1FY27 revenue from operations rose 39.7% to Rs 3,983.9 crore, while EBITDA increased 70.4% to Rs 149.8 crore and margin reached 3.7% from 3.1%.
Conclusion
Popular Vehicles’ Q2FY27 data separates expansion-led growth from existing-business growth: the company reported approximately 40% revenue growth on its business-highlight measure, including 26% organic growth. Non-luxury PV led disclosed organic revenue growth at 31%, followed by CV at 23%, luxury PV at 19%, and EV and spare-parts distribution at 15%, while service volumes grew 5% organically overall.
The next disclosures to watch are management’s FY27 revenue-growth guidance of 20% to 25% over FY26, the scaling of Punjab and Telangana operations, and post-festive inventory movement from Rs 920.3 crore at September 2026. Management also expects earnings momentum to strengthen in coming quarters and is expanding Yanik and its BKT tyre-distribution business.