










Raconteur Global review qualified over loan and depreciation
Key highlights
- Raconteur Global’s Rs 80.802776737 crore loan to Dhull Trading was 42.57% of total group assets at 30 September 2026.
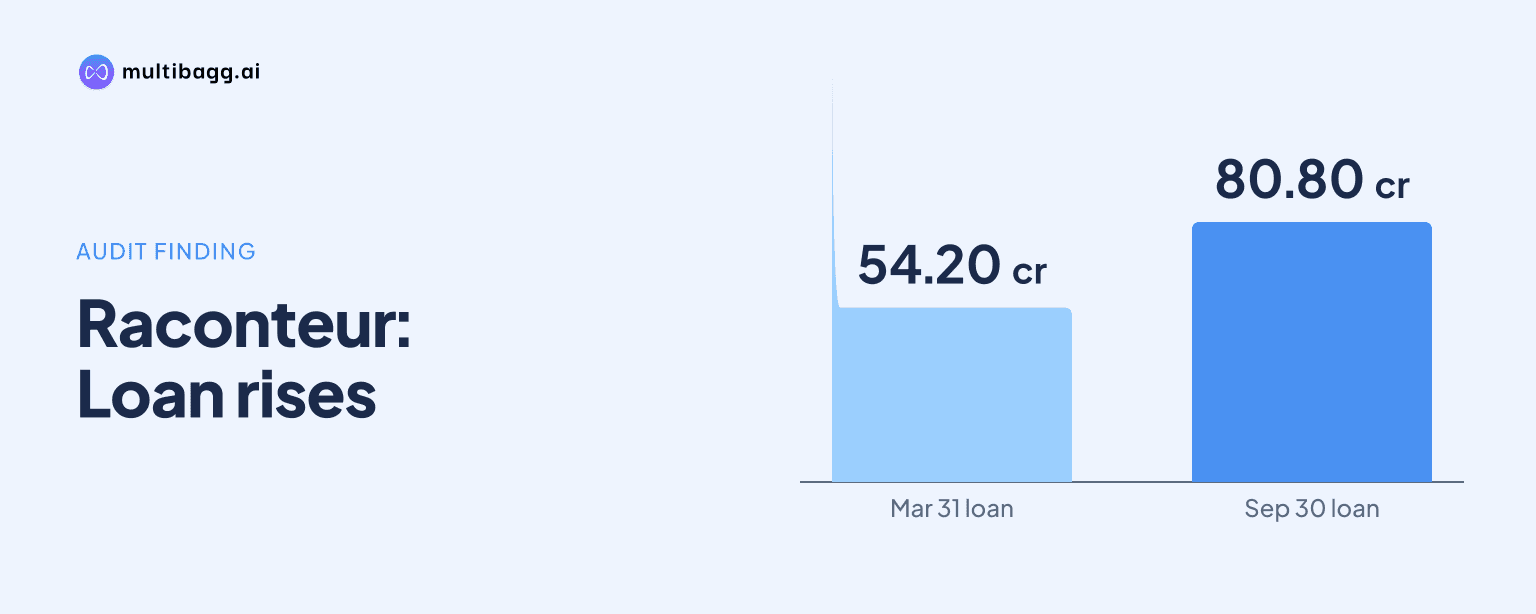
- The Dhull Trading loan rose by Rs 26.606235693 crore from Rs 54.196541044 crore at 31 March 2026.
- Raconteur Granite omitted half-year depreciation on fixed assets carried at Rs 1.209612493 crore.
- Raconteur Global reported Rs 2.9534 crore consolidated net profit for the half year ended 30 September 2026.
powered by IRIS
Raconteur Global Resources Limited received a qualified conclusion on consolidated unaudited results for the half year ended 30 September 2026 because an Rs 80.802776737 crore director-linked loan lacked a recoverability assessment and Raconteur Granite omitted depreciation on Rs 1.209612493 crore of fixed assets. The matters could affect reported loss, loans and advances, net worth and asset values.
Know Raconteur Global Resources inside out
Results, valuation, peers and who's buying, in one view.
What did Raconteur Global’s qualified review cover?
Raconteur Global’s qualified conclusion covered two accounting matters in its consolidated statement for the half year ended 30 September 2026: the recoverability and interest treatment of a related-party loan, and unprovided depreciation at Raconteur Granite. The reviewer said that, except for the possible effects of these matters, nothing had come to its attention indicating that the statement did not meet the disclosure requirements of Regulation 33 of the Securities and Exchange Board of India’s Listing Obligations and Disclosure Requirements Regulations, 2015.
The engagement was a limited review rather than an audit, conducted under Standard on Review Engagements 2410. The reviewer stated that this work primarily uses enquiries and analytical procedures and is substantially narrower than an audit, so it does not provide assurance that all significant matters would be identified. Raconteur Global’s board approved the unaudited consolidated results on 14 November 2026, prepared under Accounting Standard 25, or AS 25, on interim financial reporting and Accounting Standard 21, or AS 21, on consolidated financial statements.
The consolidated statement included Raconteur Granite, in which Raconteur Global held 70.81% at 30 September 2026; Skycrest Projects, a wholly owned subsidiary; and Rockbase Real Estate Projects, in which it held 51%. The qualification therefore concerns group reporting, rather than only Raconteur Global’s standalone financial results for the same six-month period.
How large was Raconteur Global’s related-party loan?
Raconteur Global’s unsecured loan to Dhull Trading Private Limited was Rs 80.802776737 crore at 30 September 2026, compared with Rs 54.196541044 crore at 31 March 2026. The balance therefore rose by Rs 26.606235693 crore in the six months. Dhull Trading is an entity in which a director of Raconteur Global is interested, according to the reviewer’s basis for qualified conclusion.
The reviewer said the balance represented 57.41% of group loans and advances and 42.57% of total group assets at 30 September 2026. The consolidated balance sheet reported long-term loans and advances of Rs 137.7659 crore and total assets of Rs 189.7909 crore. This establishes that the identified related-party balance formed a material part of both lending-related assets and the consolidated asset base.
No assessment of the loan’s recoverability was made available to the reviewer. It consequently could not determine whether Raconteur Global should record a provision. The filing does not estimate any possible provision, but states that one, if required, would increase consolidated net loss and reduce loans and advances and net worth.
Why did loan interest create a reporting issue for Raconteur Global?
Raconteur Global did not recognise interest income on the Dhull Trading loan during the half year ended 30 September 2026. Management stated that it intended to account for the interest at the year end. The reviewer said this was contrary to Accounting Standard 9 on revenue recognition and AS 25, which require interest to be recognised in the period in which it accrues.
The filing does not disclose the interest rate, loan tenure, repayment schedule or the amount of interest that accrued during the six months. As a result, the specific effect of the non-recognition on the reported Rs 2.9534 crore consolidated net profit cannot be calculated from the announcement. The issue concerns timing of income recognition in addition to the unresolved question of loan recovery.
Raconteur Global reported total consolidated other income of Rs 1.0167 crore for the half year ended 30 September 2026, compared with Rs 4.1822 crore for the half year ended 31 March 2026. The reviewer separately identified the unrecognised interest on Dhull Trading, but the statement does not break down other income sufficiently to isolate interest income or reconcile the effect of the loan’s missing accrual.
Got a follow-up? Ask IRIS
Why was depreciation at Raconteur Granite not provided?
Raconteur Granite did not provide depreciation for the half year ended 30 September 2026 on property, plant and equipment carried at Rs 1.209612493 crore. The reviewer said the omission was not in accordance with Accounting Standard 10 on property, plant and equipment and Schedule II of the Companies Act, 2013.
The announcement does not disclose the depreciation that should have been charged, so it does not quantify the effect on consolidated expenses, profit or carrying values. The reviewer’s stated implication is nevertheless clear: a depreciation charge would increase the group’s expense and reduce the relevant property, plant and equipment balance for the six-month period.
Raconteur Global reported consolidated depreciation and amortisation expense of Rs 83.4 lakh for the half year ended 30 September 2026, compared with Rs 76.7 lakh for the half year ended 31 March 2026. That reported amount excludes the depreciation Raconteur Granite did not provide, according to the review report, meaning the period comparison does not represent a like-for-like measure of group depreciation.
The group’s consolidated property, plant and equipment was Rs 2.3747 crore at 30 September 2026, down from Rs 2.7005 crore at 31 March 2026. Raconteur Granite’s Rs 1.209612493 crore carrying value was about half of the group total, although the announcement does not provide a subsidiary-level reconciliation of additions, disposals or depreciation.
Were Raconteur Global’s subsidiaries auditor-reviewed?
No, interim financial information for Raconteur Granite, Rockbase Real Estate Projects and Skycrest Projects was not reviewed by their auditors. Instead, management certified the information and furnished it to the consolidated reviewer. The reviewer said its conclusion on the amounts and disclosures relating to those three subsidiaries was based solely on management-certified interim financial information.
The reviewer did not modify its conclusion because of this other matter. However, it specifically distinguished the source of subsidiary information from independently reviewed financial information. That distinction is relevant to the qualification because the omitted depreciation arose at Raconteur Granite, a 70.81%-held subsidiary at 30 September 2026.
On the reported consolidated basis, Raconteur Global recorded revenue of Rs 5.9105 crore and total expenses of Rs 8.8639 crore in the September 2026 half year, compared with Rs 7.9028 crore and Rs 28.4392 crore, respectively, in the March 2026 half year. The statement reported net profit of Rs 2.9534 crore after a Rs 20.5475 crore net loss in the preceding half year, subject to the effects of the two qualified matters.
Consolidated short-term borrowings increased to Rs 105.8528 crore at 30 September 2026 from Rs 65.7346 crore at 31 March 2026, while long-term borrowings rose to Rs 46.6105 crore from Rs 39.6876 crore. Finance costs also increased to Rs 4.7211 crore from Rs 3.8762 crore across the two half-year periods, while the announcement does not provide a breakdown of borrowings by group entity.
Conclusion
Raconteur Global’s reported Rs 2.9534 crore consolidated net profit for the half year ended 30 September 2026 is subject to a qualified review conclusion over two unresolved accounting matters. The Rs 80.802776737 crore related-party loan lacks a recoverability assessment and accrued half-year interest recognition, while Raconteur Granite did not provide depreciation on Rs 1.209612493 crore of property, plant and equipment. Subsidiary interim information was also management-certified rather than auditor-reviewed.
The next financial statements should show whether management assesses and provides for any unrecoverable portion of the Dhull Trading loan, recognises interest in the period of accrual and records depreciation at Raconteur Granite. Investors can also watch the loan balance after its Rs 26.606235693 crore rise between 31 March 2026 and 30 September 2026, alongside the group’s borrowing and finance-cost movements.