










Raconteur Global Resources auditor flags Rs 80.80 crore loan
Key highlights
- Raconteur Global Resources’ unsecured loan to Dhull Trading Private Limited was Rs 80.80 crore at 30 September 2026.
- The related-party loan rose by Rs 26.61 crore from Rs 54.20 crore at 31 March 2026.
- The loan represented 68.17% of standalone assets and 42.57% of consolidated assets.
- Raconteur Global Resources reported a standalone net loss of Rs 2.31 crore for the half year ended 30 September 2026.
powered by IRIS
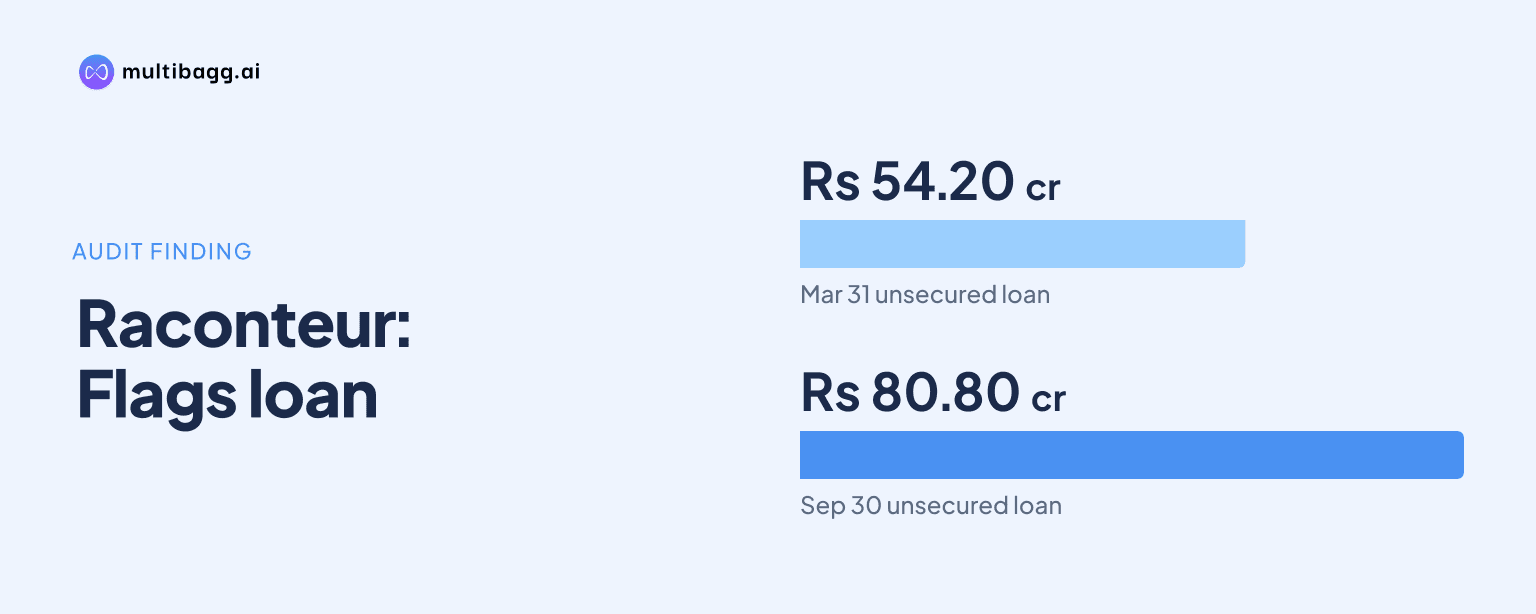
Raconteur Global Resources Limited received a qualified limited-review conclusion for the half year ended 30 September 2026 because its Rs 80.80 crore unsecured loan to related party Dhull Trading Private Limited had no recoverability assessment available to the auditor and no interest recognised for the half year. The loan represented 68.17% of standalone total assets.
Know Raconteur Global Resources inside out
Results, valuation, peers and who's buying, in one view.
What did the auditor flag at Raconteur Global Resources?
The auditor flagged Raconteur Global Resources’ unsecured loan of Rs 80.80 crore to Dhull Trading Private Limited, an entity in which a director is interested, as at 30 September 2026. Kapil Sandeep and Associates said that no assessment of the loan’s recoverability was made available during its limited review of the standalone financial statements.
The lack of an assessment meant the auditor could not determine whether Raconteur Global Resources should make a provision against the Rs 80.80 crore balance. The review report states that any required provision would increase the company’s net loss and reduce its loans and advances and net worth, but it does not quantify the possible provision.
The auditor also said Raconteur Global Resources had not recognised interest on the Dhull Trading Private Limited loan for the half year ended 30 September 2026. Management told the auditor it intended to account for the interest at year-end, whereas the report says Accounting Standard 9 on Revenue Recognition and Accounting Standard 25 on Interim Financial Reporting require interest recognition in the period in which it accrues.
The standalone review was a limited review, rather than an audit, for the period ended 30 September 2026. The auditor said such a review provides moderate assurance and is based primarily on inquiries of company personnel and analytical procedures, before issuing a qualified conclusion because of the possible effects of the loan matter.
How large is the Dhull Trading loan relative to assets?
The Dhull Trading Private Limited balance was Rs 80.80 crore, equal to 80.04% of Raconteur Global Resources’ standalone loans and advances and 68.17% of standalone total assets at 30 September 2026. The company’s standalone balance sheet reported total assets of Rs 118.54 crore and long-term loans and advances of Rs 93.00 crore.
The balance had increased by Rs 26.61 crore from Rs 54.20 crore at 31 March 2026. That movement occurred over the six months to 30 September 2026, while the company’s standalone total assets rose from Rs 85.91 crore at 31 March 2026 to Rs 118.54 crore at the half-year date.
The balance-sheet presentation also shows short-term loans and advances of Rs 7.96 crore at 30 September 2026, alongside the Rs 93.00 crore long-term category. The review report’s 80.04% measure refers to total standalone loans and advances, while the balance sheet separates the amounts by duration.
Got a follow-up? Ask IRIS
How does the consolidated position differ from the standalone position?
The loan accounted for a smaller share of the consolidated group, but remained Rs 80.80 crore at 30 September 2026. In the consolidated review report, the auditor said it represented 57.41% of group loans and advances and 42.57% of total consolidated assets.
Raconteur Global Resources’ consolidated balance sheet reported assets of Rs 189.79 crore at 30 September 2026, compared with standalone assets of Rs 118.54 crore. Consolidated long-term loans and advances were Rs 137.77 crore and short-term loans and advances were Rs 2.97 crore, producing a broader asset and advances base than in the parent-only accounts.
The consolidated conclusion contained a second qualification concerning Raconteur Granite Limited, a 70.81%-held subsidiary. The auditor said the subsidiary had not provided depreciation for the half year on property, plant and equipment carried at Rs 1.21 crore as at 30 September 2026, which it said was not in accordance with Accounting Standard 10 and Schedule II of the Companies Act.
The consolidated report additionally said interim financial information for Raconteur Granite Limited, Rockbase Real Estate Projects Limited and Skycrest Projects Limited had not been reviewed by their auditors. The information for those three subsidiaries was management-certified, and the auditor stated that its conclusion relating to those subsidiaries was based solely on that information; this matter did not modify its conclusion.
What do the half-year results show alongside the qualification?
Raconteur Global Resources reported a standalone net loss of Rs 2.31 crore for the half year ended 30 September 2026, against a loss of Rs 5.95 crore for the half year ended 31 March 2026. The auditor said an unquantified provision on the Rs 80.80 crore related-party loan, if required, would increase the reported loss.
Standalone total revenue was Rs 5.89 crore for the half year ended 30 September 2026, compared with Rs 7.78 crore in the half year ended 31 March 2026. Finance cost rose to Rs 4.07 crore from Rs 2.76 crore across those two reported half-year periods, while other income fell to Rs 1.00 crore from Rs 4.78 crore.
On a consolidated basis, Raconteur Global Resources reported net profit of Rs 2.95 crore for the half year ended 30 September 2026, compared with a consolidated loss of Rs 20.55 crore for the half year ended 31 March 2026. The consolidated revenue figure was Rs 5.91 crore, versus Rs 7.90 crore in the preceding reported half year, while finance cost increased to Rs 4.72 crore from Rs 3.88 crore.
The different standalone and consolidated outcomes reflect the inclusion of subsidiaries in the group statements, which comprise Raconteur Granite Limited, Skycrest Projects Limited and Rockbase Real Estate Projects Limited. The loan qualification applies to the parent’s balance in both reports, and the auditor said the absence of accrued interest could affect the period’s reported income and loss.
Conclusion
The qualification centres on a Rs 80.80 crore unsecured related-party balance that rose from Rs 54.20 crore in six months and comprised 68.17% of Raconteur Global Resources’ standalone assets at 30 September 2026. The auditor did not conclude that a provision was necessary, but said it could not assess that question without a recoverability assessment and identified unrecognised half-year interest as inconsistent with the cited accounting standards.
The next disclosed accounting step is management’s stated intention to account for interest at the year end. Readers will also be able to assess whether Raconteur Global Resources provides a recoverability assessment or provision for the Dhull Trading Private Limited loan, and whether Raconteur Granite Limited records depreciation on its Rs 1.21 crore property, plant and equipment balance in subsequent financial statements.