










RITES retains FY27 double-digit growth outlook after H1
Key highlights
- RITES retained its FY27 double-digit consolidated operating-revenue outlook after H1 growth of about 5%.
- Management said two to three milestones shifted by roughly 10-15 days from Q2 into Q3.
- RITES delivered 1 Bangladesh rake of 18 coaches and expects at least 2 more rakes in the rest of FY27.
- RITES reported a turnkey order book of about Rs 4,500 crore and a Mozambique locomotive order worth about Rs 150 crore.
powered by IRIS
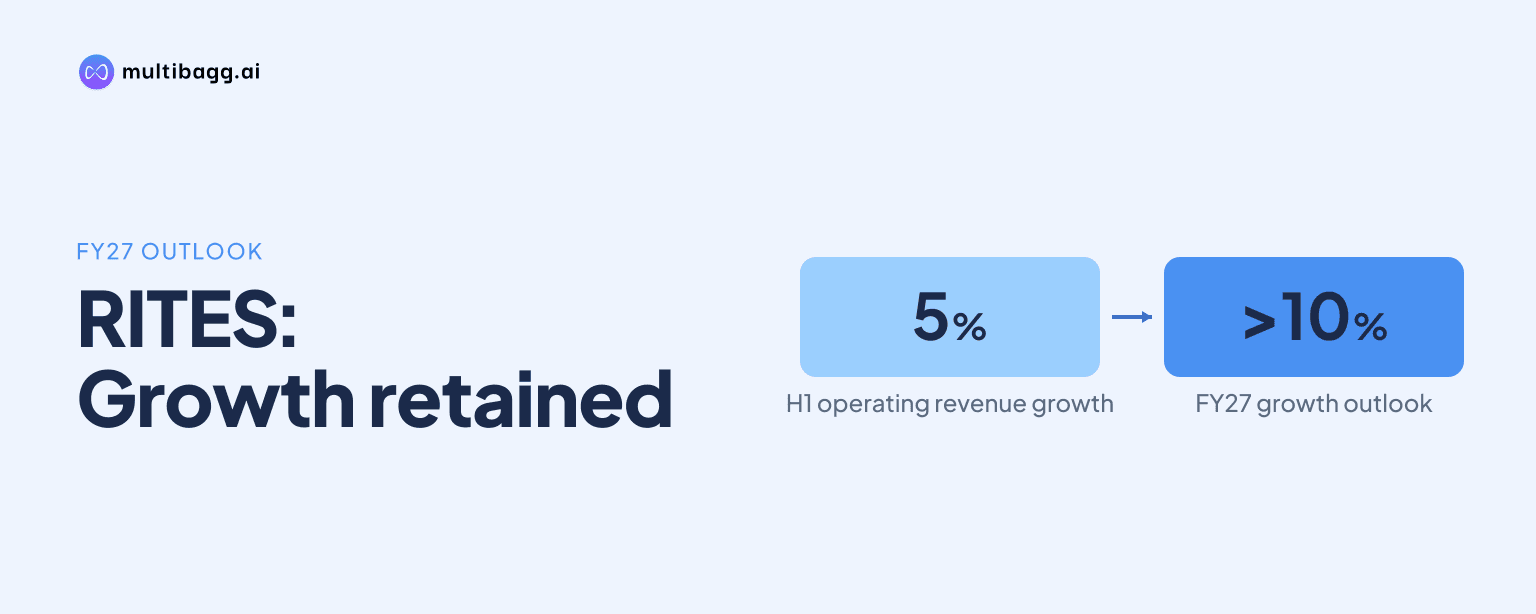
RITES Limited retained its FY27 double-digit consolidated operating-revenue growth outlook after H1 revenue grew about 5%, because management said two to three project milestones moved by roughly 10-15 days from Q2 into Q3. RITES expects faster second-half turnkey execution and rolling-stock export dispatches to support the target.
Know Rites inside out
Results, valuation, peers and who's buying, in one view.
Why is RITES retaining its FY27 growth guidance?
RITES is retaining its FY27 guidance because management said the muted Q2 and H1 performance resulted primarily from the timing of two to three revenue milestones, not from a change in its execution plan. Chairman and Managing Director Rahul Mithal said the milestones slipped by around 10-15 days into Q3, reducing both revenue and profit recognised in Q2 and H1.
An analyst on the November 5, 2026 call said H1 revenue rose about 5% year on year and Q2 revenue about 1.5%, estimating that growth of roughly 14-15% in the remaining quarters would be needed for a double-digit full-year outcome. Management maintained that its FY27 consolidated operating-revenue target remained on track, while noting that actual forward-looking outcomes can differ.
The delayed Bangladesh dispatch illustrates the timing issue. RITES had targeted the first rake for Q2, but said final checks and third-party inspections shifted it by about 10-12 days. Export revenue is recognised on final dispatch of the complete set, management said, so a short delay can defer a relatively large amount of revenue and associated profit between quarters.
What will drive RITES revenue in the second half?
RITES expects both turnkey work and exports to contribute more in H2 than in H1. Management said export booking was zero in Q2, while turnkey revenue increased by about Rs 70 crore year on year in that quarter. It expects the export contribution to resume as rolling-stock deliveries progress from Q4 onward.
The company described its turnkey order book as about Rs 4,500 crore, with many orders awarded roughly 12-18 months ago and now entering a more active execution phase. Management said these contracts are cost-plus turnkey arrangements rather than engineering, procurement and construction, or EPC, work, and that the underlying scope is mainly project management consultancy, or PMC.
RITES said the accounting treatment can inflate reported project value without changing the nature of its role. In management's example, a Rs 5 crore consultancy fee could be associated with a Rs 105 crore order value when a client elects to route the full project through RITES's profit and loss account. This increases revenue but can reduce the reported margin percentage because the denominator is larger.
When are RITES export orders expected to generate revenue?
RITES expects Bangladesh and Mozambique to be the principal rolling-stock export contributors in H2, although dispatch dates remain important for revenue recognition. One Bangladesh rake containing 18 coaches has been delivered, leaving nine rakes, or about 182 coaches. Management said the second rake should near completion in Q3 and that at least two rakes should be delivered during the remainder of FY27.
The Bangladesh contract covers 10 rakes, and management said the remaining seven are contractually required to be completed in FY28. It expects production to accelerate after the second rake as design, manufacturing and Bangladesh Railway acceptance procedures become more streamlined. The order therefore supports management's FY27 plan but also carries a substantial FY28 delivery component.
For Mozambique, RITES has an order for five locomotives valued at about Rs 150 crore. Management is aiming to have the first locomotive ready in Q4 and said the latest intended completion point for all five is H1 of the following financial year. Two developmental locomotives converted from broad gauge to Cape gauge are also ready for shipment to African markets, though management described those as prototype-led orders with a longer rollout.
A Sri Lanka opportunity was not yet a formal order on November 5. RITES had been declared lowest bidder, or L1, for five passenger multiple-unit sets of seven coaches each, valued at about Rs 400 crore, and was awaiting a letter of award, or LOA. Management said contractual delivery would be due within 12 months after the letter of credit is opened.
Got a follow-up? Ask IRIS
Can RITES hold its profit and margin thresholds?
RITES said it aims to keep consolidated earnings before interest, tax, depreciation and amortisation, or EBITDA, margins at 18-20% and profit-after-tax, or PAT, margins at 15-16%. Management cited consolidated EBITDA margin of 22% and PAT margin of 17% for the reported Q2 and H1 discussion, and called its stated ranges thresholds it did not expect to breach on quarterly, half-yearly or annual measures.
The quarter's revenue mix differed materially from a year earlier. Turnkey revenue was up about Rs 70 crore year on year in Q2, while export revenue was down about Rs 60 crore and no export was booked in the quarter. Management said exports should carry relatively higher margins than turnkey work as deliveries pick up, but did not raise its FY27 margin ranges.
Management said EBITDA margins above 25%, seen about five years earlier, were not expected to return because more work is now competitively won. More than 60% of the September 30 order book was competitive, versus about 37% nomination-based, while fresh order inflow was more than 70% competitive and about 27-28% nomination-based.
A further Q4 cost factor is the planned provision for the Eighth Pay Commission, effective from January 1, 2027. Management said the provision would be substantial, but had not finalised its value, and would begin in Q4. It nevertheless said it would try to surpass the previous year's profit despite this charge.
How are consultancy businesses contributing to the outlook?
RITES expects overall consultancy revenue to move toward double-digit growth in the near future, although management said upper-double-digit growth would be difficult immediately. More than 70% of fresh consultancy order inflow is now competitive across quality assurance, project consultancy and international consultancy, compared with a historically greater reliance on nominated work.
Quality assurance contributed more than 15% year-on-year growth to consultancy revenue in Q2, management said. Its work covers safety inspections of axles and rails, renewable-energy items, and products such as personal computers and tablets. RITES also cited recently won orders involving artificial-intelligence-based rail inspection tools.
RITES's subsidiary REMCL secured about seven to eight renewable-energy and net-zero consultancy orders in the preceding six months, with an order book of roughly Rs 10 crore. Some work began generating revenue in Q2. Management said a memorandum of understanding with the International Solar Alliance, signed on November 4, 2026, could support international consultancy opportunities.
Conclusion
RITES's FY27 outlook rests on converting delayed milestones into Q3 revenue and on a larger H2 contribution from a Rs 4,500 crore turnkey book and resumed exports. The first Bangladesh rake's 10-12-day delay shows why the company views the weak first half as a scheduling issue, while the higher competitive share of orders explains why management is maintaining, rather than raising, its 18-20% EBITDA margin range.
The next disclosed milestones are the expected Q3 near-completion of the second Bangladesh rake, deliveries of at least two Bangladesh rakes in the rest of FY27, and the targeted Q4 readiness of the first Mozambique locomotive. Investors can also watch for a Sri Lanka LOA, the size of the Eighth Pay Commission provision starting in Q4, and progress toward management's Rs 10,000 crore order-book target.