










RITES Ltd export revenue fell 98% in H1 as mix shifted
Key highlights
- RITES Ltd’s H1FY27 export revenue declined 97.6% to Rs 2 crore from Rs 64 crore.
- RITES Ltd’s H1FY27 turnkey revenue increased 39.2% to Rs 364 crore.
- RITES Ltd’s H1FY27 lease revenue rose 14.4% to Rs 98 crore and segment profit increased 30.2% to Rs 38 crore.
- RITES Ltd’s standalone H1FY27 profit after tax declined 1.6% to Rs 166 crore.
powered by IRIS
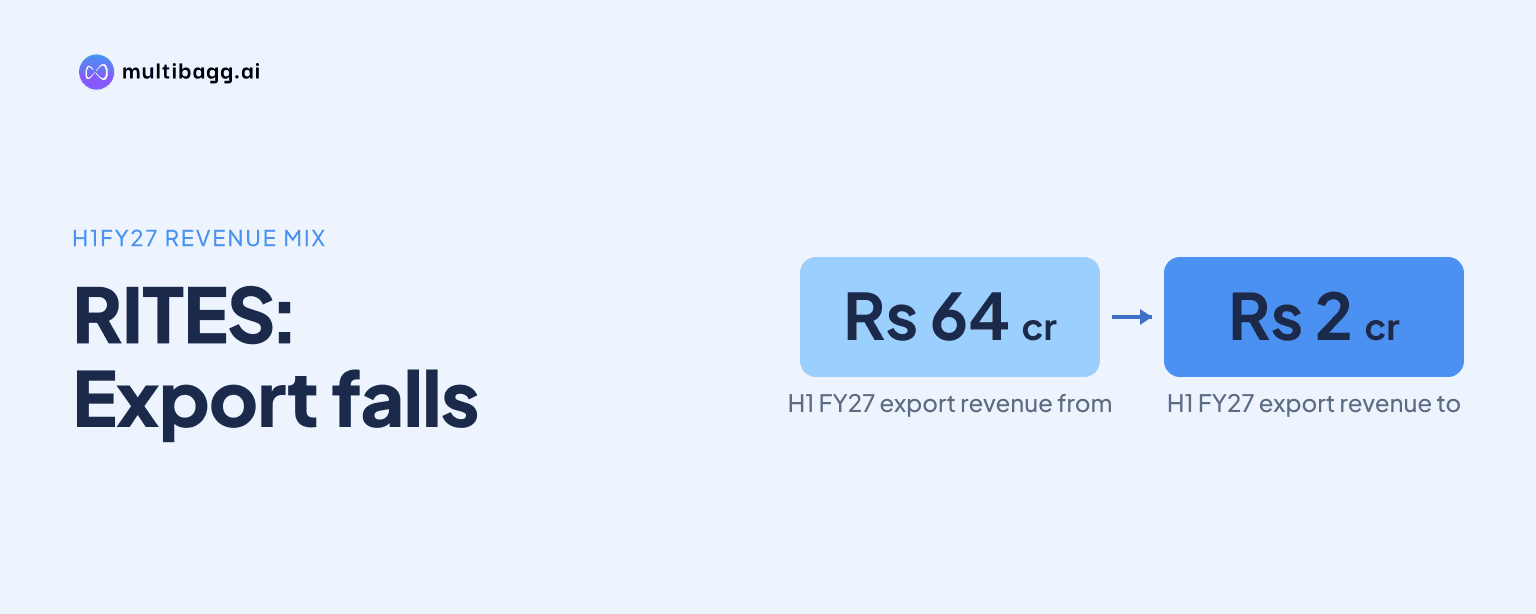
RITES LIMITED (RITES Ltd) reported standalone export revenue of Rs 2 crore in the first half of fiscal year 2027 (H1FY27), down 97.6% from Rs 64 crore in H1FY26, while turnkey revenue rose 39.2% to Rs 364 crore and lease revenue increased 14.4% to Rs 98 crore. Management expects supplies to Bangladesh Railways and ICVL Mozambique to build export momentum in H2FY27.
Know Rites inside out
Results, valuation, peers and who's buying, in one view.
Why did RITES Ltd’s export revenue decline in H1FY27?
RITES Ltd’s export revenue was Rs 2 crore in H1FY27, compared with Rs 64 crore in H1FY26, a 97.6% year-on-year fall. The export segment also recorded a Rs 2 crore loss in H1FY27, versus a Rs 6 crore profit a year earlier, with no segment margin reported for the current half.
The decline was also visible in the second quarter of FY27 (Q2FY27). Q2FY27 export revenue was reported as Rs 0 crore, against Rs 60 crore in Q2FY26, a fall of 99.2%. Export profit moved from Rs 6 crore in Q2FY26, carrying a 10.4% margin, to a Rs 2 crore loss in Q2FY27. RITES Ltd attributed the broader Q2 profit decline to lower exports and a changed revenue mix.
Management said the export pickup had begun in Q3FY27 through the supply of the first rake of coaches to Bangladesh through October. For H2FY27, RITES Ltd expects export revenue momentum from supplies to Bangladesh Railways and ICVL Mozambique. The presentation does not quantify the expected revenue, timing or profit contribution from the Mozambique supplies.
Which RITES Ltd businesses grew as exports fell?
RITES Ltd’s turnkey segment supplied the largest increase among the reported operating segments, with H1FY27 revenue rising by Rs 103 crore to Rs 364 crore from Rs 261 crore in H1FY26. That was growth of 39.2%, which management linked to better project execution. Turnkey revenue was therefore far larger than the Rs 2 crore generated by exports during the half.
Lease revenue increased by Rs 13 crore, or 14.4%, to Rs 98 crore in H1FY27 from Rs 85 crore in H1FY26. Management attributed the gain to locomotive additions and their utilisation. Consultancy, the largest reported segment by revenue, was nearly unchanged at Rs 557 crore, down 0.4% from Rs 559 crore, while other income rose 3.3% to Rs 70 crore.
The quarter showed the same direction, but with a sharper turnkey increase. Q2FY27 turnkey revenue rose 65.9% to Rs 187 crore from Rs 113 crore, while lease revenue gained 14.5% to Rs 49 crore from Rs 43 crore. Consultancy revenue fell 4.3% to Rs 285 crore and other income decreased 9.2% to Rs 43 crore, indicating that growth was concentrated in turnkey and leasing rather than spread across all reported lines.
Got a follow-up? Ask IRIS
How did RITES Ltd’s segment profits change in H1FY27?
RITES Ltd’s lease segment delivered the largest reported profit increase in H1FY27, with profit up 30.2% to Rs 38 crore from Rs 29 crore. Its margin expanded to 38.8% from 34.1%. Turnkey profit increased 54.4% to Rs 5 crore from Rs 4 crore, although its margin was 1.5%, compared with 1.3% in H1FY26.
Consultancy remained the largest reported profit contributor, producing Rs 179 crore in H1FY27, down 1.5% from Rs 182 crore. Its margin eased from 32.6% to 32.2%. The export business was the main negative movement, shifting from a Rs 6 crore profit and 8.6% margin to a Rs 2 crore loss, alongside the fall in export revenue.
Standalone earnings still declined despite the gains in lease and turnkey. H1FY27 earnings before interest, tax, depreciation and amortisation, or EBITDA, fell 2.9% to Rs 179 crore, while profit before tax declined 1.7% to Rs 218 crore and profit after tax fell 1.6% to Rs 166 crore. RITES Ltd said margins remained in its expected range, though standalone EBITDA margin decreased to 17.5% from 19.0%.
What does the changed business mix mean for RITES Ltd’s results?
RITES Ltd’s H1FY27 mix shifted away from exports, which had delivered Rs 64 crore of revenue and Rs 6 crore of profit a year earlier, toward turnkey execution and locomotive leasing. Turnkey added Rs 103 crore of revenue but generated Rs 5 crore of segment profit at a 1.5% margin. Lease added Rs 13 crore of revenue and Rs 9 crore of profit, at a 38.8% margin.
At the consolidated level, H1FY27 EBITDA was Rs 243 crore, down 3.1% from Rs 250 crore, and consolidated profit after tax was Rs 195 crore, down 2.6% from Rs 200 crore. Consolidated EBITDA margin reduced to 22.3% from 24.1%, while profit-after-tax margin moved to 17.0% from 18.3%. The company explicitly linked the fall in profits to the changed revenue mix.
The comparison uses restated H1FY26 segment revenue. RITES Ltd said it reclassified reversals of provisions from other operating income to expenses, requiring a restatement of the prior-period segmental figures. This means the stated 39.2% turnkey increase, 14.4% lease increase and 97.6% export decline are management’s comparable figures after that accounting presentation change.
At Q2 level, the standalone pattern was similar: EBITDA declined 6.6% to Rs 93 crore, profit before tax declined 8.5% to Rs 121 crore, and profit after tax fell 7.7% to Rs 94 crore. Management cited lower exports and revenue mix for the decline. Unallocable expenses were Rs 73 crore in H1FY27 versus Rs 66 crore in H1FY26, and Rs 37 crore in Q2FY27 versus Rs 34 crore in Q2FY26.
Conclusion
RITES Ltd’s reported H1FY27 business mix was materially different from H1FY26: export revenue dropped from Rs 64 crore to Rs 2 crore, while turnkey revenue grew to Rs 364 crore and lease revenue reached Rs 98 crore. Leasing expanded both revenue and segment profit, whereas turnkey added substantially more revenue at a 1.5% margin. The export shortfall coincided with lower standalone and consolidated margins and profits.
The next disclosed development to watch is execution of the Bangladesh coach supplies and the expected start of Mozambique supplies in H2FY27. Management expects these deliveries to restore export revenue momentum and generate export profits in the second half, but the presentation provides no export revenue target or specific delivery schedule for Mozambique.