










Route Mobile earmarks Rs 1,150-1,200 crore for acquisitions
Key highlights
- Route Mobile has around Rs 1,150 crore to Rs 1,200 crore of free cash for potential acquisitions.
- Management identified Latin America, Saudi Arabia and selected Southeast Asian markets for expansion evaluations.
- Route Mobile reported second-quarter gross profit of Rs 264 crore, up 6.8% year on year.
- Second-quarter adjusted EBITDA was Rs 118.4 crore, with an adjusted EBITDA margin of 10%.
powered by IRIS
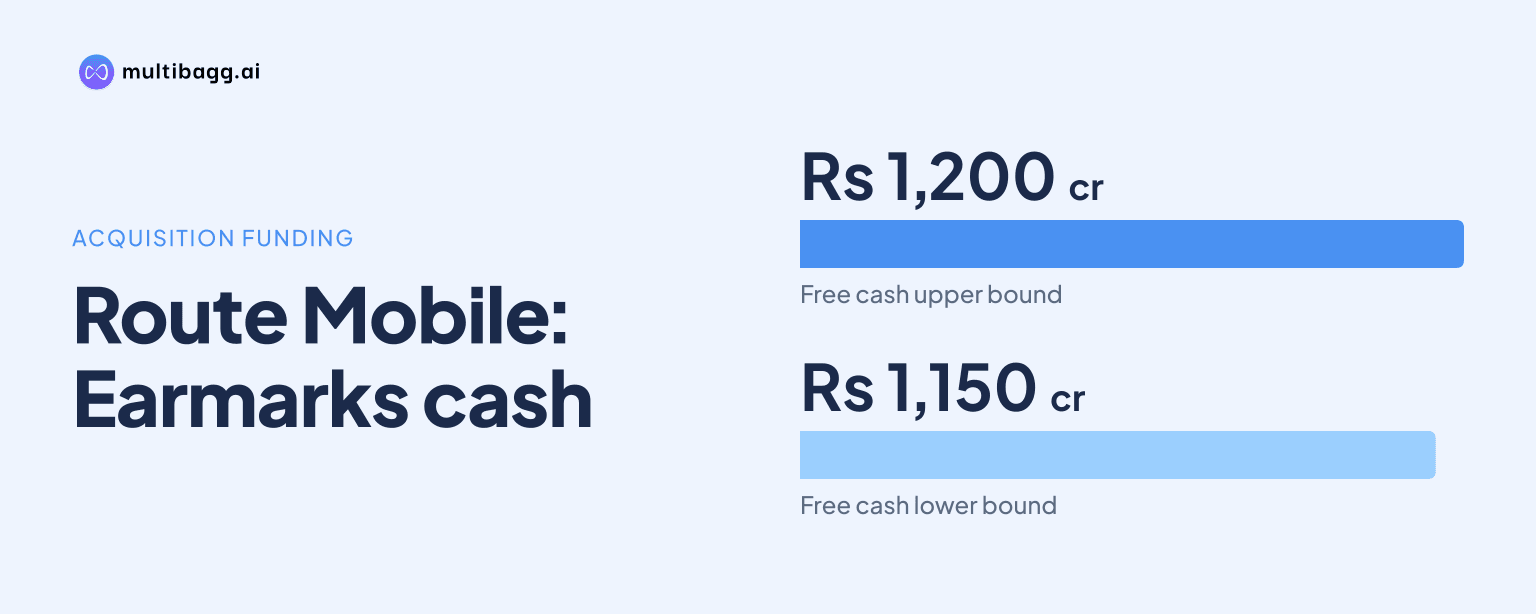
Route Mobile said it has Rs 1,150 crore to Rs 1,200 crore of free cash available for acquisitions, with management prioritising product and geographic expansion in Latin America, Saudi Arabia and Southeast Asia. No transaction has reached an agreement stage, but management said inorganic growth is the primary intended use of the cash.
Know Route Mobile inside out
Results, valuation, peers and who's buying, in one view.
How much free cash does Route Mobile have for acquisitions?
Route Mobile has around Rs 1,150 crore to Rs 1,200 crore of free cash for potential acquisitions, management said during the call. The disclosure followed an analyst's reference to a Rs 1,350 crore cash balance, although management did not provide a reconciliation between that balance, deposits and the stated free-cash range.
Management said dividends remain a possible but marginal use of the money, while acquisitions are its primary objective. It is evaluating targets for market and product expansion, but described reviews of business performance, valuation and transaction structure as early-stage work rather than signed deals.
The Rs 50 crore spread between the lower and upper ends of the range was not explained on the call. Route Mobile also did not disclose a maximum deal value, financing plan, expected closing date or a deadline after which it would consider a buyback or a larger dividend.
Which markets is Route Mobile evaluating for acquisitions?
Route Mobile is evaluating opportunities in Latin America, Saudi Arabia and selected Southeast Asian markets. Management said it sees a couple of Latin American markets as particularly interesting, called Saudi Arabia a market growing at a good pace, and said it is speaking to a few select companies in Southeast Asia.
Latin America is a focus for advanced conversational artificial intelligence, or AI, solution providers. Management said the region's margin profiles are attractive and that the size and scale of potential assets fit Route Mobile's deal-size criteria, making it suitable for transactions that it believes it can execute.
In Southeast Asia, Route Mobile did not identify countries or targets, but said it is considering large markets and companies that are immediate contenders for market share. It said these are not necessarily the largest operators in their markets, indicating that the review is aimed at selected capabilities and positions rather than scale alone.
Saudi Arabia was presented as a separate geographic opportunity, with management referring to it as KSA during the call. Route Mobile did not assign any part of the Rs 1,150 crore to Rs 1,200 crore free-cash pool to Latin America, Saudi Arabia or Southeast Asia, so the relative allocation across regions remains undisclosed.
Got a follow-up? Ask IRIS
What capabilities does Route Mobile want to add?
Route Mobile said it is not seeking SMS leaders and instead wants businesses that are stronger in alternative communication channels, including conversational AI. This fits its existing emphasis on WhatsApp, Rich Communication Services, or RCS, and other newer products alongside its core messaging traffic.
The product rationale follows a second quarter in which gross profit reached Rs 264 crore, up 6.8% year on year and 9.8% sequentially. Management attributed the increase primarily to the new-products portfolio, which it said carries higher margins than core messaging traffic, while gross margin rose to 22.4% from 22.1% a year earlier and 20.9% in the previous quarter.
New products contributed one-tenth of Route Mobile's revenue, according to management. The acquisition contribution within that portfolio was about Rs 5 crore in the quarter, while management said the rest of the growth was organic, suggesting that its prior acquisition added product capability without being the main source of the portfolio's current revenue increase.
Management also expects seasonal marketing communication to be spread across SMS, WhatsApp and RCS rather than concentrated in SMS. RCS prices changed from September 1, with marketing rates nearly doubling from earlier levels, while WhatsApp had no major price change; Route Mobile said the eventual split between RCS and WhatsApp remains uncertain.
Why is Route Mobile putting acquisitions ahead of shareholder payouts?
Route Mobile is putting acquisitions ahead of major shareholder distributions because management sees expansion opportunities in selected markets and products. It said it is absolutely keen to use the available money for expansion, while describing dividends as marginal and not announcing a buyback, payout amount or payout timetable.
The approach remains an intention rather than deployed capital. Management said Latin American opportunities are still being assessed for performance, valuation and structure, and Southeast Asian interactions are with a select group of potential targets. It did not state that its board had approved a specific transaction or a deadline for completing one.
Route Mobile is also pursuing an operating plan that management says could support the acquisition agenda. It reconfirmed revenue-growth guidance at the midpoint of its earlier mid- to high-single-digit range and is working toward an adjusted earnings before interest, tax, depreciation and amortisation, or EBITDA, margin of around 12%.
In the second quarter, adjusted EBITDA was Rs 118.4 crore, up 8.7% sequentially, and the adjusted EBITDA margin was 10%, 50 basis points above the preceding quarter. Management said non-recurring Masivian security-incident costs and performance-bonus provisions affected first-half margins, and it is targeting high-margin pipeline conversion, cost optimisation and seasonal demand to move towards around 12%.
Conclusion
Route Mobile's stated capital-allocation direction is to use Rs 1,150 crore to Rs 1,200 crore of free cash for acquisitions rather than substantial near-term distributions. Its target profile combines geographic entry, particularly in Latin America, Saudi Arabia and Southeast Asia, with product expansion in conversational AI and alternative communication channels that management associates with its newer, higher-margin portfolio.
The next development to watch is whether early evaluations produce signed transactions and disclose valuation, structure and funding details. Management also expects seasonal activity in the October-November-December period, a Masivian business revival after its security incident, and progress toward around 12% adjusted EBITDA margin as one-off costs moderate and high-margin opportunities convert.