










Route Mobile new products cross 10% of Q2 revenue mix in FY27
Key highlights
- Route Mobile’s new-products revenue rose 36.7% year on year to Rs 128 crore in Q2 FY27.
- New products contributed more than 10% of Route Mobile revenue in Q2 FY27, versus about 8% a year earlier.
- Route Mobile’s gross profit margin rose to 22.4% in Q2 FY27 from 20.9% in Q1 FY27.
- Route Mobile acquired Heltar for Rs 33.7 crore, completing the transaction on July 29, 2026.
powered by IRIS
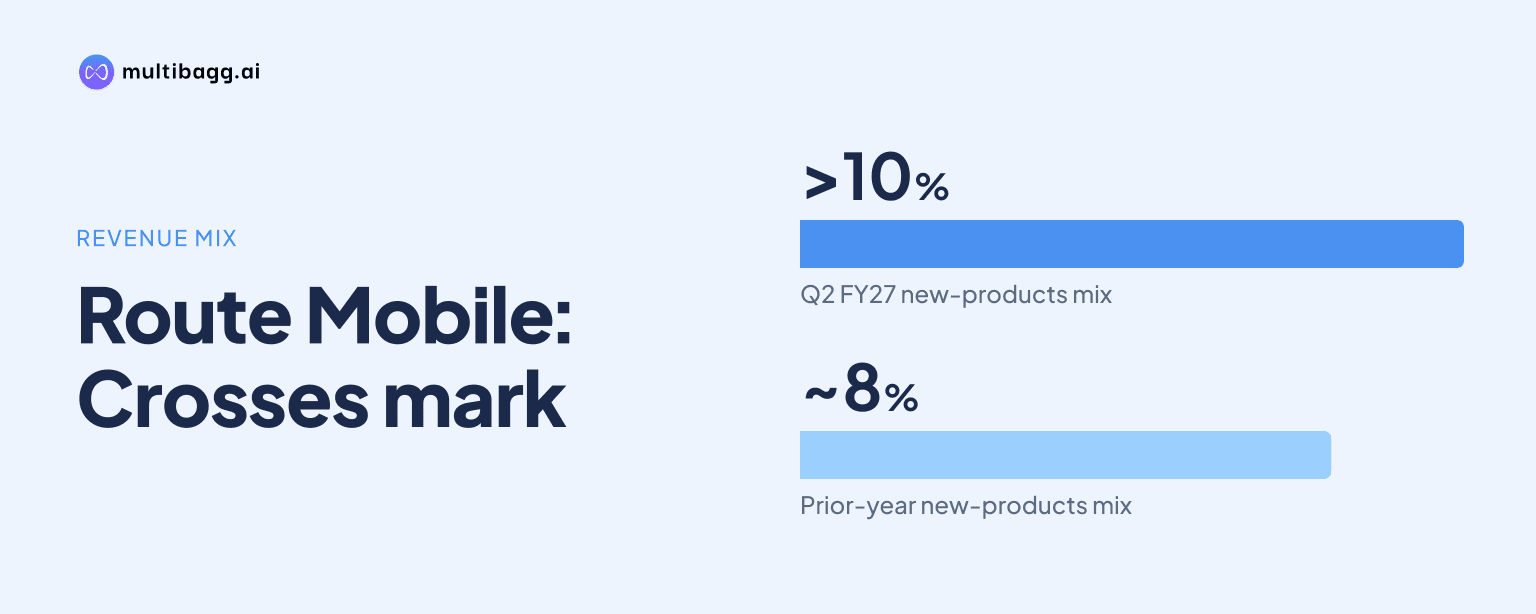
Route Mobile Limited reported that its new-products portfolio rose 36.7% year on year to Rs 128 crore in the second quarter of fiscal year 2027 (Q2 FY27), taking its contribution above 10% of revenue after it added Heltar’s artificial intelligence, or AI, native customer-engagement capabilities in July 2026.
Know Route Mobile inside out
Results, valuation, peers and who's buying, in one view.
How much did Route Mobile’s new-products revenue grow?
Route Mobile’s new-products revenue grew 36.7% year on year and 35.8% quarter on quarter to Rs 128 crore in Q2 FY27. The portfolio comprises Rich Communication Services, or RCS, WhatsApp and other Internet Protocol, or IP-based, messaging solutions, and it contributed more than one-tenth of quarterly revenue, compared with about 8% a year earlier.
The portfolio expanded faster than Route Mobile’s overall business in Q2 FY27. Revenue from operations reached Rs 1,180 crore, up 5.4% year on year and 2.4% sequentially, while new products grew at more than six times the company’s reported year-on-year rate; first-half FY27 revenue was Rs 2,331 crore, up 7.4% year on year.
Route Mobile said growth came from conversational commerce, customer care and banking journeys, as well as RCS supported by wider direct operator coverage. Its international long-distance, or ILD, business continued to face growth challenges, and management said it was managing that activity for absolute gross profit rather than volume.
What did the Heltar acquisition add to Route Mobile?
Heltar added an AI-native, no-code engagement layer across Route Mobile’s existing communications channels. Route Mobile signed the business transfer agreement for Heltar Technologies’ AI-driven customer-engagement business on July 13, 2026, and completed the slump-sale acquisition on July 29, 2026.
The total consideration was Rs 33.7 crore, including Rs 23.9 crore paid at closing from internal accruals and Rs 9.8 crore deferred for payment 18 months after closing. Route Mobile said the transaction extended its offering beyond short message service, or SMS, across WhatsApp, RCS, voice and communications analytics, while adding customer-journey orchestration for enterprise customers in India and international markets.
Heltar is being sold through Route Mobile and Proximus Global sales teams, while its core product-development team remains responsible for development and is being strengthened through targeted hiring. Route Mobile said several blue-chip enterprises were already live when it acquired Heltar, with early wins across banking, healthcare, retail, consumer durables and education, plus opportunities emerging in the Middle East and Latin America.
Route Mobile cited two India use cases: a healthcare provider uses Heltar on WhatsApp for appointment booking, doctor search, test reports and hospital information, while a fashion brand uses it for conversational commerce from product catalogues and recommendations through purchase. Management said Heltar could expand subscription-based and AI-led revenue and, over time, allow outcome-based pricing rather than pricing based only on transactions.
Got a follow-up? Ask IRIS
Did the shift in product mix improve Route Mobile’s margins?
Yes, Route Mobile’s gross profit margin recovered to 22.4% in Q2 FY27 from 20.9% in Q1 FY27 and exceeded the 22.1% recorded in Q2 FY26. Gross profit reached Rs 264 crore, rising 9.8% sequentially and 6.8% year on year, which management attributed primarily to higher-margin traffic from new products and existing customers.
The Q1 FY27 margin decline followed a temporary disruption in traffic from select large high-margin customers while Route Mobile deployed new solution capabilities for them. Management said it had not lost that business and described the Q2 recovery as progress in restoring it; a smaller part of the Q1 impact came from a security incident at Colombian subsidiary Masivian.
Route Mobile reported adjusted earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 118.4 crore in Q2 FY27, up 8.7% from Q1 FY27, with an adjusted EBITDA margin of 10%, or 50 basis points higher sequentially. Reported operating costs increased because of non-recurring Masivian security-incident effects and the timing of a performance-bonus provision, which management said would moderate in coming periods.
Management said it was using growth and cost-optimisation levers to return adjusted EBITDA margin to around 12%, which it said would result in mid-single-digit year-on-year EBITDA growth. Adjusted profit after tax was Rs 82.5 crore, down 17.8% year on year but up 20.4% sequentially in Q2 FY27.
What do Route Mobile’s customer and operator metrics show?
Route Mobile reported net revenue retention of 105% for H1 FY27. It defines recurring revenue as revenue from customers billed in every month of the relevant period, and recurring revenue represented 93% of revenue in the 12 months from September 2025 to September 2026, compared with 89% reported for FY26.
Non-recurring revenue can include one-time promotional and marketing campaigns, management said in response to an analyst question. Management also said a customer excluded from the recurring-revenue calculation in a particular month may return for a seasonal campaign, while some non-recurring revenue results from charging for solution-development work based on hours devoted.
Customer concentration eased during the disclosed period, with Route Mobile’s top five customers representing 30% of revenue against 33% in FY26. Financial services remained the largest vertical at 15% of revenue, followed by digital natives at 12%, while Route Mobile processed 47.6 billion billable transactions in Q2 FY27 and 93.4 billion in H1 FY27, about 11% more than in the prior-year first half.
Route Mobile is building its operator business alongside enterprise products, with AI-driven firewall solutions deployed at 12 operators as of the October 28, 2026 call. Management also identified network application programming interfaces being developed with the Proximus Global ecosystem as an additional growth opportunity.
Conclusion
Route Mobile’s Q2 FY27 disclosures show a measurable change in revenue mix: new products reached Rs 128 crore, rose 36.7% year on year and contributed more than 10% of revenue, versus about 8% a year earlier. The faster-growing product mix coincided with gross margin recovering to 22.4% from 20.9% in Q1 FY27, although ILD remained challenged and adjusted profit after tax was lower year on year.
The next disclosed execution points are conversion of high-margin firewall and new-product opportunities, Heltar’s expansion through Route Mobile and Proximus Global sales teams, and progress toward adjusted EBITDA margin of around 12%. Management also plans to scale Heltar across markets, following early wins in banking, healthcare, retail, consumer durables and education after the July 2026 acquisition.