










Route Mobile Targets 12% EBITDA Margin After Q2 Recovery
Key highlights
- Route Mobile reported Q2 FY27 revenue from operations of Rs 1,180 crore, up 5.4% year-on-year.
- Route Mobile’s gross profit margin rose to 22.4% in Q2 FY27 from 20.9% in Q1 FY27.
- Route Mobile reported adjusted EBITDA of Rs 118.4 crore and a 10% margin in Q2 FY27.
- Route Mobile’s new-products portfolio generated Rs 128 crore in Q2 FY27, up 36.7% year-on-year.
powered by IRIS
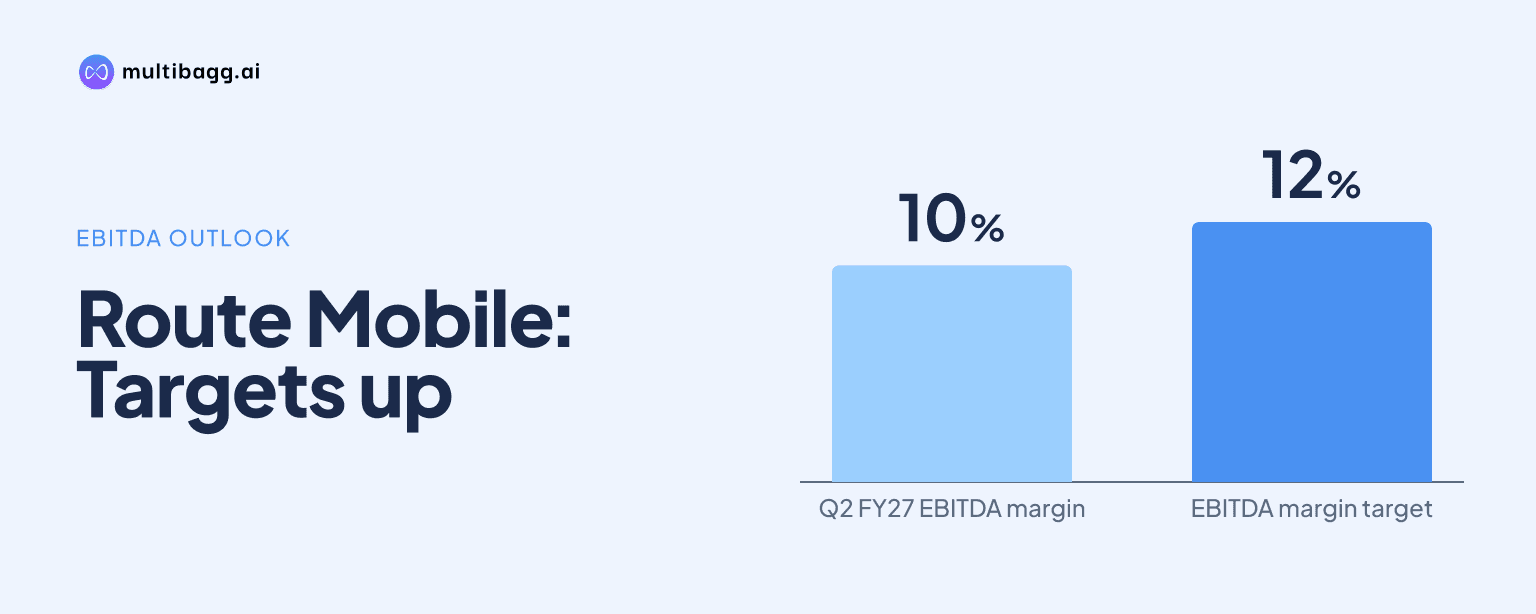
Route Mobile Limited is targeting an EBITDA margin of about 12% after reporting a 10% adjusted EBITDA margin in Q2 FY27, supported by gross profit margin rising to 22.4% from 20.9% in Q1 FY27 and management’s expectation that one-off costs will moderate. Revenue from operations was Rs 1,180 crore in the September 2026 quarter.
Know Route Mobile inside out
Results, valuation, peers and who's buying, in one view.
How did Route Mobile’s Q2 FY27 margins recover?
Route Mobile’s gross profit margin recovered to 22.4% in Q2 FY27, up 150 basis points from 20.9% in Q1 FY27 and 30 basis points from 22.1% in Q2 FY26. Gross profit reached Rs 264 crore, rising 9.8% sequentially and 6.8% year-on-year, while revenue increased 2.4% quarter-on-quarter and 5.4% year-on-year to Rs 1,180 crore.
The improvement came primarily from higher-margin traffic in new products and among existing customers, management said. Its new-products portfolio, including Rich Communication Services (RCS), WhatsApp and other Internet Protocol-based messaging products, generated Rs 128 crore in Q2 FY27, up 36.7% year-on-year and 35.8% sequentially. The portfolio contributed more than 10% of revenue, compared with about 8% a year earlier.
Adjusted EBITDA, or earnings before interest, tax, depreciation and amortisation, rose 8.7% sequentially to Rs 118.4 crore in Q2 FY27. The 10% adjusted EBITDA margin was 50 basis points above Q1 FY27. Adjusted profit after tax was Rs 82.5 crore, down 17.8% year-on-year but up 20.4% sequentially.
Why was Route Mobile’s EBITDA margin still 10%?
Route Mobile said operating costs increased from Q1 because of non-recurring expenses connected to a security incident at Masivian, its Colombian subsidiary, and the timing of a provision for performance-related bonuses. Management said these costs do not affect the ongoing cost run rate and should moderate in coming periods, benefiting EBITDA.
The Q1 FY27 gross profit margin of 20.9% had also reflected a temporary disruption in traffic from selected large, high-margin customers while Route Mobile deployed new solution capabilities. Management said that business had not been lost. The Q2 recovery to Rs 264 crore of gross profit reflected the return of higher-margin traffic and a richer new-products mix.
Management described the route from 10% adjusted EBITDA margin to about 12% as starting with the normalisation of one-off costs. It also cited seasonal campaigns, conversion of high-margin pipeline opportunities, increased new-products revenue and continuing cost optimisation. Management acknowledged that the plan carries execution considerations and did not provide a quarterly margin target.
What supports Route Mobile’s 12% EBITDA margin target?
Route Mobile is working toward an EBITDA margin of around 12%, which management said would lead to about 6% year-on-year EBITDA growth. It reconfirmed its revenue-growth outlook at the middle of its earlier mid- to high-single-digit range, citing sequential revenue growth and an expected recovery from H1 FY27 customer-specific items and non-recurring costs.
Seasonality is one of the identified contributors. Management expects communication activity to build during October, November and December as e-commerce and retail customers run campaigns. Route Mobile processed 47.6 billion billable transactions in Q2 FY27 and 93.4 billion in H1 FY27, with first-half volumes about 11% above the prior-year period.
Management expects campaign traffic to be split more across SMS, WhatsApp and RCS than in earlier seasonal periods. It said the mix between WhatsApp and RCS remains difficult to forecast following RCS price changes effective September 1. The company also expects a revival in Masivian’s business because its third quarter is typically a stronger period.
Got a follow-up? Ask IRIS
Which factors could affect Route Mobile’s margin plan?
Route Mobile’s international long-distance, or ILD, messaging business remains a constraint because management said the segment is not in a growth phase. The company reported some softness from aggregators but said it added direct enterprise traffic and contracts for messages sent from Indian banking platforms to overseas markets. Its focus in ILD is absolute gross profit rather than volume.
RCS pricing may also affect the seasonal product mix. Management said telecom operators increased RCS prices from September 1, with marketing pricing nearly doubling, while utility and authentication pricing changed marginally. Route Mobile said RCS volumes remained healthy, but management wants to assess brands’ response after the seasonal period; it reported no major WhatsApp pricing change.
Customer measures show both recurring activity and campaign variability. Net revenue retention was 105% in H1 FY27, while recurring revenue accounted for 93% of revenue in the 12 months to September 2026, compared with 89% in FY26. Route Mobile had 80 customers with annual billing above $1 million, versus 73 in FY26, while its five largest customers accounted for 30% of revenue, down from 33% a year earlier.
How can new products and firewall solutions lift Route Mobile’s mix?
Route Mobile completed the acquisition of Heltar Technologies’ AI-driven customer-engagement business on July 29, 2026, after signing the business transfer agreement on July 13. The slump-sale consideration was Rs 33.7 crore, including Rs 23.9 crore paid at closing from internal accruals and Rs 9.8 crore deferred for 18 months.
Management said Heltar added no-code customer-journey orchestration across WhatsApp, RCS, voice and communication analytics. About Rs 5 crore of Q2 FY27 new-product revenue came from the acquisition, management said, indicating that most of the Rs 128 crore portfolio was organic. Heltar is being sold through Route Mobile and Proximus Global sales teams, with early customer activity across banking, healthcare, retail, consumer durables and education.
Firewall is another margin-related opportunity. Route Mobile said its AI-driven firewall solutions were deployed with 12 operators, while firewall revenue remained a single-digit percentage of total revenue. Management said blended firewall gross profit margins were in the 50% to 60% range, with some customers generating up to 70%, and cited advanced customer discussions that it hopes to convert over the next few quarters.
Conclusion
Route Mobile’s Q2 FY27 margin recovery was visible first in gross profit, with margin increasing to 22.4% from 20.9% in Q1 and new-products revenue reaching Rs 128 crore. Adjusted EBITDA margin reached 10%, while management attributed the remaining gap to its roughly 12% objective to Masivian incident-related costs, the performance-bonus provision and further work needed on revenue mix and cost optimisation.
The next test is the October-November-December seasonal period, when management expects higher campaign volumes, a stronger Masivian contribution and greater use of WhatsApp and RCS. Investors will also watch whether Route Mobile converts its high-margin firewall pipeline, how customers respond to the September 1 RCS price increase, and whether the identified one-off costs recede in coming quarters.