










Sabrimala Q2 profit falls 37% as operating revenue stays nil
Key highlights
- Sabrimala reported Rs 7.35 lakh standalone net profit for the quarter ended 30 September 2026, down from Rs 11.68 lakh in the preceding quarter.
- Sabrimala reported nil revenue from operations in the September 2026 quarter, while other income was Rs 15.51 lakh.
- Sabrimala's trading segment posted a Rs 5.68 lakh loss before tax and interest in the September 2026 quarter.
- Sabrimala used Rs 1.4773 crore in operating activities for the period ended 30 September 2026.
powered by IRIS
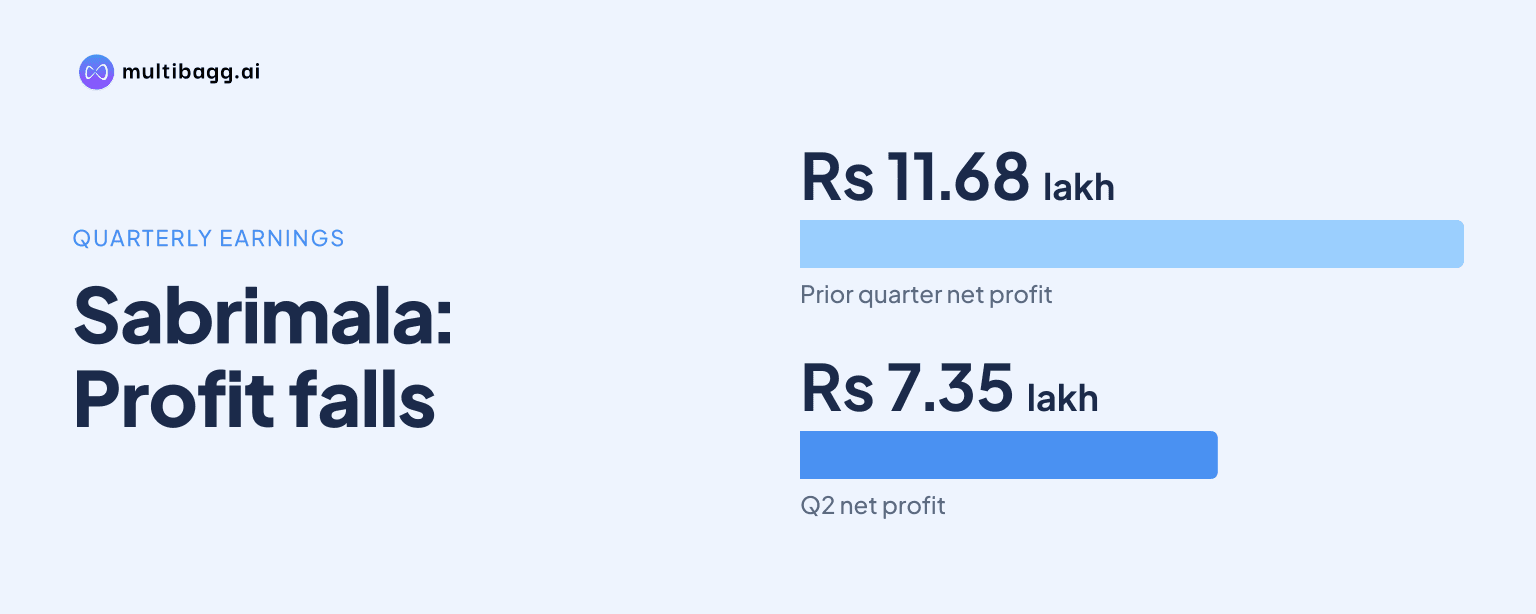
Sabrimala Industries India Limited reported standalone net profit of Rs 7.35 lakh for the quarter ended 30 September 2026, down 37.1% from Rs 11.68 lakh in the preceding quarter, while revenue from operations was nil and other income of Rs 15.51 lakh accounted for all reported income.
Know Sabrimala Industries India inside out
Results, valuation, peers and who's buying, in one view.
What were Sabrimala's Q2 profit and income figures?
Sabrimala recorded profit before tax of Rs 9.82 lakh and net profit of Rs 7.35 lakh in the quarter ended 30 September 2026. Net profit was lower than Rs 11.68 lakh in the quarter ended 30 June 2026 and Rs 11.77 lakh in the quarter ended 30 September 2025, representing declines of 37.1% sequentially and 37.6% year on year.
Total income fell to Rs 15.51 lakh from Rs 20.48 lakh in the June 2026 quarter and Rs 20.93 lakh a year earlier. Revenue from operations was nil in each of the three quarterly periods, leaving other income as the whole of total income in the September 2026 quarter.
Why did Sabrimala report profit without operating revenue?
Sabrimala reported a profit because Rs 15.51 lakh of other income exceeded total expenses of Rs 5.68 lakh by Rs 9.82 lakh before tax. The quarterly financial-results statement does not separately identify the underlying source of other income beyond its reported classification.
The segment statement shows that trading made a loss before tax and interest of Rs 5.68 lakh in the September 2026 quarter, compared with losses of Rs 4.89 lakh in June 2026 and Rs 5.38 lakh in September 2025. Other unallocable income net of unallocable expenses was Rs 15.51 lakh, offsetting the trading loss and resulting in reported pre-tax profit.
Sabrimala's tax expense was Rs 2.48 lakh in the latest quarter, compared with Rs 3.90 lakh in the preceding quarter and Rs 3.73 lakh a year earlier. Basic and diluted earnings per share, not annualised, were Rs 0.08 for the September 2026 quarter, against Rs 0.13 in June 2026 and Rs 0.14 in September 2025.
How did Sabrimala's first-half performance compare with last year?
Sabrimala's net profit for the half year ended 30 September 2026 was Rs 19.03 lakh, down from Rs 26.01 lakh in the half year ended 30 September 2025. Profit before tax declined to Rs 25.41 lakh from Rs 33.98 lakh as total income fell to Rs 35.99 lakh from Rs 41.59 lakh.
Expenses increased despite the lower income, with total expenses rising to Rs 10.58 lakh from Rs 7.61 lakh in the prior-year half year. Employee-benefit expense rose to Rs 3.79 lakh from Rs 1.66 lakh, while other expenses increased to Rs 6.79 lakh from Rs 5.74 lakh.
Revenue from operations for the six months was nil, compared with Rs 0.24 lakh in the corresponding period a year earlier. Tax expense declined to Rs 6.38 lakh from Rs 7.96 lakh, and basic and diluted earnings per share, not annualised, decreased to Rs 0.22 from Rs 0.30.
Got a follow-up? Ask IRIS
What do Sabrimala's cash flow and balance-sheet figures show?
Sabrimala used Rs 1.4773 crore in operating activities for the period ended 30 September 2026, compared with an operating outflow of Rs 90.63 lakh for the year ended 31 March 2026. Cash generated from operations was negative Rs 1.4431 crore in the latest half year, after a Rs 1.3283 crore increase in other assets, followed by Rs 3.43 lakh of direct taxes paid.
Investing activities generated Rs 1.3966 crore during the period ended 30 September 2026, including Rs 88.91 lakh reported under inter-corporate deposits given and Rs 35.99 lakh of interest received. The investing inflow partly offset the operating outflow, resulting in cash and cash equivalents of Rs 19.28 lakh on 30 September 2026, down from Rs 27.35 lakh at 31 March 2026.
Which segments and disclosures matter in Sabrimala's results?
Sabrimala identifies trading and acquisition of stressed assets as its reportable segments. Assets allocated to acquisition of stressed assets were Rs 5.8121 crore at 30 September 2026, up from Rs 4.6421 crore at 30 June 2026 and Rs 4.8401 crore a year earlier.
Unallocable corporate assets were Rs 6.245 crore at 30 September 2026, while total segment assets were Rs 12.0571 crore. Acquisition-of-stressed-assets liabilities were Rs 4.525 crore, unchanged from both 30 June 2026 and 30 September 2025, whereas total segment liabilities declined to Rs 4.6758 crore from Rs 5.1603 crore a year earlier.
Sabrimala's audit committee reviewed and recommended the unaudited standalone results, and its board approved them on 10 November 2026. Suresh & Associates issued an unmodified limited-review report, stating that its review had not identified matters suggesting the standalone statement lacked required disclosures or contained a material misstatement.
Conclusion
Sabrimala's Rs 7.35 lakh quarterly profit fell against both the preceding quarter and the prior-year quarter as other income declined to Rs 15.51 lakh and total expenses rose to Rs 5.68 lakh. With revenue from operations reported as nil and the trading segment posting a Rs 5.68 lakh loss before tax and interest, the reported profit depended on other unallocable income.
The next result to watch is whether Sabrimala reports operating revenue in either disclosed segment and whether operating cash flow changes from the Rs 1.4773 crore outflow recorded for the period ended 30 September 2026. Management also said it will continue monitoring labour-code developments and assess any effect on employee-benefit liabilities, although its current assessment is that the codes should not result in a material increase in gratuity liability or past-service cost.